Costco Stock Could Surprise Investors Over the Next Several Years
Costco parking lots are packed, yet the stock sits well below its 52-week high while tariff headwinds and margin pressure cloud the outlook. Whether those forces are temporary noise or a real warning sign shapes everything about where shares go…


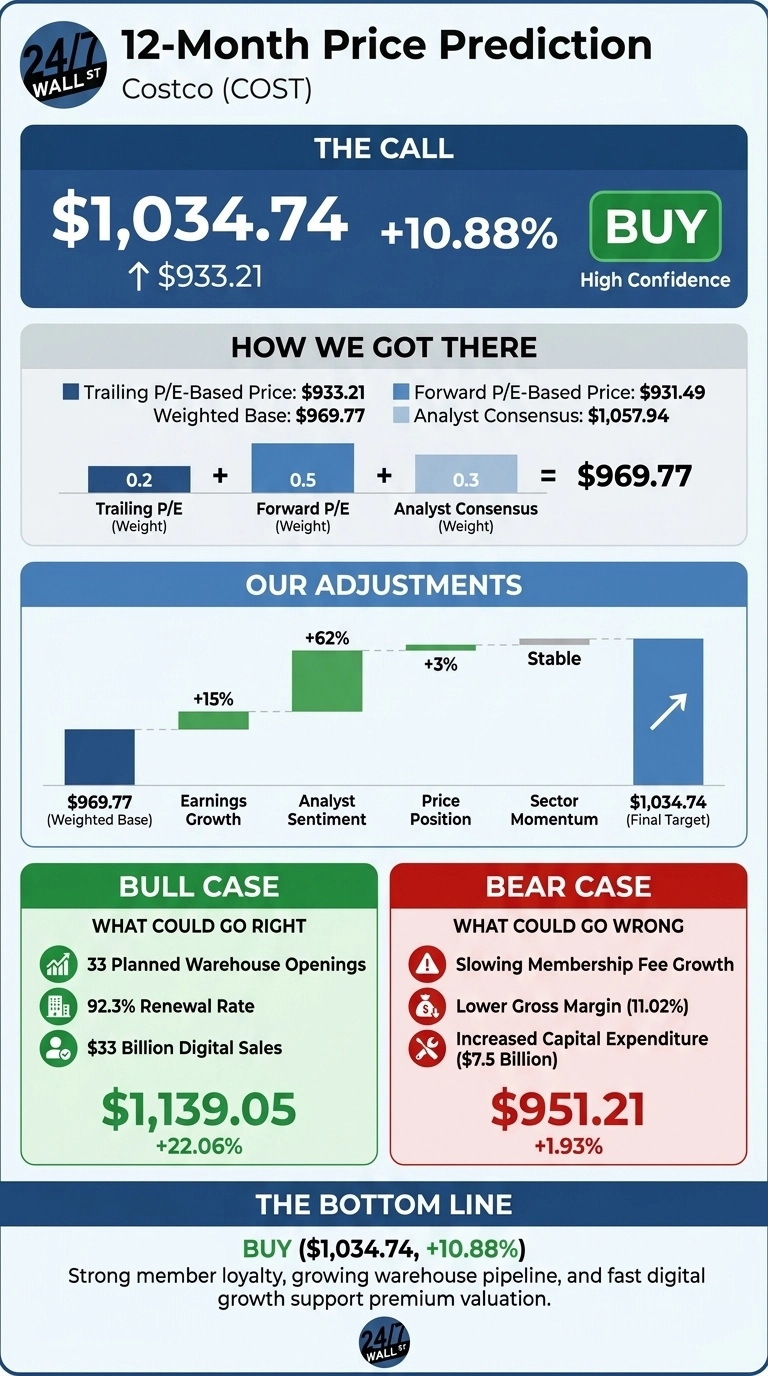
Our 24/7 Wall St. price target for Costco (NASDAQ:COST | COST Price Prediction) is $1,034.74. That means 10.88% upside from the $933.21 reference price. Our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $933.21 |
| The Price Target from 24/7 Wall St. | $1,034.74 |
| Upside/Downside | 10.88% |
| Recommendation | BUY |
| Confidence Level | 90% |

Costco just finished fiscal 2026 with revenue of $303.15 billion, up 10.14%, and GAAP EPS of $20.76. At about 41x forward earnings, the stock is priced at a premium. Our model finds that member loyalty, a growing warehouse pipeline, and fast digital growth support that premium.
Packed Parking Lots, Lagging Shares
Business Insider called this the “Costco conundrum: Packed parking lots and a falling stock.” Shares have gained 2.22% over the past week, 3.21% over the past month and 10.08% year to date. Over the past year they are up 4.36%. The 52-week range runs from $840.35 to $1,094.76.
Fourth-quarter revenue reached $95.72 billion, beating estimates of $94.85 billion. EPS came in at $6.75, ahead of the $6.53 estimate. That figure includes a $0.15 non-recurring tariff refund benefit. Comparable sales rose 6.7% excluding gas and FX, and Costco has now beaten estimates for five consecutive quarters.
Why Bulls See $1,139 Ahead
The bull case reaches $1,139.05, a 22.06% return. Costco plans 33 warehouse openings in fiscal 2027 as it works toward 30 net new warehouses per year.
Paid executive members climbed 9.4% to 42.3 million, and the U.S. and Canada renewal rate reached 92.3%. Digitally enabled sales topped $33 billion. Traffic from AI search grew at a triple-digit rate and converts better than any other source.

Analysts lean bullish, with 24 Buy or Strong Buy ratings against 2 Sell ratings. Firm-level targets were unavailable. Costco also raised its quarterly dividend to $1.47 from $1.30.

What Could Hold Costco Back
The bear case sits at $951.21. Membership fee growth slowed to 7.3% from 14% in Q1 as the benefit from the last fee increase faded. Gross margin slipped to 11.02% from 11.13%, largely from a $152 million LIFO charge versus $43 million prior year.
Core-on-core margins rose 18 basis points. Capex is set to rise to roughly $7.5 billion, but management expects capex growth to slow after fiscal 2027.
Is Costco Worth the Premium Over Walmart and BJ’s?
Walmart (NASDAQ:WMT) makes a useful comparison because Sam’s Club competes directly for warehouse members. Walmart trades at about 39 times earnings while growing quarterly revenue 5.94%. Costco is growing revenue roughly twice as fast at a similar multiple, so our target looks reasonable.
BJ’s Wholesale Club (NYSE:BJ) runs the same membership model. Its comparable sales excluding gas rose only 3.1%, compared with Costco’s 6.7%. Membership fee income grew 9.9%. Costco’s stronger core growth supports its premium, and our target looks modestly conservative next to BJ’s.
Costco Price Prediction 2026-2030
I’m sticking with the 24/7 Wall St. price target of $1,034.74, a buy rating and 90% confidence. Member loyalty is the deciding factor.
I’d view shares as attractive if renewal rates stay near record highs and new warehouses open on schedule. I’d turn cautious if fee income slows further without growth in spending per member. The data supports the bullish argument.
Here is where our model projects Costco could trade if current trends hold. The 2027 through 2030 figures follow the model’s base-case path as of each October.
| Year | The Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month target) | $1,034.74 |
| 2027 | $1,036.43 |
| 2028 | $1,124.89 |
| 2029 | $1,218.03 |
| 2030 | $1,296.52 |
The projections rest on Costco continuing to execute its current strategy. Faster growth in Asia could push results higher, while a lower valuation multiple could brings them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.