Prediction: This AI Stock Could Hit $1,000 Before 2030
Marvell Technology has already delivered 2,100% returns over a decade and 216% gains this year alone, but reaching $1,000 demands something far more ambitious than momentum. Here is what the math actually requires.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) is one of the purest ways to own the AI data center buildout. Its Data Center segment brought in $2.1715B last quarter. That was up 46% year over year and made up 79% of total revenue.
The stock has kept pace, rising 216.55% year to date. Wall Street’s target, though, sits just above the latest $272.29 share price. So can Marvell reach $1,000 before 2030?

Why Marvell Shares Are Stalling Below Their 52-Week High
Valuation is the problem: shares pulled back from a 52-week high of $329.80 and trade at 90 times trailing earnings. The stock is up 30.09% over the past month but only 2.55% over the past week. Momentum is fading as the share price closes in on analyst targets.
With a beta of 2.253, Marvell moves more than twice as much as the market. Management guided Communications revenue to fall in the low to mid-teens next quarter, and customer concentration remains a real exposure.
Wall Street Sees Modest Upside. I Think It’s Underpricing Custom Silicon
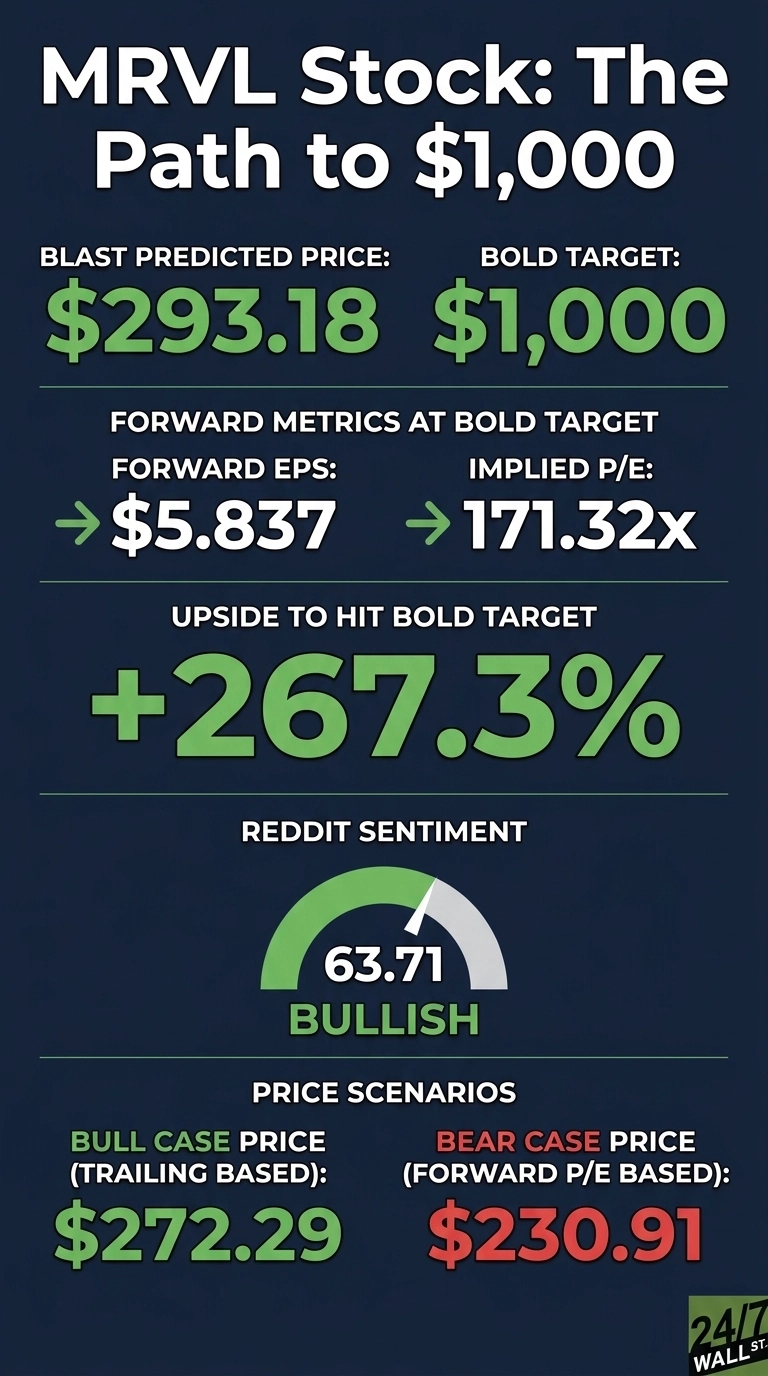
The consensus target is $293.88. The breakdown is 8 Strong Buy ratings, 32 Buy calls, 6 Holds and zero Sells. The base case from our model is $293.18, or 7.67% upside. Analysts’ one-year targets span $224.30 to $353.70. Confidence in the model stands high at 0.9.

I think analysts are behind the curve. Bullish sentiment sits at 87%, while earnings growth adds 0.03 to our factor. Meanwhile, the FY2028 EPS estimate has rose from $6.1726 to $6.7609 in 90 days, with 33 upward revisions in the past month. Price targets usually follow revisions like that.
Here’s What It Takes for Marvell to Reach $1,000
Reaching $1,000 from today’s price of $272.29 would require a gain of 267.3%.
With forward EPS of $5.837, a price of $1,000 implies a forward P/E of 171x. The base case already implies 83x, so the bold target requires 89x of additional multiple expansion. That’s too much on today’s earnings.
The realistic path runs through earnings growth. On FY2028 estimates, $1,000 works out to 148x. At a reasonable 40x, Marvell would need roughly $25 in EPS by decade’s end. Our adjustment factor of 1.136 reflects strong tech-sector momentum, but a mega-cap drag cut it by 50%.
Catalysts support that path: management expects FY2028 revenue to grow about 50% and custom revenue to more than double. An expanded Alphabet (NASDAQ:GOOGL) Google partnership includes a warrant for up to 7% of Marvell’s shares, tied to revenue milestones.
CEO Matt Murphy said there is “a lot of upside bias in those numbers in fiscal ’29 and beyond in custom.” We should learn more at Investor Day on October 6, 2026.
The chief risk is that hyperscalers bring more chip design in-house and reduce Marvell’s custom pipeline.
Where Marvell Trades Today vs Its Earnings Power
On forward EPS, Marvell trades at about 47x. That’s a premium multiple, backed by guided growth of about 60% in Data Center revenue this fiscal year.
Shares sit much closer to the $329.80 high than the $70.64 low. Over 10 years, the stock has returned 2109.88%. A company that compounds earnings this quickly can grow into an expensive multiple.
$1,000 Is a Stretch, But Here’s Why It’s Possible
Reaching a $1,000 share price means a 267.3% rose. Our five-year bull case reaches $514.53, so this is a stretch.
The thesis needs three things: custom revenue beats the $10 billion-plus FY2029 framework, operating margins reach the top of the 38% to 40% target range, and scale-up optics ramp on schedule. A decline in AI capital spending would undermine the thesis.
You shouldn’t expect returns like this every year, but we’ve outlined the blueprint for how Marvell Technology could reach $1,000 in 2029 (we reverse-engineered what the biggest tech winners looked like early and put the pattern in a free playbook here).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.