Intel Stock Is Still a Turnaround Bet. Here’s What I See Ahead
Intel shares have already surged more than 200% this year, but Wall Street still calls the stock a hold. Here is what bulls and skeptics are each missing about where INTC goes from here.

Under CEO Lip-Bu Tan, Intel (NASDAQ:INTC | INTC Price Prediction) has rebuilt itself around three assets: the x86 CPU franchise, advanced packaging and a U.S. wafer foundry network. That strategy paid off in the second quarter, when revenue rose 25.4% to $16.13 billion.
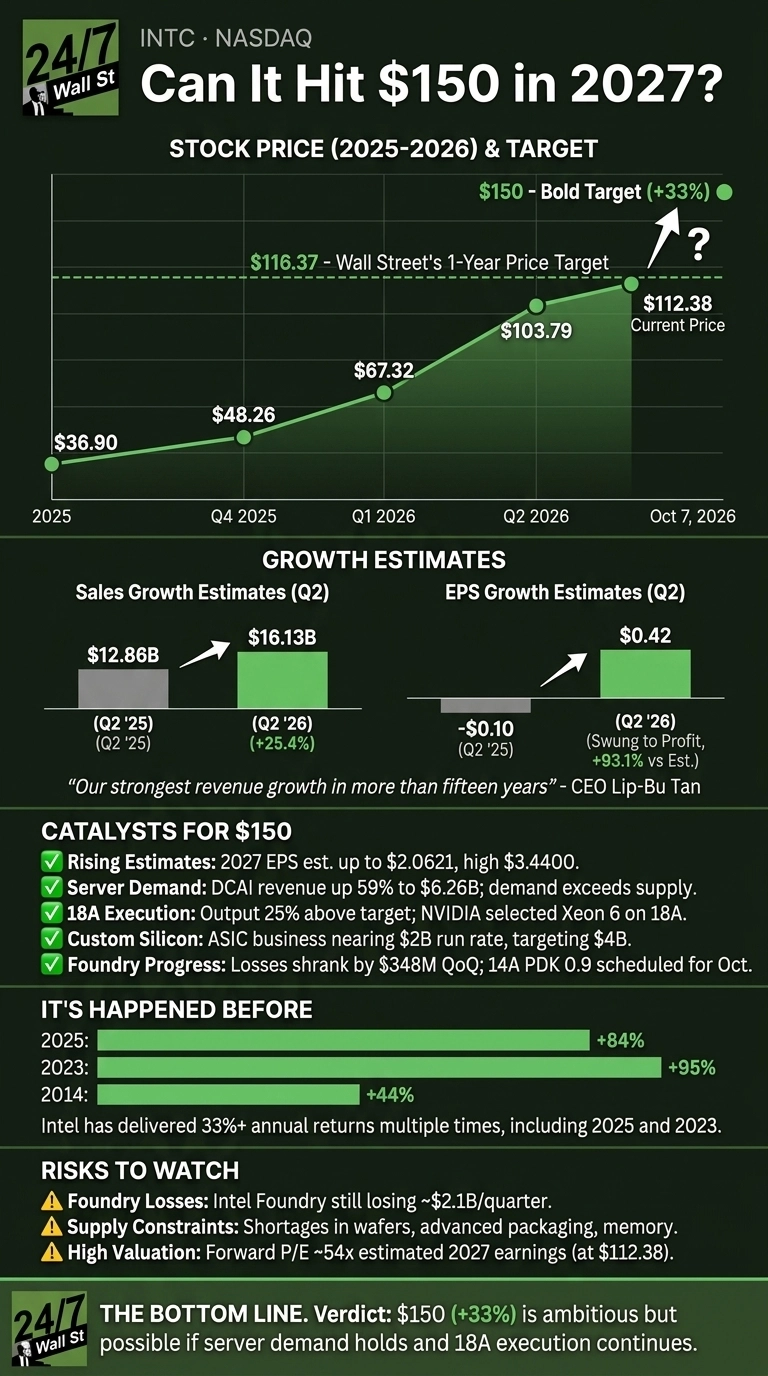
Tan called it “our strongest revenue growth in more than fifteen years.” Shares are up 204.55% year-to-date to $112.38, after an 84% gain in 2025. Here’s what I think it would take for Intel to reach $150 per share over the next year.

Analysts Are Cautious, but Their Estimates Keep Climbing
Wall Street’s average price target is $116.37, just 3.6% above today’s price. 32 analysts rate the stock a hold, while 14 rate it a buy.

The estimates look more bullish: analysts project $1.5203 in EPS for 2026 and $2.0621 for 2027, which works out to 36% growth. Just three months ago, the 2027 estimate stood at $1.5322.
Management says Intel has beaten its financial expectations for seven consecutive quarters, including Q2 non-GAAP EPS of $0.42 against a $0.2175 estimate. A run like that suggests results will likely beat forecasts.

Here’s What It Takes for Intel to Reach $150
At $112.38, Intel trades at about 54x estimated 2027 earnings. At $150, that would rise to roughly 73x. That’s a rich multiple.
Still, Intel’s PEG ratio of 0.501 points to growth that justifies a premium, and the highest 2027 estimate is $3.44. If Intel keeps beating, the effective multiple at $150 shrinks fast.
Several catalysts could push Intel to $150:
- Server demand exceeding supply: Data Center and AI revenue rose 59% to $6.26 billion at a 40% operating margin. CFO David Zinsner said, “Our outlook for server CPU demand has improved again since our last earnings report.”
- 18A execution: 18A output ran about 25% above target. NVIDIA (NASDAQ:NVDA), which invested $5B in Intel stock, chose Xeon 6 as the host CPU for its DGX Rubin NVL8 systems.
- Custom silicon: The ASIC business is nearing a $2 billion run rate, and management is aiming for $4 billion in a market it sizes at over $100 billion.
- Foundry progress: Foundry losses shrank by $348 million from the prior quarter, and Intel 14A PDK 0.9 was scheduled for October. A major external customer win would change the story.
Intel’s History Shows a 33% Gain Is Within Reach
Getting to $150 requires a 33% gain. Intel has beaten that in six calendar years since 2000: 107% in 2003, 34% in 2007, 44% in 2009, 44% in 2014, 95% in 2023 and 84% in 2025.
Shares hit $142.35 within the past 52 weeks, so $150 is only a little above levels the stock has already reached. Its beta of 2.23 means big moves can happen in either direction.

$150 Is a Stretch, but Here’s Why It’s Possible
(we reverse-engineered what the biggest tech winners looked like early in a free playbook you can get here: The Next Nvidia Playbook)
Reaching $150 means a 33% gain, well beyond Wall Street’s target. The bull case rests on rising estimates, a long beat run, server demand that tops supply and 18A yields tracking ahead of expectations.
Hurdles remain: Intel Foundry still loses about $2.1B a quarter, and shortages of wafers, substrates and memory could limit near-term growth.
Keep an eye on the third-quarter earnings report for updates on supply and 14A customers. Such gains won’t happen every year, but we’ve outlined the plan for how Intel could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.