My Position on Tesla Will Not Change Until Two Things Happen
Tesla is spending at a pace it has never attempted before, and earnings are falling while the bills pile up. Two specific conditions have to be met before this stock becomes a conviction buy, and right now neither one has…

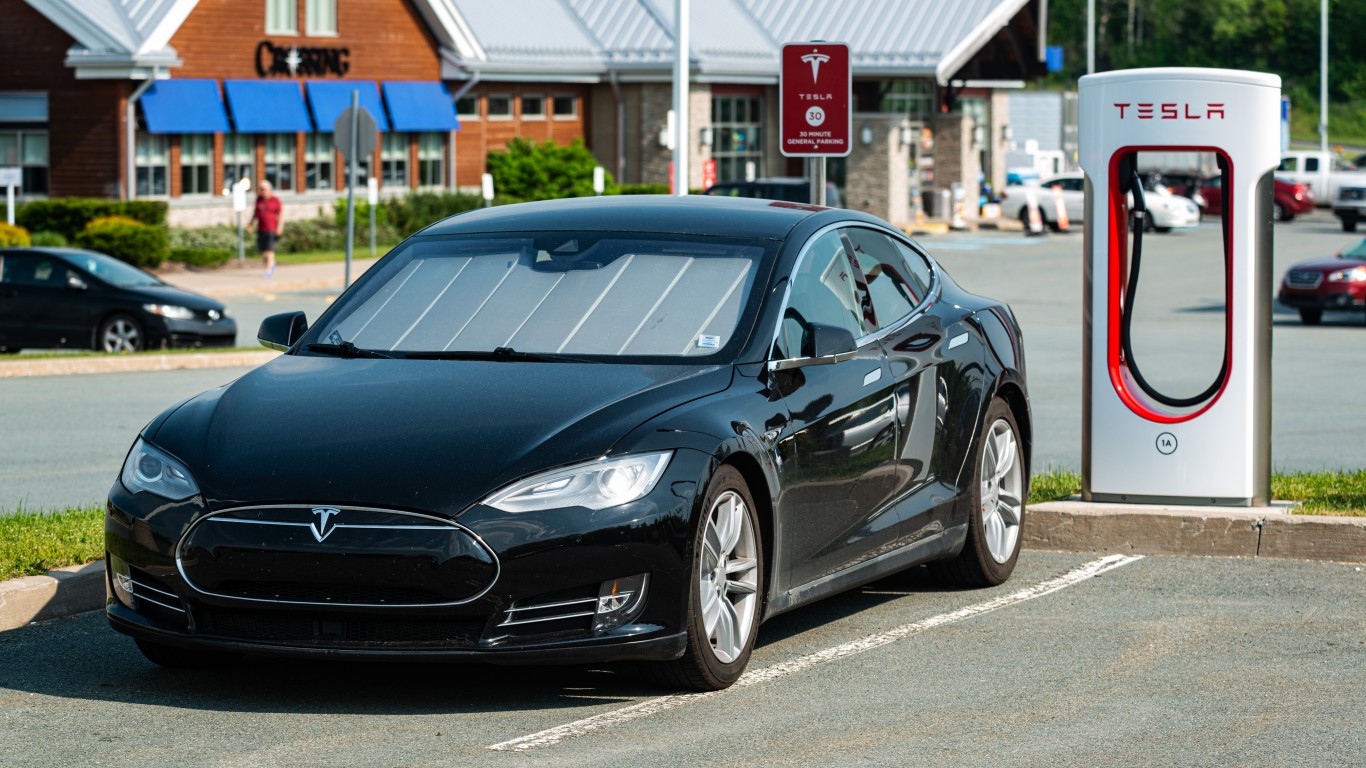
Tesla (NASDAQ:TSLA | TSLA Price Prediction) trades at $375. Two developments would change the picture: free cash flow turns positive again, and Robotaxi starts producing revenue at scale. Tesla is now spending at a pace it has never tried before, and its earnings are falling while the spending ramps.
Tesla sells electric vehicles, grid batteries and Full Self-Driving (FSD) software. It is also building Robotaxi, Cybercab and the Optimus robot. Last quarter, revenue rose 25.52% to $28.24 billion and beat estimates. EPS of $0.33 missed expectations of $0.5367, and free cash flow fell to negative $1.09 billion.
Record Deliveries and a Cash Pile Power the Bull Case
Demand is healthy. Deliveries hit a record 480,126, and Tesla ended the quarter with “our largest order backlog since 2023.” FSD subscriptions climbed 56% to 1.48 million. Services margin reached an all-time high of 14.1%, and energy storage deployments rose 41%.
Robotaxi now runs in seven U.S. metros. It has logged more than 380,000 miles of unsupervised driving with “zero notable incidents,” according to management. Tesla also holds $43.52 billion in cash. A forward P/E of 159, compared with a trailing P/E of 350, shows that analysts expect earnings to grow sharply.
A $25 Billion Spending Wave Is Squeezing Earnings
Operating margin fell to 1.4% as operating expenses jumped 47%. Management expects capital spending this year to top $25 billion and to keep rising for two or three years. Tesla is also arranging debt facilities that would let it borrow up to $30 billion. Automotive gross margin excluding credits slipped to 16.3% from 19.2% the quarter before.
Some skeptics argue the stock is worth far less. Investor George Noble said “the cyber taxi thing is completely overcooked” and put his sum-of-the-parts value at $30 to $60 a share. Management expects the early Optimus ramp to be “quite flat and long.”
Robotaxi Miles Are Piling Up While Revenue Proof Lags
The core business is working. Deliveries, FSD and services all grew. No one has yet shown how Robotaxi miles become profit. Management says unsupervised miles are growing more than 10% a week. Over the next two to four quarters, investors should watch for fleet revenue disclosures and signs that capital spending is paying for itself.
Down 16.61% This Year While the S&P 500 Gained 13.5%
Tesla is down 16.61% year to date, while the S&P 500 is up 13.5%. Over one year, the stock is down 14.52%, while the index has gained 14.98%. The stock sits under its 200-day average of $392.19.
The consensus target of $392.42 implies upside. Here is how 43 analysts rate the stock:
- Strong Buy: 4
- Buy: 15
- Hold: 20
- Sell: 2
- Strong Sell: 2
Cash Flow and Robotaxi Revenue Are the Two Tests That Matter Next
At $375, Tesla faces two tests.
Free cash flow must turn positive and stay there for consecutive quarters, even with capital spending above $25 billion. If operating margin climbs from 1.4%, the spending is paying off.
Robotaxi must report real fleet revenue, with Cybercab moving from pilot builds to volume production. Unsupervised miles prove the technology works; revenue proves the business model works.
A Robotaxi breakthrough could lift the stock quickly. The valuation also carries risk: Tesla still trades at 350 times trailing earnings while its cash flow is negative (riding a story stock at that multiple is fine as long as you plan the exit, something our free bubble survivor’s handbook walks through in detail). If both conditions are met, the investment case strengthens. If cash burn grows with no fleet revenue, it weakens.
The vision is fully priced in, and the proof has not arrived yet.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.