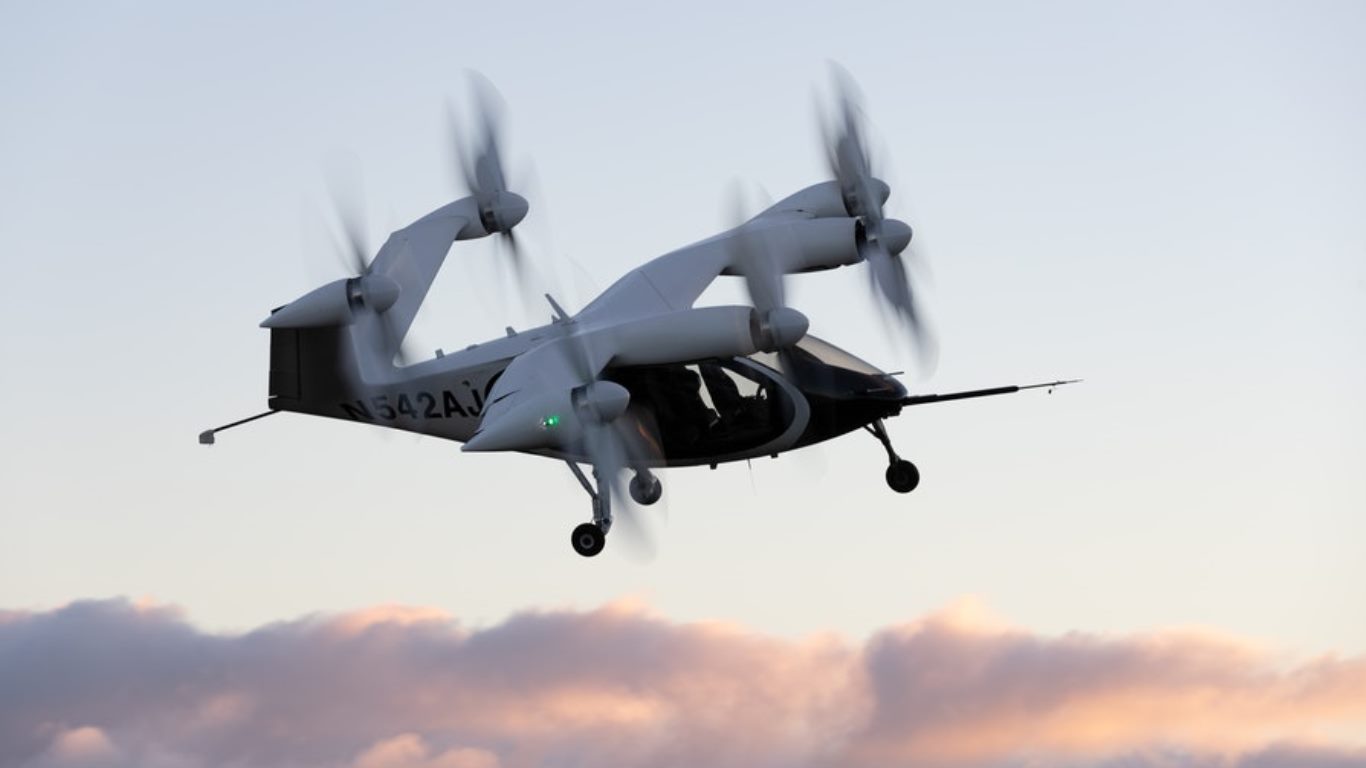
Joby Could Be Worth Far More If One Piece of the Puzzle Falls Into Place
Joby Aviation has already beaten revenue estimates, started flights in Texas, and locked in a manufacturing deal with Toyota, yet the stock sits at its 52-week low. One regulatory decision separates a potential doubling from a collapse toward book value.

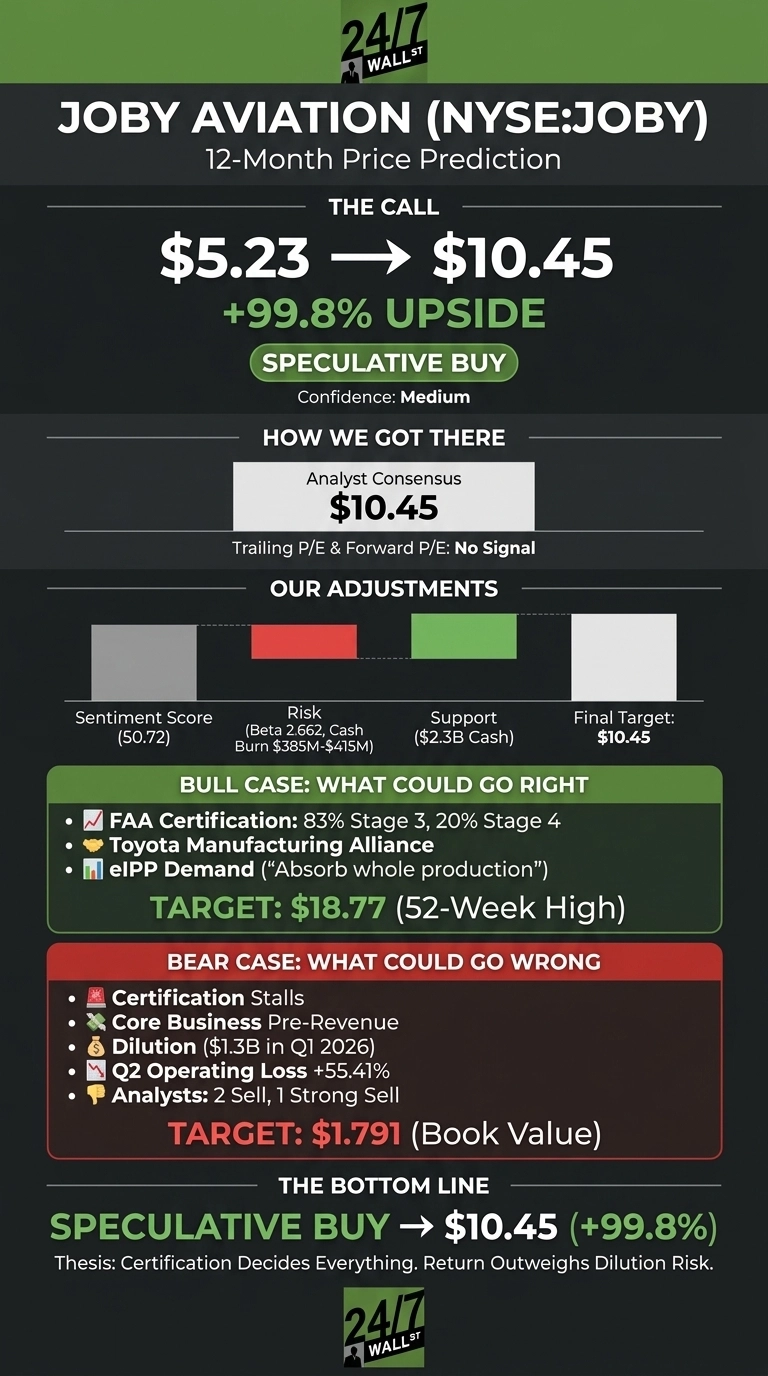
Joby Aviation (NYSE:JOBY | JOBY Price Prediction) trades at $5.23, which is also its 52-week low. The 24/7 Wall St. price target for Joby is $10.45 over the next 12 months, meaning 99.8% upside.
| Metric | Value |
|---|---|
| Current Price | $5.23 |
| Price Target from 24/7 Wall St. | $10.45 |
| Upside/Downside | 99.8% |
| Model Rating | Speculative BUY |
| Confidence Level | Medium |
The model gives Joby a speculative buy rating with medium confidence.
Everything depends on one piece of the puzzle: FAA type certification, which would turn Joby’s air taxi from a test program into a fleet that makes revenue. Until that happens, almost all of Joby’s sales come from Blade, and the stock price suggests investors expect certification to slip.

A 60% Slide Even After a Revenue Beat and Flights in Texas
Shares fell 12.1% over the past week and 18.54% over the past month. They are down 60.38% year to date and sit well below the 52-week high of $18.77.
In Q2, revenue came in at $38.64 million against a $30.38 million estimate. EPS of -$0.25 missed expectations of -$0.2345. Management raised full-year revenue guidance to $115 million to $125 million after Blade seats rose more than 50%. Joby has since started its eIPP flights in Texas as planned, but the shares have kept falling.
Why Bulls See $18.77 Again
Joby has completed 83% of Stage 3 certification work and 20% of Stage 4. CFO Rodrigo Brumana said the eIPP markets alone “could absorb the whole production for quite some time.”
Joby also has a manufacturing alliance with Toyota (NYSE:TM), with a $250 million direct investment expected, and plans to double output to four aircraft per month in 2027. If conditions improve, a return to the $18.77 high is realistic.

What Could Push Joby Toward Book Value
The core eVTOL business still has no revenue. Q2 operating losses rose 55.41% year over year, and Joby raised about $1.3 billion in Q1 alone, which diluted existing shareholders. Among analysts, there are 2 Sell ratings and 1 Strong Sell.

If certification stalls, the stock could fall toward book value of $1.791 per share. On the other side of the argument, management says Blade is not currently consuming cash, and spending can be managed to match targets.
Joby vs. Archer and EHang: Paying Up for Revenue
Archer Aviation (NYSE:ACHR) is Joby’s most direct eVTOL rival. It reported Q2 revenue of only $5 million and trades at 1.74x book, compared with Joby at 3.525x. Joby’s premium comes from Blade’s revenue, which Archer lacks.
EHang (NASDAQ:EH) already holds a type certificate, yet its Q2 revenue fell 46.56%. EHang also withdrew its 2026 guidance after a crash in China made regulators more conservative. Certification is the main hurdle, but it does not guarantee revenue on its own.
| Company | Market Cap | Q2 2026 Revenue |
|---|---|---|
| Joby | $5.21B | $38.64M |
| Archer | $3.61B | $5.0M |
| EHang | $230M | $11.56M |
Next to these peers, the 24/7 Wall St. price target looks reasonable. Joby has the most revenue in the group and the richest liquidity.
Joby Price Prediction 2026-2030
The 24/7 Wall St. price target of $10.45 comes with a speculative buy rating and medium confidence. The rating stands if eIPP flights move on to paying passengers and Stage 4 progress picks up.
I’d turn conservative if certification slips into 2027 and Joby needs to raise more money at these prices. I think the return from certification outweighs the dilution risk.
Our model assumes Joby makes certification and then rose 30%, 25%, and 20% a year in the three years after reaching our target. On that basis, here is where Joby could trade:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $7.84 |
| 2027 | $10.45 |
| 2028 | $13.59 |
| 2029 | $16.98 |
| 2030 | $20.38 |
The projections rest on Joby continuing to execute on its current plan. The timing of certification and how fast production increases could move results far above or below these figures.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.