PepsiCo Stock Has Fallen Out of Favor. That Could Create an Opportunity
PepsiCo sits near a 52-week low after a brutal guidance cut, yet its international business keeps firing on all cylinders while the stock trades at a steep discount to its closest rivals. The question is whether Wall Street has already…


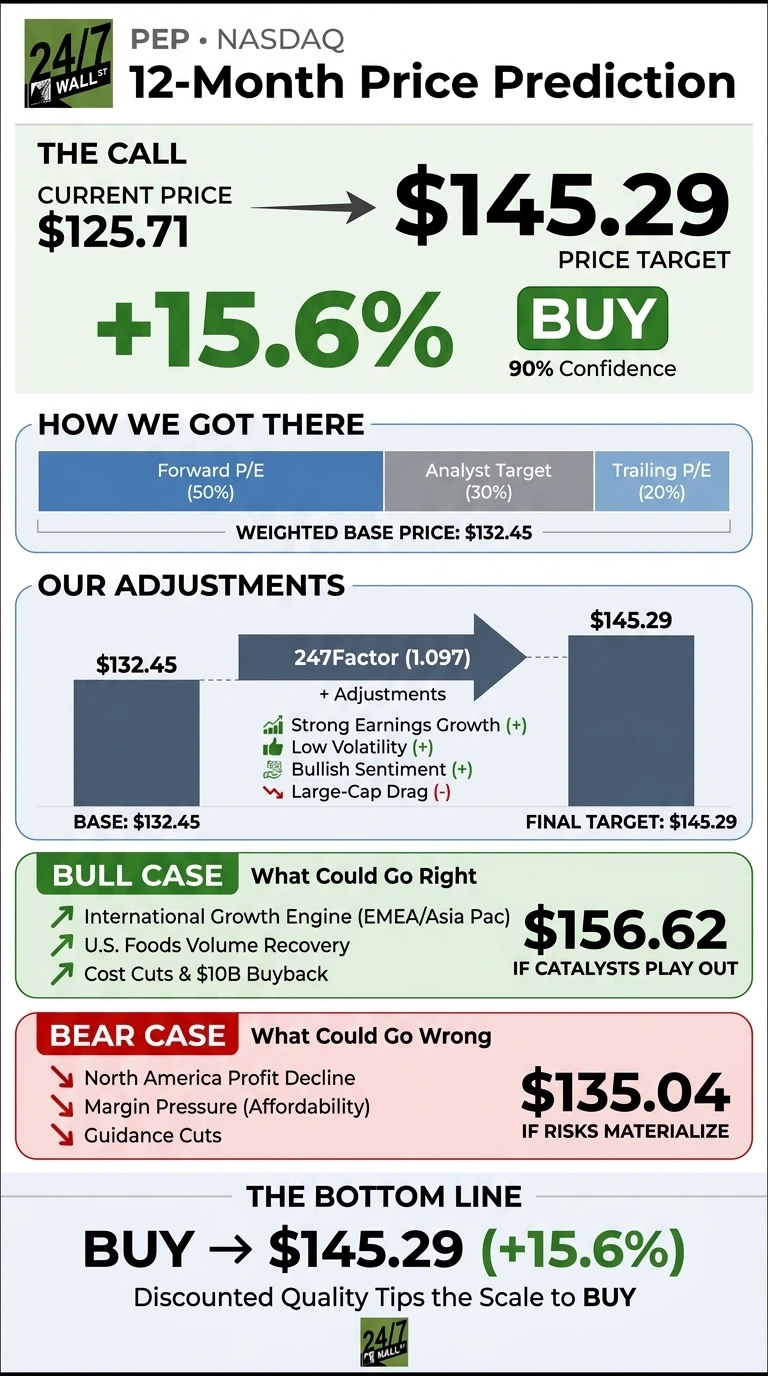
The 24/7 Wall St. price target for PepsiCo (NASDAQ:PEP | PEP Price Prediction) is $145.29. That is about 15.6% above today’s $125.71 share price. The stock wins a buy rating with high confidence from our model.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $125.71 |
| Price Target from 24/7 Wall St. | $145.29 |
| Upside | 15.6% |
| Recommendation | BUY |
| Confidence Level | 90% |
PepsiCo trades at a forward multiple of 14x and yields 4.36%. The stock has beaten EPS estimates 5 quarters running. North America is the problem. International growth, cost cuts and a valuation correction offer a credible path back toward its old range.

A Guidance Cut Left PepsiCo Near Its 52-Week Low
Shares are down 9.2% over the past month and 9.75% year to date. They traded at $143.30 when second-quarter results came out in July. The stock sits 24.5% below its $166.41 52-week high and just 1.8% above its $123.47 low.
Third-quarter adjusted EPS of $2.34 beat the $2.30 estimate. Revenue rose 5.6% to $25.27 billion. Management cut core EPS growth guidance to 2.5% to 3.5%, down from 5% to 7%. CEO Ramon Laguarta said “our business in North America performed below our expectations and represents a meaningful opportunity for improvement.”
Why Bulls See $156 Within Reach
International is the growth engine. EMEA and Asia Pacific each posted 9% organic growth, and LatAm Foods rose 14%. Management expects international revenue to top $40 billion this year. February snack price cuts of up to 15% returned U.S. foods to volume growth.
A $10 billion buyback, cost cuts and a 54th consecutive dividend increase add support. Our bull case reaches $156.62. Wall Street shows 18 Hold ratings against 5 Buy or Strong Buy ratings.

North America Is the Risk Worth Watching
Frito-Lay North America’s core operating profit fell 12%, and North American beverage volume dropped 2%. Core operating margin contracted 35 bps, with a tariff refund adding 4 points.
Reported operating income rose 19.36%. Much margin pressure stems from calculated affordability investments. The bear case of $135.04 still sits above today’s price.

PepsiCo Trades at a Discount to Coca-Cola and Mondelez
| Company | Forward P/E | Dividend Yield |
|---|---|---|
| PepsiCo | 14x | 4.36% |
| Coca-Cola | 25x | 2.41% |
| Mondelez | 18x | 3.37% |
| Keurig Dr Pepper | 12x | 2.96% |
Coca-Cola (NYSE:KO) is PepsiCo’s direct soda rival with a 34.9% operating margin wins a premium multiple.
Mondelez International (NASDAQ:MDLZ) competes in global snacks and commands a higher multiple.
Keurig Dr Pepper (NASDAQ:KDP) is cheaper on forward earnings but its 5.1% return on equity trails PepsiCo’s 42.86% by a wide margin. Our target means about 16x forward earnings, below both Coca-Cola and Mondelez.
PepsiCo Price Prediction 2026-2030
A buy rating with a 24/7 Wall St. price target of $145.29 and 90% confidence. A defensive franchise with a 4%-plus yield trading at a peer-group discount tips the scale.
North American volume stability and margin-protecting cost cuts would strengthen the case. A further guidance cut from management in early 2027 would hurt it.
Our model projects PepsiCo could trade as follows in the base case:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $132.62 |
| 2027 | $144.90 |
| 2028 | $158.62 |
| 2029 | $173.03 |
| 2030 | $185.18 |
PepsiCo’s continued execution of its current strategy supports these projections. A faster North American recovery could drove results above these figures, while lasting input-cost inflation could pull them below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.