Prediction: ServiceNow Could Be Building Its Next Billion-Dollar Growth Engine
ServiceNow's AI business just crossed a milestone that has analysts arguing over whether the stock's recent selloff is a gift or a warning sign. The answer depends on one number management has promised to hit before year-end.

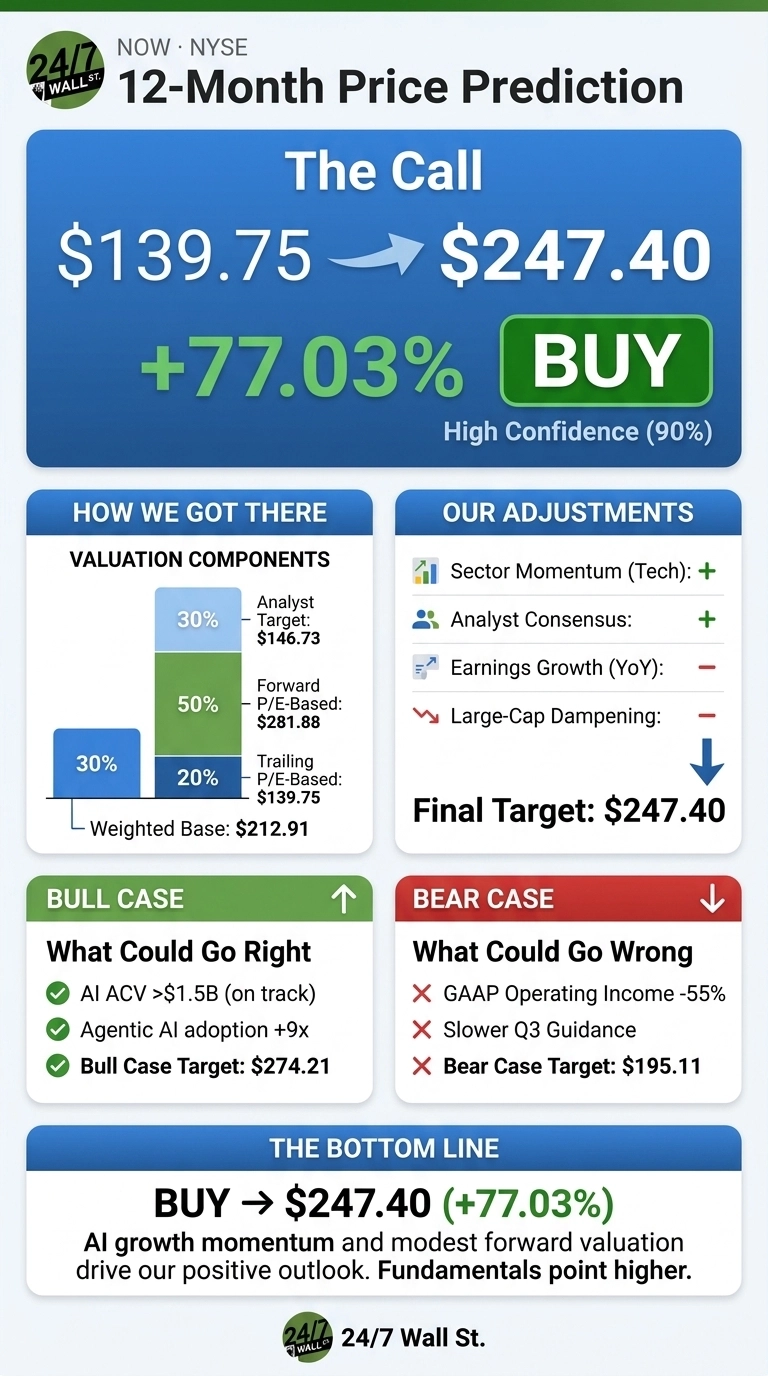
ServiceNow (NYSE:NOW | NOW Price Prediction) trades at $139.75. The 24/7 Wall St. price target of $247.40 implies 77.03% upside over the next 12 months, and our model rates the stock a buy.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $139.75 |
| 24/7 Wall St. Price Target | $247.40 |
| Upside/Downside | 77.03% |
| Recommendation | BUY |
| Confidence Level | 90% |
The model has high confidence in this call. It rests on AI. In Q2, annual contract value (ACV) from ServiceNow AI passed $1B, and management said it is “on track to beat our target of one and a half billion ACV by the end of 2026.”
That engine sits on top of subscription revenue growing 24.5% per year. The share price has fell behind those results.

Shares Are Climbing Back After a Brutal Year
ServiceNow is up 2.4% over the past week and 5.11% over the past month. It is still down 7.91% year to date and 22.86% over 12 months. It trades about 24% below its 52-week high of $192.97 and well above its low of $81.24.
Q2 revenue rose 24% to $3.987B. Non-GAAP EPS came in at $0.90, ahead of the $0.86 estimate. Current remaining performance obligations (cRPO), which track contracted revenue due over the next 12 months, rose 21% to $13.20B. Management also raised full-year subscription guidance to $15.76-$15.78B.

Why Bulls See $274 Within Reach
Agentic AI customer adoption rose 9x over the last nine months, with AI ACV growing over 40% quarter over quarter. ServiceNow’s Level 1 support agents close 80 to 85% of service requests without human help.
The Armis and Veza acquisitions add security and identity products to a cybersecurity business management called “billion-dollar-plus.” The long-term goal is $30B+ subscription revenue by 2030. Analysts are firmly bullish, with 10 Strong Buy and 35 Buy ratings. Our bull case reaches $274.21.

GAAP Profits Are the Risk to Keep an Eye On
GAAP operating income fell 54.75% to $162M, and GAAP subscription gross margin slipped to 73.5% from 80%. Part of Q2’s strength came from federal revenue pulled forward from Q3, with guidance pointing to slower growth of +20.5% next quarter.
The pressure comes from amortization and stock-based pay linked to the Moveworks, Veza and Armis deals. Free cash flow still grew 20.53%. The bear case still lands at $195.11.
Is ServiceNow Pricier Than Salesforce, Workday and Palantir?
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| ServiceNow | 28x | 24% |
| Salesforce | 14x | 10.8% |
| Workday | 18x | 12.8% |
| Palantir | 85x | 92.8% |
Salesforce (NYSE:CRM) competes directly with ServiceNow’s 2 billion ACV CRM business at half the multiple but less than half the growth.
Workday (NASDAQ:WDAY) competes for HR workflow budgets at roughly half ServiceNow’s growth rate.
Palantir (NASDAQ:PLTR) trades at 85x forward earnings as the premium enterprise-AI benchmark. ServiceNow sits between these names: costlier than slower-growing application peers and far less than the AI leader, making our target reasonable.
ServiceNow Price Prediction 2026-2030
The 24/7 Wall St. price target of $247.40 carries a buy rating at 90% confidence. The deciding factor is AI growth coupled with a modest forward multiple.
Conviction would grow if AI ACV tops $1.5 billion by year-end. Caution would rise if cRPO growth slows significantly below guidance. Right now, fundamentals point higher.
Our model projects the stock could trade at these levels if current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $144.16 |
| 2027 | $242.85 |
| 2028 | $368.90 |
| 2029 | $478.47 |
| 2030 | $581.16 |
ServiceNow’s ability to perform its AI and security strategy supports these projections. Faster AI rollout could add upside. Weaker federal spending or ongoing GAAP margin pressure could pull results lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.