Applied Materials Cratered in The last 3 Months: One Wall Street Sell Side Firm Predicts it Will Nearly Double Within 12 Months
Applied Materials just posted its fifth consecutive earnings beat while the stock cratered 22% in three months, and at least one Wall Street firm thinks that disconnect points to one of the more compelling setups in the chip equipment sector…

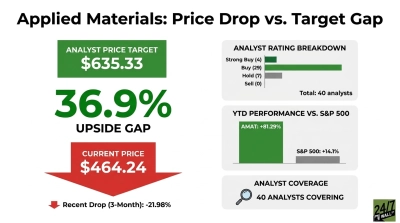
Applied Materials (NASDAQ:AMAT | AMAT Price Prediction) currently trades at $464.24, while Wall Street’s average price target stands at $635.33. That gap implies 36.9% upside.
Applied Materials builds the deposition, etch, inspection and packaging tools that chipmakers use to produce AI processors and high-bandwidth memory. Its latest quarter delivered revenue of $9.115 billion, up 24.8% year over year, and non-GAAP EPS of $3.50 against a $3.39 consensus. That was its fifth consecutive beat.
The business is accelerating while the stock falls, and investors need to know whether the market sees something analysts are missing.
An Investor Day Omission Deepened a 22% Three-Month Slide
Applied Materials declined to provide an industry spending forecast at its investor day, and shares fell 6.69% in a single session. Barron’s noted the stock was on pace to close lower for a sixth consecutive trading session. The one-week loss reached 12.45%, and the three-month decline stands at 21.98% from $595.06. Shares now sit 37.2% below their 52-week high of $738.88.
The pressure started earlier. Reuters reported that shares slipped after the August earnings report as an upbeat outlook failed to soothe investors seeking faster growth after a stellar run. Management also highlighted a hard constraint on the call: “It will be the availability of clean room at a high level that will determine what we can all ship next year.” With no spending forecast on offer, investors had to price that uncertainty themselves.
The weakness hit the whole group, but Applied took the most damage. Lam Research (NASDAQ:LRCX) fell 2.73% and KLA (NASDAQ:KLAC) dropped 3.22% on the same day, while the S&P 500 slipped just 0.01%.
Analysts Keep Raising Estimates as the Stock Falls
Analysts are focused on to AI-driven demand that management says stretches years out. Applied expects leading-edge foundry logic, DRAM and advanced packaging to represent “around 80% of wafer fab equipment growth in 2026 and 2027,” and projects packaging revenue to grow “more than 70% in calendar 2026.” DRAM revenue, including HBM packaging, grew 52% year over year. Fiscal Q4 guidance calls for revenue of about $10.25 billion and non-GAAP EPS of roughly $4.02. Customer visibility now includes “some conversations now extending to 2030.”
Revisions point higher. The fiscal 2027 EPS consensus has rose to $18.4658 from $16.5279 90 days ago, and the January-quarter estimate drew 18 upward revisions in the past week with none lower. The top fiscal 2027 estimate reaches $21.77, which supplies the earnings math behind the most aggressive near-doubling calls by HC Wainwright, with its $900 target price. Ratings break down as 4 Strong Buy, 29 Buy, 7 Hold and no Sells.
Rising estimates coupled with a falling price signal multiple compression, and at 23x forward earnings the stock still prices in sustained growth. Analyst targets are 12-month opinions and carry no guarantee.
Chip Equipment Peers Fell Together, and Applied Fell Hardest
The semiconductor equipment group sold off as a pack, so Applied belongs to a broader falls. It has simply dropped further.
Lam Research lost 9.82% over the past week. The stock trades at $301.11, versus a $375.81 average target, implying 24.8% upside. Ratings show 4 Strong Buy, 25 Buy and 6 Hold with no Sells. Wall Street sees less upside here than for Applied.
KLA fell 6.82% over the week and trades at $184 versus a $232.77 target, implying 26.5% upside. Its 5 Strong Buy, 14 Buy and 10 Hold ratings make it the most carefully rated name of the group. Its upside also trails Applied’s.
Western Digital (NASDAQ:WDC) is an adjacent AI-infrastructure play that sells hard drives. It has fallen 32.4% over three months. The shares trade at $380.71 versus a $668.50 target, implying 75.6% upside, with 4 Strong Buy, 17 Buy and 5 Hold ratings. Melius Research has the highest target on the Street at $1,050.
Western Digital carries the largest implied upside of the group. Among direct equipment peers, Applied offers the widest gap to consensus.
An 81% Year-to-Date Gain Still Leaves the S&P 500 Far Behind
Applied trades at $464.24 against a consensus target of $635.33, implying 36.9% upside across 40 analysts. The three-month decline of 21.98% sits alongside a 1.7% one-month gain, showing the damage arrived in two sharp waves.
Year to date, Applied is up 81.29% while the S&P 500 has gained 14.1%. Over one year, the stock has returned 112.71% against 17.35% for the index. The 50-day moving average of $489.74 now sits above the share price, with the 200-day average at $435.51.
Applied Materials Bull and Bear Cases Hinge on the 2027 Spending Outlook
Shares look more compelling if DRAM and advanced packaging ramp as guided and fiscal Q4 lands near $10.25 billion. That keeps the $18.4658 fiscal 2027 EPS path intact and makes a forward multiple near 23x look reasonable for this growth rate. A clear 2027 spending outlook would also remove the uncertainty behind this week’s drop.
The bear case gains weight if clean room shortages cap shipments, export controls squeeze China sales, or the investor day silence signals a weaker 2027 than analysts model. China already declined to 28% of revenue from 35%.
On balance, the data leans positive. Estimates are rising, guidance points higher, and the stock trades 37.2% off its high. The missing forecast is a real yellow flag, so management’s 2027 outlook is the next data point to keep an eye on.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.