Meta’s AI Spending Is Massive. The Payoff Could Be Even Bigger
Meta is pouring over $130 billion into AI while free cash flow craters and Reality Labs keeps bleeding billions. Whether that spending is a catastrophic overhang or the setup for a massive payoff depends on one number that most investors…


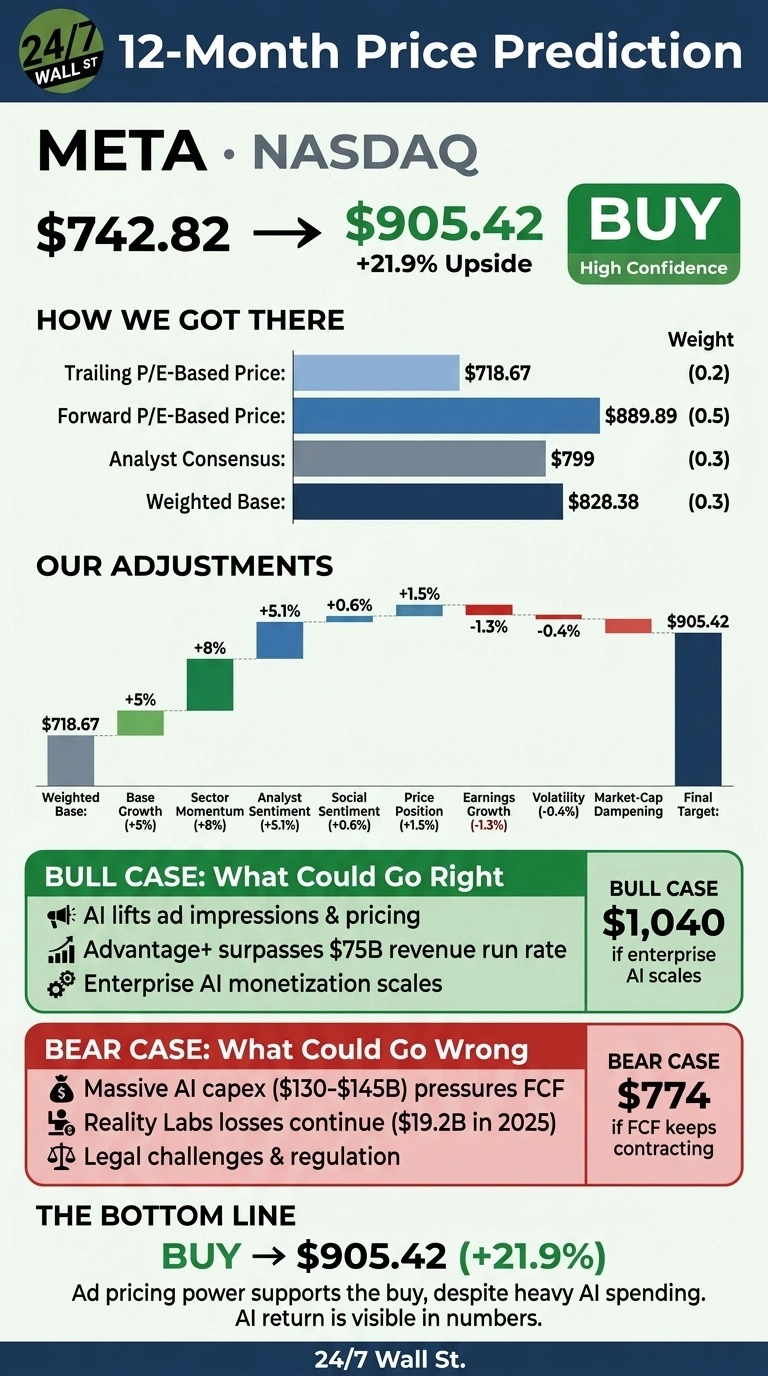
The 24/7 Wall St. price target for Meta Platforms (NASDAQ:META | META Price Prediction) is $905.42 over the next 12 months. That stands well above today’s price.
| Metric | Value |
|---|---|
| Current Price | $742.82 |
| Price Target from 24/7 Wall St. | $905.42 |
| Upside | 21.9% |
| Recommendation | BUY |
| Confidence Level | 90% |

Our model has high confidence in this call. Meta is spending heavily on AI, with 2026 capex forecast to $130-$145B, and the market spent most of the summer punishing that.
Our view is that the spending already shows up in ad pricing, engagement, and new revenue lines. On that basis, the stock looks undervalued for what it is building.

Meta Rebounds Sharply After Its Q2 Earnings Miss
Shares are up 3.36% today, 2.02% over the past week, 13.72% over the past month, and 12.81% year to date. Meta trades 4.7% below its 52-week peak of $779.82 and 43% over its low of $519.37. CNBC also reported that President Trump bought Meta shares in August (CNBC).
In Q2, revenue rose 27.96% to $60.80B, beating the $60.29B consensus. Diluted EPS of $6.18 missed the $7.22 estimate. Higher expenses caused the miss.

Bulls See a Path to $1,040
AI is already lifting the ad business. Ad impressions rose 14% and average price per ad went up 12%. Advantage+ has passed a $75 billion annual revenue run rate. Meanwhile, more than 1 million businesses use Meta’s business agents every week.
On the earnings call, Mark Zuckerberg said Meta receives computing power offers “at a meaningful premium over what we paid”. If enterprise AI scales, our bull case of $1,040.03 means 40% upside.

Free Cash Flow Is Where the Pressure Shows
Q2 free cash flow fell to $784M from $8.55B a year earlier. Operating margin contracted to 31% from 43%. Reality Labs lost $19.2B in 2025, and youth-related lawsuits are heading to trial.
Part of the margin decline came from one-time items: $2.40B in legal charges and $1.18B in severance. Without those, operating income would have grown 9%. Even the bear case of $774.02 stands 4.2% above today’s price.
How Meta Compares to Alphabet and Pinterest
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Meta | 22x | 28% |
| Alphabet | 23x | 24.2% |
| 8x | 18.2% |
The closest match is Alphabet (NASDAQ:GOOGL), since it also funds AI infrastructure with advertising profits. It trades at a slightly higher forward multiple than Meta while growing revenue more slowly. That makes Meta’s discount hard to justify.
Pinterest (NYSE:PINS) gives a pure social-ad comparison. It trades at a much lower multiple, but its TTM operating margin is -3.46%, compared with Meta’s 34.8%. Against these peers, the 24/7 Wall St. price target looks reasonable, and arguably conservative.
Ad Pricing Power Supports Our Buy Rating
The 24/7 Wall St. price target of $905.42 carries a buy rating with 90% confidence. What tips the scale for me is ad pricing power: Meta keeps raising prices even while spending heavily.
The thesis holds if ad growth stays above 20% and the 2026 operating income guidance holds. The thesis weakens if free cash flow keeps contracting into 2027 without new enterprise revenue to offset it. For now, I think the AI return is already visible in the numbers.
This is the level our model projects for Meta if current trends continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $762.53 |
| 2027 | $906.73 |
| 2028 | $1,062.29 |
| 2029 | $1,195.72 |
| 2030 | $1,292.50 |
The projections rest on Meta continuing to execute on its current strategy. Enterprise AI monetization could push results above this path, while litigation losses or a sustained capex overhang could pull them below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.