Tesla Stock Has a Huge Valuation. Here’s What It Would Take to Justify It
Tesla trades at multiples that make traditional automakers look like bargain bins, and whether that premium survives depends on a set of bets that have never been more consequential or more uncertain.

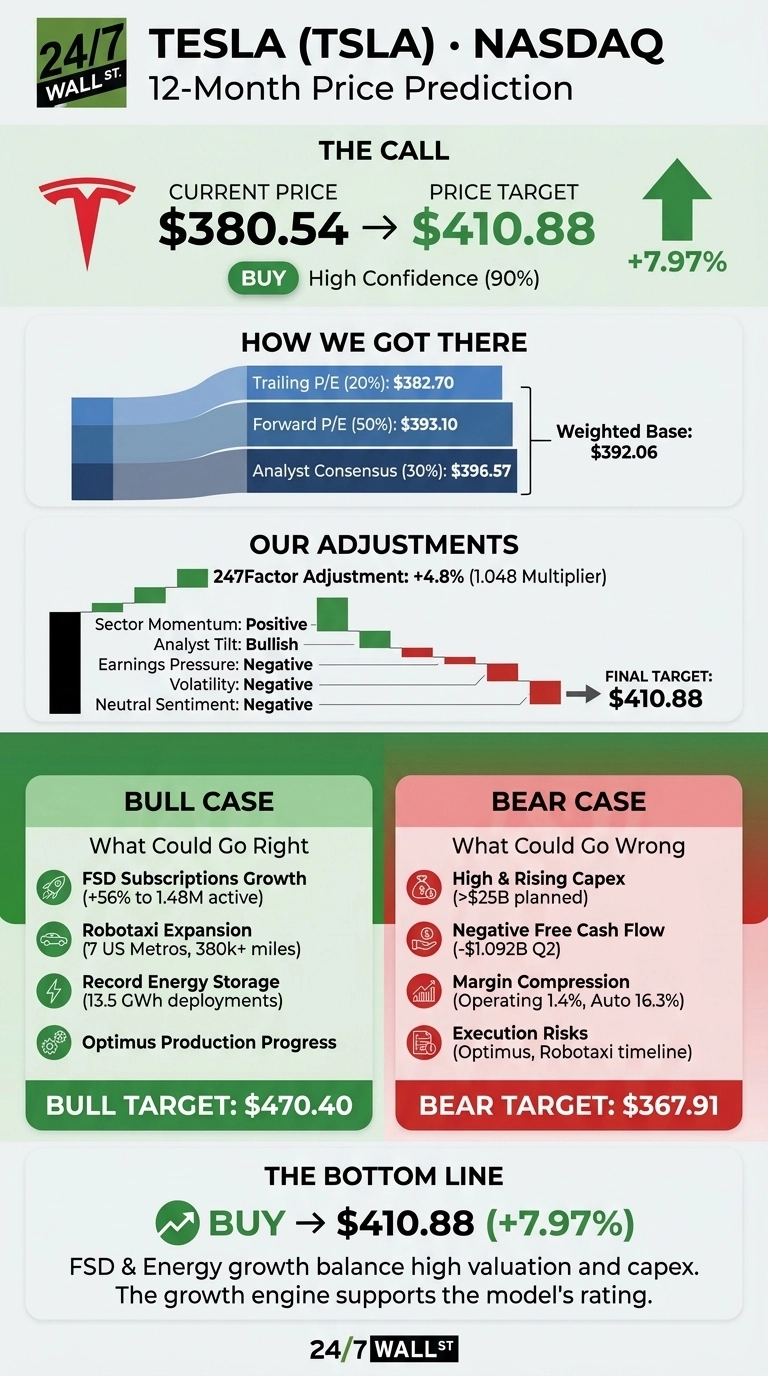
The 24/7 Wall St. price target for Tesla (NASDAQ:TSLA | TSLA Price Prediction) is $410.88 over the next 12 months. With shares at $380.54 in Monday morning trading, that means 7.97% upside. Our model rates Tesla a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $380.54 |
| Price Target from 24/7 Wall St. | $410.88 |
| Upside/Downside | 7.97% |
| Recommendation | BUY |
| Confidence Level | 90% |

Tesla trades at 354x trailing earnings and 159x forward earnings. Justifying that multiple requires autonomy, energy, and robotics to generate profits far larger than the car business produces today. Our model finds the market already prices in much of that future, leaving small but real upside.
Revenue Is Accelerating While an AI Build Absorbs Margins
Shares rose 2.68% over the past week and 3.46% over the past month, but remain down 15.38% year to date. The stock sits between a 52-week low of $297.38 and a high of $498.83. On Friday, Tesla rose as Elon Musk asserted control over the Terafab chip project.
Second-quarter revenue reached $28.24 billion, up 25.5% and exceeding the $26.36 billion consensus, on record Q2 deliveries of 480,126 vehicles. EPS came in at $0.33, while operating margin contracted to 1.4% as operating expenses rose 47% to $4.35 billion. Free cash flow came in at negative $1.092 billion.
What Bulls Need to See for $470
Software is the core of the bull case. Active Full Self-Driving (FSD) subscriptions hit 1.48 million, up 56%. Robotaxi now operates in 7 US metros and has logged more than 380,000 miles of unsupervised driving with zero notable incidents.
Energy storage deployments reached 13.5 GWh. Musk told analysts, “I think Optimus will be the biggest product ever.” Among analysts, 4 rate Tesla a strong buy and 15 a buy. If those businesses scale on schedule, our bull case reaches $470.40.

Cash Burn and a Hold-Heavy Street Cloud the Story
Management expects 2026 capex of more than $25 billion and plans to keep raising it for the next two or three years. Automotive margin excluding credits fell to 16.3% from 19.2%.
The drop reflects a tough comparison: Q1 included a $230 million one-time benefit, and without it margins were about flat. Energy margins also fell after a $240 million warranty true-up tied to legacy installations.
Prediction market traders give Optimus just a 7.3% chance of release by year-end. On the Street, 21 analysts rate the stock a hold, and the consensus target of $396.57 sits close to today’s price. The downside scenario lands at $367.91.

Tesla vs. GM and Ford: Software Explains the Premium
| Company | Forward P/E | Price/Sales (TTM) |
|---|---|---|
| Tesla | 159 | 14.59 |
| General Motors (NYSE:GM) | 6 | 0.391 |
| Ford (NYSE:F) | 7 | 0.258 |
General Motors is the closest US competitor in EVs and autonomy. GM generated $185.5 billion in trailing revenue, far more than Tesla’s $103.6 billion, yet trades at a fraction of Tesla’s valuation. The gap shows that investors price Tesla on its future potential.
Ford offers a value contrast, with a 4.9% dividend yield, while quarterly revenue declined 3.8%. Tesla’s 25.5% revenue growth earns some premium, though measured against the peer group alone, our 24/7 Wall St. price target looks fully valued.
Cash Flow Will Decide Whether Tesla Earns Its Premium
The 24/7 Wall St. price target of $410.88 supports a buy at 90% confidence. FSD subscription growth is what tips the scale.
The bull case strengthens if Robotaxi keeps expanding and free cash flow turns positive again in 2027. The outlook weakens if capex keeps climbing without any recovery in margins. For now, the growth engine supports the model’s rating.
Tesla Price Prediction 2026-2030
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $382.60 |
| 2027 | $430.06 |
| 2028 | $436.08 |
| 2029 | $473.40 |
| 2030 | $502.05 |
Tesla would need to keep executing on its current strategy for these projections to hold. Large moves in either direction could come from Optimus production timing or a possible SpaceX merger, which traders price at 59.5% probability of being announced by the end of 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.