Applied Digital Sinks 4% as Rotation Out of Debt-Funded AI Builders Extends; TeraWulf Dips 3%, Core Scientific Retreats 2%
JPMorgan just downgraded Applied Digital's bonds and the stock is sliding, yet management is already lining up its next round of borrowing to fund three more data centers. Find out whether the bull case on $36 billion in contracted revenue…

Investors are souring on leveraged AI data center developers again. Applied Digital (NASDAQ:APLD) stock has fallen 4%, recently trading around $19.59, extending a rotation out of highly valued, debt-heavy AI infrastructure stocks.
Meanwhile, TeraWulf (NASDAQ:WULF) stock is down 3% to $12.28. At the same time, Core Scientific (NASDAQ:CORZ) stock is down 2% to $14.21.
The Global X Data Center & Digital Infrastructure ETF (NASDAQ:DTCR) is down 0.6%. Its May 31 holdings report listed Applied Digital at 4.5% of net assets. The SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is up 0.3%, leaving the selling concentrated in leveraged builders.
JPMorgan Bond Cut Sharpens Supply Worries
Debt is driving the selling. This week, JPMorgan analysts cut Applied Digital’s project finance bonds to Neutral from Overweight, citing a looming supply overhang as the company prepares to borrow more to fund its construction pipeline. Data center developer bonds also fell as investors questioned the debt loads behind AI buildouts (we featured seven suppliers riding the same expansions, from power to cooling, in a free report here).
Applied Digital builds AI data centers and leases them to hyperscalers under long-term contracts, raising project debt before the rent arrives. It carried $6.4 billion of debt against $3.7 billion in cash and restricted cash at the end of Q1 FY2027. Its latest raise was $1.59 billion of 7% senior secured notes to fund a third HPC building at Polaris Forge 1 in North Dakota.
Management at Applied Digital has pushed back. Chief Financial Officer Saidal Mohmand stated on the October 7 earnings call, “Our goal remains to maintain one of the strongest balance sheets in the industry through the majority of the construction phase and we’ll execute as such.” He also said, “We don’t underwrite leases where 100 basis point move would impact our economics really.”
Blowout Quarter Offers Little Cover
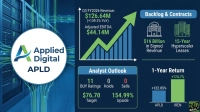
Applied Digital’s operating results have rarely looked stronger. Its Q1 revenue was $341.9 million, up 432.4% year over year and far above the $124.6 million analysts expected.
Earnings also surprised. The adjusted loss of $0.01 per share beat the expected loss of $0.3023.
Within the quarter, Applied Digital’s HPC Hosting segment generated $262.6 million of that revenue. The company’s adjusted EBITDA (earnings before interest, taxes, depreciation and amortization) jumped to $64.4 million from $0.5 million a year earlier.
When the company filed those results on October 7, Applied Digital stock was at $25.45. That filing also showed a net loss of $184 million under standard accounting rules, driven by non-cash fair value losses, heavy stock-based compensation and rising interest expense.
Long Leases Meet a Growing Debt Stack
Applied Digital’s bull case rests on long-term hyperscaler leases: 1.41 gigawatts of leased critical IT load, representing $36 billion of contracted revenue over initial terms, or $86 billion with renewals. Polaris Forge 2 in Harwood could lift North Dakota capacity to 300 megawatts by year-end.
The skeptics could point out that each new round of project debt adds to the burden JPMorgan described. CEO Wes Cummins argues Applied Digital’s powered campuses gain value as other markets tighten: “Put simply, we view every new restriction elsewhere as making what we already own harder to replicate.” Yet, the construction pipeline still runs on fresh borrowing.
Pricing the Next Debt Raise
Applied Digital’s next test is whether the coming debt raise prices without pushing borrowing costs higher. Management plans to finance Polaris Forge 3, Delta Forge 1 and Delta Forge 2 next, all tied to one tier-one hyperscaler under 15-year take-or-pay contracts, and has expressed “a high level of confidence” in funding them at favorable rates.
A clean deal could ease the burden and shift focus back to the committed backlog. Until then, Applied Digital’s debt load argues for investors keeping their positions modest.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.