The Next AI Stock Wall Street Is Starting to Pay Attention To
Arm Holdings has surged over 120% this year while building a chip empire that stretches from smartphones into AI data centers, but a brutal recent selloff and a valuation that makes even NVIDIA look cheap raise a pointed question about…

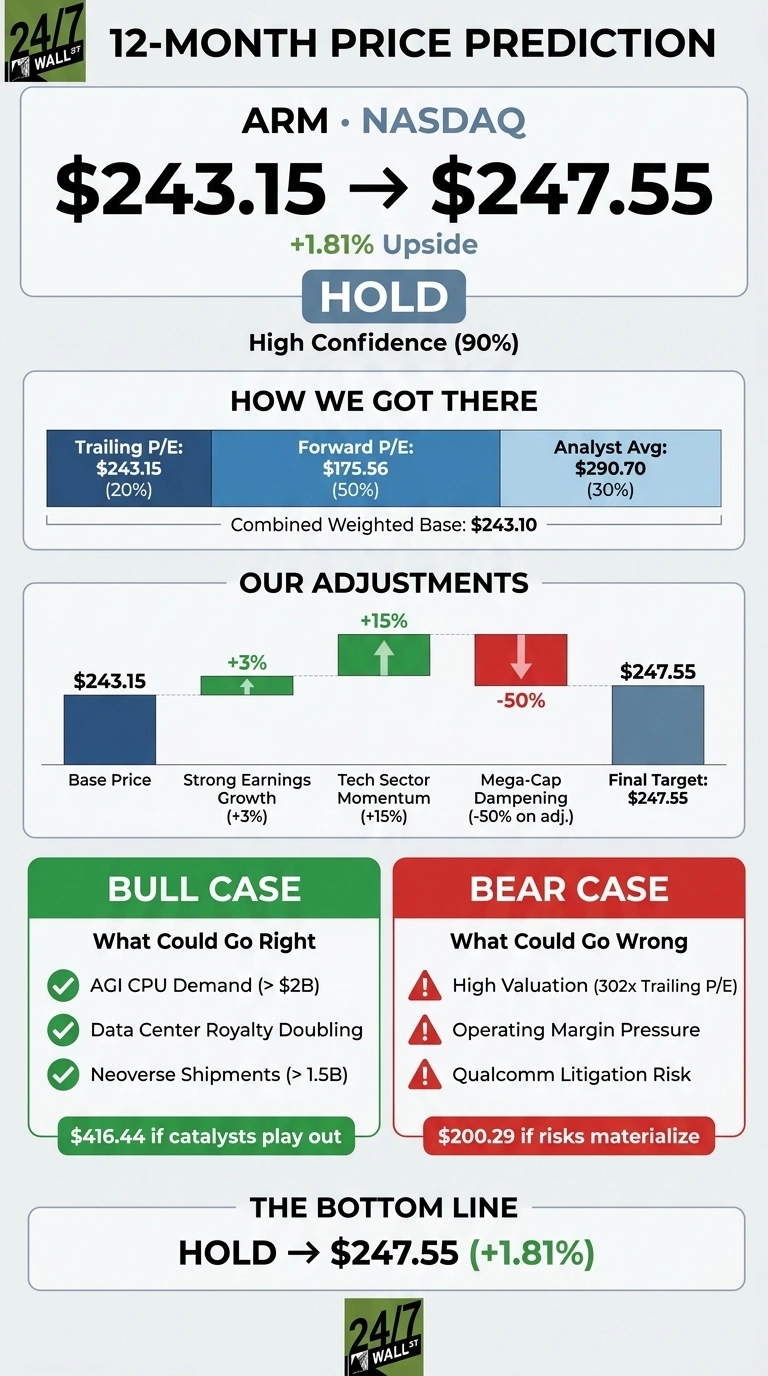
Arm Holdings (NASDAQ:ARM | ARM Price Prediction) trades at $243.15 today. The 24/7 Wall St. price target for Arm is $247.55 over the next 12 months, which means 1.81% upside. Our rating is hold, and our confidence in the model is high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $243.15 |
| Price Target from 24/7 Wall St. | $247.55 |
| Upside/Downside | 1.81% |
| Recommendation | HOLD |
| Confidence Level | 90% |

Arm started out licensing chip designs for smartphones. Today it is building its own AI data center silicon, and Wall Street has taken notice.
The stock carries 8 Strong Buy and 21 Buy ratings. At the end of June, Alphabet (NASDAQ:GOOGL) held $695 million of Arm stock, and Maverick Capital opened a new position. I think the story is real, but much of it is already in the price.
A Brutal Week Takes Some Shine Off a Huge Year
Arm has dropped 19.64% over the past week and 8.17% over the past month. Even so, it is still up 122.44% year to date. Shares sit about 46% below the 52-week high of $452.70 and about 143% above the low of $100.02.
Arm’s fiscal Q1 2027 revenue came in at $1.289 billion, up 22.4% and ahead of the $1.267 billion consensus. GAAP EPS of $0.25 missed expectations. Non-GAAP EPS of 45 cents topped the high end of guidance. Management also said demand for its Arm AGI CPU “now exceeds $2 billion.”
Why Bulls See $416 Ahead
Arm’s data center royalties more than doubled year over year once again, and Neoverse shipments have passed 1.5 billion cores. Vera from NVIDIA (NASDAQ:NVDA), Google’s Axion, Microsoft’s Cobalt and AWS’s Graviton all run on Arm designs.
Management has seen outside estimates for the CPU market rise from $100 billion to as much as $220 billion (we studied what the earliest signs of the last mega-winner in chips looked like and put the pattern in a free playbook here). The consensus target of $290.70 stands well above our number. If everything goes right, Arm reaches $416.44.

Valuation and Margin Pressure Are the Risks Worth Watching
Arm trades at about 302x trailing earnings. GAAP operating margin fell to 7% from 11% as operating expenses rise 28%, and EPS has missed estimates in four of the last five quarters.
Other risks include the Qualcomm (NASDAQ:QCOM) trial expected in Q4 2026, Arm’s reliance on Arm China and smartphone royalty growth that is heading toward the “high teens.”
Bulls have a reasonable reply. Non-GAAP operating margin rose to about 41%, which shows the GAAP pressure mostly reflects stock-based pay and spending on future growth. In our bear case, the stock falls to $200.29.

How Arm Compares to NVIDIA and AMD
NVIDIA belongs in this comparison because its Vera CPU runs on Arm designs, so the two depend on the same AI buildout. The stock trades at about 46x earnings, and Q2 revenue rose 105.85%. That much faster growth at a far lower multiple makes Arm’s valuation look stretched.
AMD (NASDAQ:AMD) competes with Arm-based chips through its x86 EPYC server processors. Its P/E of about 228x shows the market will pay a premium for AI CPU exposure, although AMD’s gross margin is much lower than Arm’s.
| Company | Trailing P/E | Gross Margin |
|---|---|---|
| Arm | 302x | 92.5% |
| NVIDIA | 46x | 71.1% |
| AMD | 228x | 49.5% |
Taken together, these peers make the 24/7 Wall St. price target look reasonable. Arm’s margins justify a premium, but there is little room for the multiple to expand from here.
Valuation Caps Arm’s Upside for Now
The hold rating rests on a 24/7 Wall St. price target of $247.55, with 90% confidence. Valuation is what tips the scale.
I’d turn more constructive if AGI CPU revenue grows on schedule and GAAP earnings start beating estimates. I’d stay cautious if the Qualcomm case goes against Arm or margins keep fell. For now, the price fairly reflects a great business.
Here is where our model projects Arm could trade if current growth and market conditions hold over the longer term.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $259.56 |
| 2027 | $230.35 |
| 2028 | $243.69 |
| 2029 | $247.42 |
| 2030 | $291.93 |
These projections assume Arm keeps executing on the plan in place. Big deals in the AGI CPU business could push the stock well above these levels, while a loss in the Qualcomm case could brings it below them.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.