Prediction: One Major Catalyst Could Send Alphabet Stock to New Highs
Google Cloud's revenue growth keeps accelerating at a scale that has rivals scrambling, and one forward-looking metric buried in Alphabet's latest earnings report suggests the stock has barely started its move.

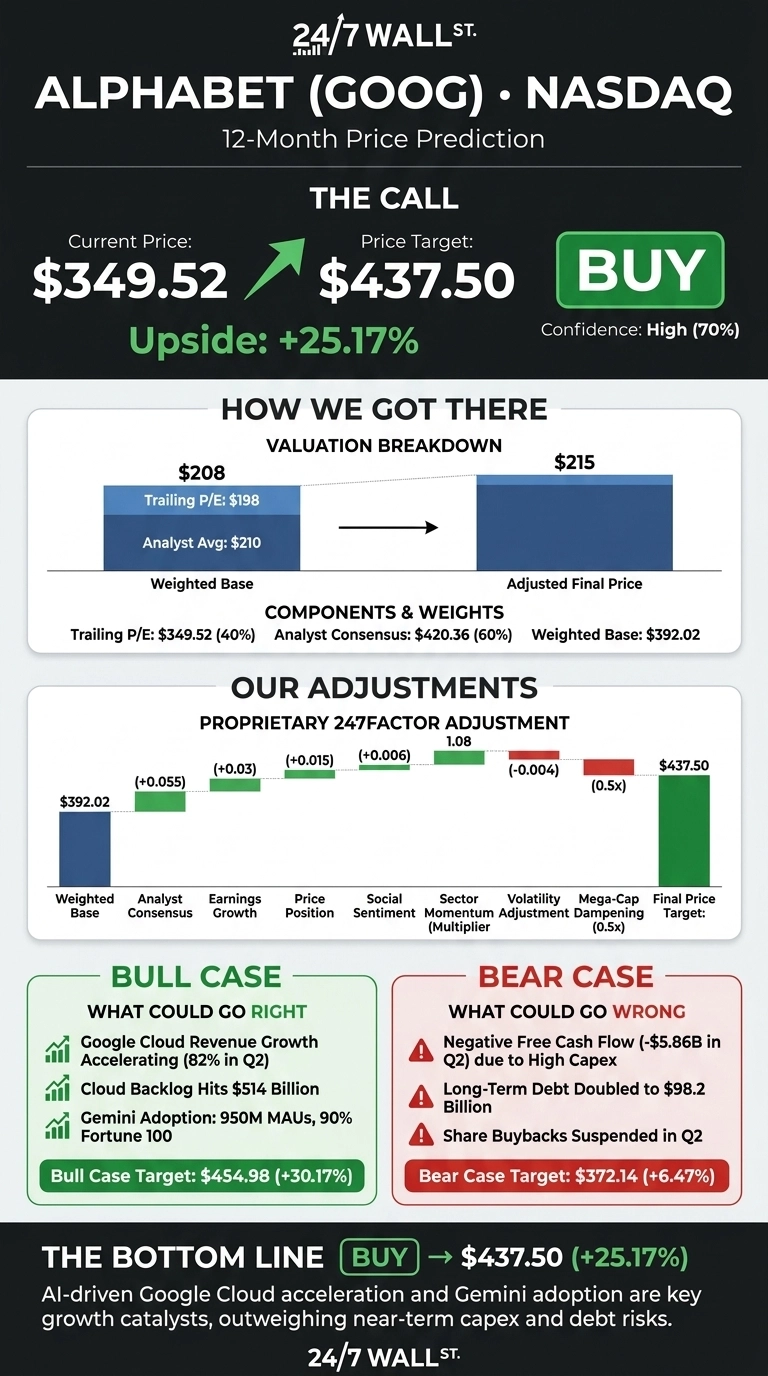
Alphabet (NASDAQ:GOOG | GOOG Price Prediction) trades at $349.52. The projected 24/7 Wall St. price target is $437.50, meaning 25.17% upside over the next 12 months. Our rating is buy with fairly high confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $349.52 |
| Price Target from 24/7 Wall St. | $437.50 |
| Upside/Downside | 25.17% |
| Recommendation | BUY |
| Confidence Level | 70% |
Google Cloud is the catalyst. Its revenue grew 82% in Q2, up from 63% in Q1 and 48% in Q4 2025. Backlog hit $514 billion. Our target stands above the 52-week high of $403.96, so reaching it would mean new highs.

Cloud Acceleration Keeps Alphabet Within Reach of Its High
GOOG has gained 1.52% over the past week, 4.28% over the past month, 11.7% year to date and 43.37% over the past year. Shares sit about 13.5% below the 52-week high and around 43.2% above the low of $244.03.
In the Q2 report, revenue of $119.80 billion beat the $116.91 billion estimate and rose 24.23%. EPS of $9.11 exceeded the $3.0427 estimate, although a $99.03 billion gain on equity securities inflated that figure. The cleaner signal was operating income, which rose 30.38% to $40.77 billion, while Search grew 17%.
Why Bulls See $455 and Beyond
The bull case rests on Cloud’s profitability. Cloud operating margin rose to 35.6% from 20.7% a year earlier. Management expects just over 50% of the backlog to become revenue within 24 months. Gemini reached 950 million monthly users, nearly 90% of the Fortune 100 use Gemini Enterprise, and Gemini 4 is in pre-training.
Most TPU system sales revenue is expected in 2027. Analysts rate the stock 13 Strong Buy, 44 Buy and 5 Hold, with no Sell ratings. Our bull case is $454.98.

Negative Free Cash Flow Is the Cost of the Buildout
Capex doubled to $44.92 billion, which drove free cash flow to -$5.855 billion. Long-term debt rose from $46.5B to $98.2B, a $49.6 billion equity raise diluted holders, and buybacks were suspended.
Higher-cost third-party capacity may also pressure Cloud margins in Q3. Bulls would answer that operating cash flow grew 40.8%, and the backlog shows demand is already signed. Our bear case of $372.14 is still above today’s price.
Alphabet Trades at a Discount to Microsoft and Meta
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Alphabet | 15 | 24.23% |
| Microsoft | 30 | 17.75% |
| Meta | 28 | 27.96% |
Microsoft (NASDAQ:MSFT) belongs here because Azure is Google Cloud’s closest rival. Azure grew 43%, about half the pace of Google Cloud, yet Microsoft trades at around twice Alphabet’s trailing multiple. Microsoft’s operating margin of 46.8% helps explain that premium.
The closest match on ads and capex is Meta Platforms (NASDAQ:META). Its Q2 EPS of $6.18 missed the $7.2214 estimate, and operating margin fell to 31%. Alphabet’s trailing P/E is depressed by equity gains, but even its forward P/E of 22 stands below both peers’ trailing multiples. That makes our target look conservative.
Cloud Momentum Drives Our $437.50 Target
The 24/7 Wall St. price target is $437.50, with a buy rating and 70% confidence. The main factor is Cloud growth that keeps speeding up at scale.
The Q3 report will show whether the backlog is converting to revenue and Cloud margins are holding up. The key risk is capex that keeps rising while Cloud growth slows down. For now, the data supports the bulls.
Over a longer horizon, here is where our model projects Alphabet could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $437.50 |
| 2027 | $487.93 |
| 2028 | $544.17 |
| 2029 | $606.90 |
| 2030 | $676.85 |
These projections assume Alphabet keeps executing on its full-stack AI strategy. Results could swing significantly in either direction depending on how Gemini 4 is received and whether AI capex realizes an adequate return.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.