Prediction: This Magnificent Seven Stock Could Be a $1 Trillion Opportunity
Alphabet shares sit roughly 21% below their 52-week high even as Google Cloud posts explosive growth and its backlog swells to half a trillion dollars. Whether that gap represents a rare buying window or a value trap depends on one…

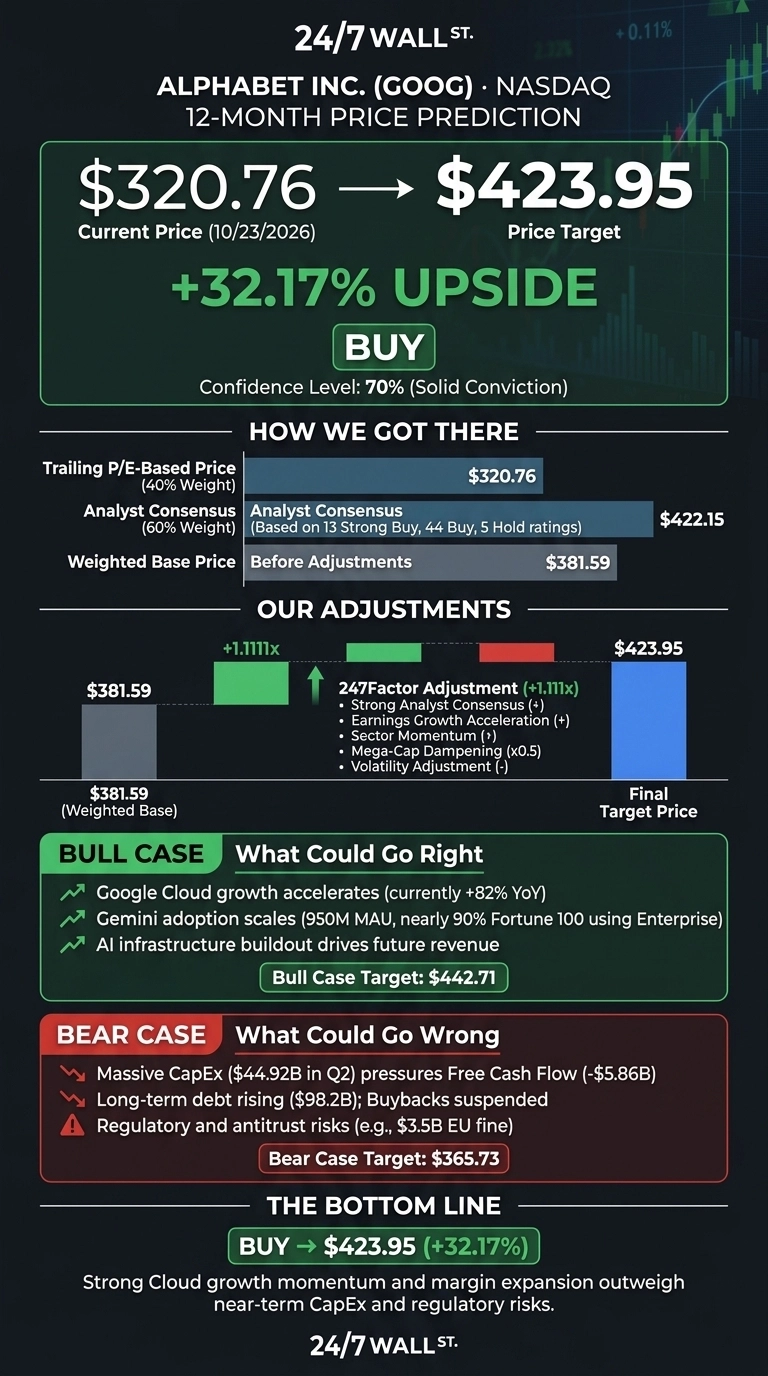
The 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG | GOOG Price Prediction) is $423.95. That means 32.17% upside from the prior close of $320.76. The stock gets a buy rating with 70% confidence, which we read as solid conviction with a margin for error.
| Metric | Value |
|---|---|
| Current Price | $320.76 |
| Price Target from 24/7 Wall St. | $423.95 |
| Upside/Downside | 32.17% |
| Recommendation | BUY |
| Confidence Level | 70% |
Applied to Alphabet’s $4.05 trillion market cap, that upside works out to about $1.3 trillion in added market value. That figure is the opportunity behind our headline.

Google Stock Pulls Back Even as Cloud Growth Accelerates
Shares fell 7.82% over the past week and 8.49% over the past month. Early Friday they traded at $317.93, up just 1.51% year to date and about 21% below the 52-week high of $403.96. Over the past year the stock is still up 26.23%.
The fundamentals point the other way. In Q2, revenue rose 24.2% to $119.80 billion, ahead of the $116.91 billion estimate. EPS came in at $9.11 against a $3.04 estimate, although a $99.03 billion equity securities gain inflated that number. Google Cloud grew 82%, and its backlog reached $514 billion.
Why Bulls See a Breakout to $442
Cloud is now a profit engine. Its operating margin expanded to 35.6% from 20.7% a year earlier. The Gemini app has 950 million monthly users, and nearly 90% of the Fortune 100 use Gemini Enterprise.
Waymo has passed 500,000 fully autonomous rides a week. On the Q2 call, CEO Sundar Pichai said, “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.”
Wall Street largely agrees: 13 analysts rate the stock Strong Buy, 44 rate it Buy, 5 rate it Hold and none rate it Sell. The bull case reaches $442.71.

Spending Risks That Could Cap the Upside
Q2 capex jumped 100.14% to $44.92 billion, and free cash flow fell to -$5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion. Buybacks are suspended, and a new at-the-market program of up to $40 billion could dilute shareholders. Regulators also remain a threat after the $3.5 billion EU fine.
The counterpoint is that this cash is going into capacity customers are waiting for. Management says Alphabet remains supply constrained. Operating cash flow still rose 40.8%, and interest coverage stands at 175.5x.
Even our bear case of $365.73 sits above today’s price. The same AI expansion driving that capex is pulling a long list of suppliers along with it (we highlighted seven of them, from power to cooling, in a free report you can grab here).
Alphabet Looks Cheaper Than Microsoft and Meta
The most direct cloud rival is Microsoft (NASDAQ:MSFT). Azure grew 43%, about half of Google Cloud’s rate, yet Microsoft trades at 29x earnings.
Meta Platforms (NASDAQ:META) competes with Alphabet for ad budgets and AI talent. Its Q3 operating margin fell to 20%, partly because of a $9.89 billion legal charge.
| Company | P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Alphabet | 13x | 24.2% |
| Microsoft | 29x | 17.75% |
| Meta | 24x | 26.07% |
Alphabet’s multiple gets a lift from equity gains. Even its forward P/E of 22x is still below Microsoft’s trailing multiple. Next to these peers, our target looks reasonable, maybe even conservative.
Cloud Momentum Tips the Scale
The 24/7 Wall St. price target of $423.95 carries a buy rating with 70% confidence. The deciding factor is cloud growth that is speeding up as margins expand.
I’d view the stock as attractive if the backlog keeps turning into revenue at these margins. I’d grow more cautious if free cash flow stays negative while debt keeps rising. On balance, Alphabet looks undervalued.

| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month target) | $423.95 |
| 2027 | $426.05 |
| 2028 | $510.24 |
| 2029 | $597.01 |
| 2030 | $659.84 |
Alphabet needs to keep executing on its full-stack AI strategy for these projections to hold. Gemini adoption, regulatory action or a slowdown in AI spending could move the stock well above or below these targets.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.