Forget Realty Income: These 4 High-Yield REITs Are Better Buys Today
Realty Income dominates net-lease portfolios by default, but four rivals offer higher yields, faster payout growth, and tenant rosters built around casinos, experiential venues, and inflation-linked leases that O simply cannot match.

Realty Income (NYSE:O) is the default net-lease holding in many retirement portfolios. Owning only one landlord, though, links your income to a single tenant roster, a single cost of capital, and a single growth rate. Four other NYSE-listed triple-net REITs spread that income across casinos, global industrial sites, freestanding retail and entertainment venues. Each one covers its payout with adjusted funds from operations (AFFO, the cash earnings measure REITs use to fund dividends), and each has raised its distribution this year. A pullback over the past month has lifted the group’s top forward yield to 8.0%.
VICI Properties: An 8% Yield Backed by Casino Leases
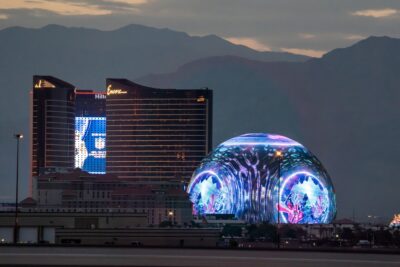
VICI Properties (NYSE:VICI) owns gaming, hospitality, and entertainment destinations, including Caesars Palace. The annualized forward dividend is $1.84 per share, and the stock trades at $22.88, which works out to a forward yield of about 8.0%. That places VICI well into ultra-high-yield territory.
Dividend safety: The board raised the quarterly payout to $0.46 from $0.45. Management raised its full-year AFFO guidance to $2.45-$2.47 per diluted share, so the forward dividend uses about 75% of the midpoint. Second-quarter AFFO came in at $0.62 per share, up 4.6% year over year. Occupancy is 100%, the weighted average lease term is 39.6 years, and most leases include 2.0% annual escalators. Total debt is about $17.2 billion, against $29.6 billion of shareholders’ equity. The quarterly distribution has climbed from $0.2875 in 2019 to today’s level, with a higher payout each year. The second-quarter GAAP miss ($0.48 vs. a $0.71 estimate) came from a $271.1 million non-cash CECL charge, which is an accounting item and did not reduce rent collected.
Bull case: The valuation has contracted. The stock is down 14.31% year to date, sits close to its 52-week low of $22.43, and trades at 0.895 times book value on a trailing P/E of 9. The tenant roster also grew to 16 after the additions of Clairvest, Golden Entertainment, and Club Med. The chief executive said the “partner-driven model will continue to generate attractive, durable growth.”
Risk: Rent is concentrated in two tenants. Caesars supplies about 38% of rent and MGM about 32%.
W.P. Carey: Quarterly Raises With CPI-Linked Rent
W.P. Carey (NYSE:WPC) pays an annualized forward distribution of $3.80. With shares at $63.36, the forward yield is about 6.0%, which lands just below the ultra-high-yield threshold.
Dividend safety: Management places the payout ratio at just over 70% of AFFO. Full-year AFFO guidance was raised to $5.19 to $5.27 per diluted share, and second-quarter AFFO of $1.34 beat the $1.24 consensus. Net debt is 5.5x adjusted EBITDA, or 5.1x including unsettled forward equity. About 95% of debt is fixed-rate at a 3.2% weighted average. Liquidity is about $2.7 billion, with no debt left to refinance this year. Track record: W.P. Carey cut its quarterly payout from $1.071 to $0.86 in late 2023 when it exited office properties. Since then, it has raised the payout every quarter, most recently to $0.95.
Bull case: More than 99% of base rent has contractual increases built in, and 47.8% is tied to CPI. That gives income investors some protection against inflation. Occupancy is 98.5%, and full-year investment guidance went up to $1.7 to $2.1 billion. The chief executive said the company is “raising our expectations for both full-year investment volume and AFFO per share.”
Risk: European same-store rental income fell 2.6% in constant currency, which exposes the payout to currency swings and weaker overseas markets.
NNN REIT: 37 Straight Years of Raises at a 6.2% Yield
NNN REIT (NYSE:NNN) owns freestanding single-tenant retail properties. Its forward dividend is $2.48 per share, and at $40.23 that is a forward yield of about 6.2%. It joins this list as a high-yield name with the longest dividend record of the four.
Dividend safety: The quarterly payout rose 3.3% to $0.62. That marked the company’s 37th consecutive year of annual dividend increases, a record management says just three REITs share. Management places the new rate at a 69% AFFO payout ratio. Free cash flow left after paying the dividend was about $56 million in the second quarter. AFFO guidance went up for the second time this year, to $3.55 to $3.59. Only 2.5% of debt is floating-rate, the weighted average debt maturity is 10.1 years, and liquidity stands at $1.4 billion.
Bull case: Occupancy reached 99.1%, up 110 bps year over year. Second-quarter acquisitions totaled $291.0 million at a 7.3% initial cash cap rate, with a 17.9-year lease term, so new money is going into long-dated rent flows. The shares fell 8.81% over the past month and trade below their 200-day average of $44.21. As the chief financial officer put it, “Our portfolio is in great shape.”
Risk: Borrowing costs are rising. Quarterly interest expense rose to $53.5 million from $49.3 million. A $350 million maturity due this year may be refinanced at an estimated mid-5 to 5.6% for ten-year debt.
EPR Properties: Monthly Income at a 6.8% Yield
Shares of EPR Properties (NYSE:EPR) pay $0.31 per share every month, or $3.72 a year. At $54.76, the forward yield is about 6.8%. It ranks as the only monthly payer in the group and an ultra-high-yield one.
Dividend safety: Full-year FFOAA guidance (EPR’s adjusted FFO measure) was raised to $5.41 to $5.57 per diluted share, so the dividend uses about 68% of the midpoint. Second-quarter AFFO rose to $1.43 per share, up 15.3% year over year. Tenant rent coverage across the portfolio is 2.0x, and properties are 99% leased or operated. Net debt is 5.3x Adjusted EBITDAre, interest coverage is 4.0x, and a new $1.6 billion credit agreement supports a $450 million maturity due later this year. Track record: EPR suspended its dividend during the pandemic. It resumed payments at $0.25 per month in 2021 and has raised them in steps to $0.31. That is still below the pre-pandemic $0.3825.
Bull case: EPR committed $440.8 million in the second quarter at about an 8.5% initial cash yield. That included the $304.4 million Six Flags acquisition. Netflix also became a tenant, and theater ticket sales are running about 10% above the prior year. The chief executive said the company is “increasing our 2026 earnings and investment spending guidance.”
Risk: Topgolf and AMC each produced about 13.1% of second-quarter revenue, and the top ten customers produced 63.7%.
Four Ways to Diversify Net-Lease Income
Each of these four REITs funds its payout from rising AFFO, holds occupancy at or above 98.5%, and has raised its distribution this year. NNN has the longest record of increases, VICI the highest yield, W.P. Carey the strongest inflation protection, and EPR pays monthly. Together, they spread net-lease income across four different tenant bases. The next earnings reports will show whether guidance continues to rise alongside the dividends.
Contact [email protected] for any questions or corrections.
Lee Jackson has covered Wall Street analysts' equity and debt research and equity strategy daily for 24/7 Wall St. since 2012. His broad, diverse career, including a stint as creative services director at an NBC affiliate in Austin, Texas, gives him unique insight into the financial industry.
Lee Jackson's journey in the financial industry spans more than 30 years, including nearly two decades as an institutional equity salesperson at Bear Stearns, Lehman Brothers, and Morgan Stanley. His career spanned pivotal sell-side Wall Street events, from the dot-com rise and bubble to the Long-Term Capital Management debacle, 9/11, and the Great Recession of 2008. This reflects his resilience and adaptability amid market volatility.
Lee Jackson’s practical financial industry experience, gained through a career at some of the biggest banks and brokerage firms, is complemented by a lifetime of writing across various platforms. This unique combination allows him to shed light on the intricacies of Wall Street in a way only someone with deep insider experience and knowledge can. Moreover, his extensive network across Wall Street continues to provide direct access for him and 24/7 Wall St., a privilege few firms enjoy.
Since 2012, Jackson’s work for 24/7 Wall St. has been featured in Barron’s, Yahoo Finance, MarketWatch, Business Insider, TradingView, Real Money, The Street, Seeking Alpha, Benzinga, and other media outlets. He attended the prestigious Cranbrook Schools in Bloomfield Hills, Michigan, and has a degree in broadcasting from the Specs Howard School of Media Arts.