Amazon Stock Could Climb Higher as AWS Becomes an Even Bigger Growth Engine
AWS just posted its fastest growth rate in 18 quarters, but a $200 billion capital spending plan and deeply negative free cash flow are raising serious questions about whether Amazon can actually afford its own ambitions.

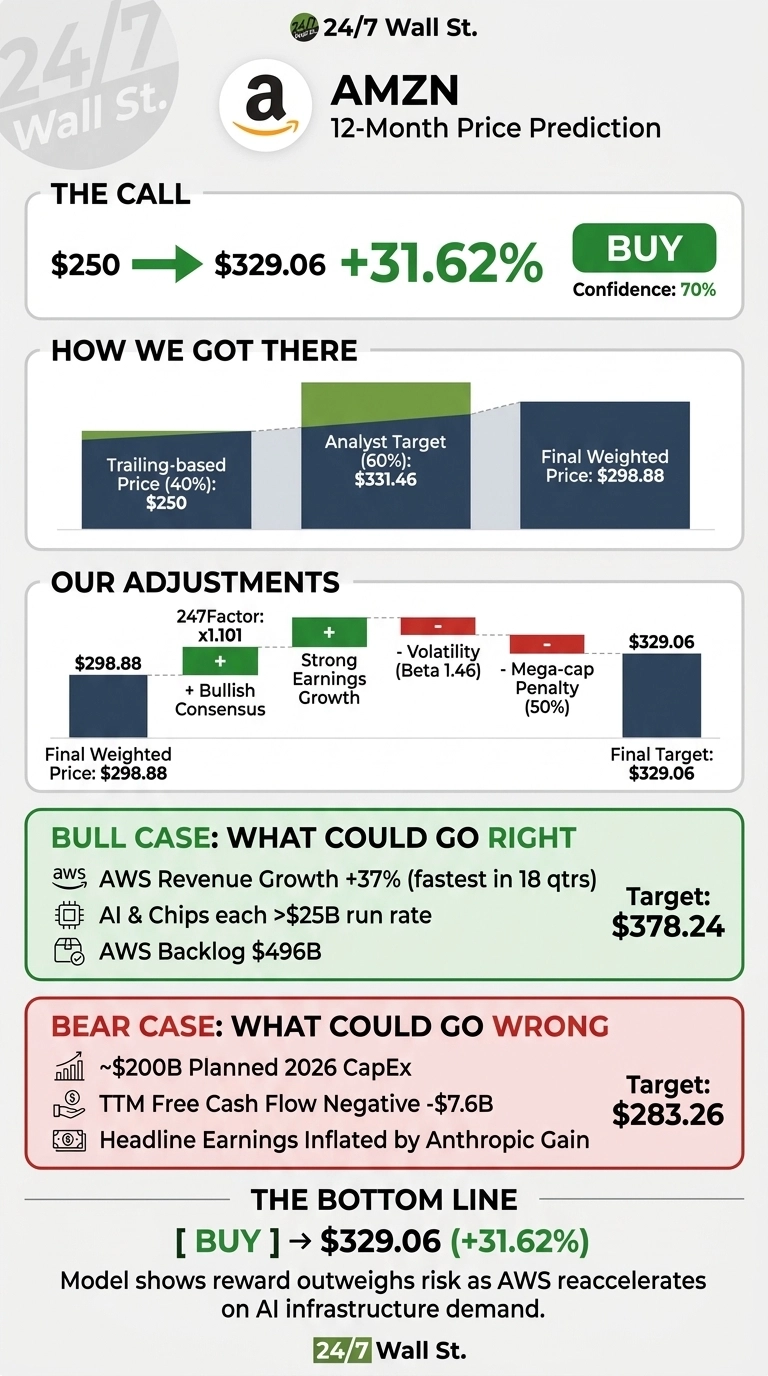
The 24/7 Wall St. price target for Amazon (NASDAQ:AMZN | AMZN Price Prediction) is $329.06. That is 31.62% above the $250 close on October 16. The stock gets a buy rating from our model with fairly high confidence.
| Metric | Value |
|---|---|
| Current Price | $250 |
| Price Target from 24/7 Wall St. | $329.06 |
| Upside/Downside | 31.62% |
| Recommendation | BUY |
| Confidence Level | 70% |

My case rests on AWS. Revenue there grew 37% last quarter, the fastest rate in 18 quarters, and the backlog reached $496 billion. AWS is quickly becoming the main driver of Amazon’s valuation.
AWS Acceleration Collides With a Choppy October
Shares fell 4.74% over the past week and rose 1.64% over the past month. They are about flat over three months, up 0.04%, and up 8.31% year to date. The stock sits 12.95% below its 52-week peak of $287.20 and trades 27.55% above its low of $196.
Second-quarter revenue rose 19.6% to $200.61 billion, beating estimates by 2.12%. GAAP EPS came in at $5.75, lifted by a $53.4 billion Anthropic gain.
Comparable EPS of about $1.88 beat the $1.83 estimate. For the third quarter, Amazon guided to operating income of $22.5 billion to $26.5 billion, compared with $17.4 billion a year earlier.
Why Bulls See $378 Within Reach
AWS now has a $169 billion annualized run rate. Its AI and chips businesses have each passed $25 billion run rates. OpenAI committed to about 2 GW of Trainium capacity, and Anthropic to up to 5 GW.
CEO Andy Jassy said AWS could “very possibly be a trillion dollar annual revenue business for us in time.” Analysts agree: 16 rate it Strong Buy, 43 give it a Buy and none call it a Sell. Our bull case reaches $378.24.

Cash Burn Risks That Could Derail the AWS Story
Amazon plans about $200 billion of capital spending in 2026, and trailing free cash flow has turned negative at -$7.6 billion. Headline earnings are also inflated by one-time Anthropic gains.
In fairness, management says servers break even in a little less than three years, and most AI capacity is signed to at least five-year terms. Our bear case of $283.26 still sits above today’s price.
How Amazon Stacks Up Against Microsoft and Alphabet
Microsoft (NASDAQ:MSFT) belongs here because Azure is AWS’s closest rival. Last quarter Azure grew 43%, and commercial bookings Microsoft has yet to recognize as revenue reached $678 billion. Even with faster cloud growth, Microsoft trades at a lower P/E than Amazon.
In both cloud and advertising, Alphabet (NASDAQ:GOOGL) competes with Amazon. Google Cloud grew 82%. However, its low P/E is flattered by a $99.03 billion equity gain.
| Company | P/E | Cloud Growth |
|---|---|---|
| Amazon | 35x | 37% |
| Microsoft | 29x | 43% |
| Alphabet | 15x | 82% |
Amazon carries a premium multiple, but that premium buys the largest cloud business plus advertising and retail. Compared with these peers, our target looks reasonable.
AWS Momentum Tips the Scale at $250
The 24/7 Wall St. price target of $329.06 comes with a buy rating at 70% confidence. The deciding factor is AWS reaccelerating on a very large base. Gains pile up if AWS growth remains above 30% and capital spending starts turning into backlog conversion.
Risks grow if free cash flow keeps falling into 2027 without a matching rise in AWS margins. On balance, the model shows more reward than risk at this price.

Looking further ahead, here is where our model projects Amazon could trade, assuming current growth patterns continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $262.59 |
| 2027 | $326.83 |
| 2028 | $386.75 |
| 2029 | $466.71 |
| 2030 | $519.42 |
These projections assume Amazon stays on its current strategic path. Results could beat them if Trainium demand exceeds expectations, or fall short if AI spending stops paying off.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.