PepsiCo Stock Could Be a Contrarian Opportunity if This One Thing Improves
PepsiCo trades nearly 19% below its 52-week high while Wall Street sits overwhelmingly on the sidelines, but one struggling business unit holds the key to whether this Dividend King is a bargain or a trap.

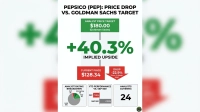
PepsiCo (NASDAQ:PEP | PEP Price Prediction) closed at $134.45 on October 20. The 24/7 Wall St. price target of $148.97 points to 10.8% upside over the next 12 months. The stock earns a buy rating with high confidence from the model.
| Metric | Value |
|---|---|
| Current Price | $134.45 |
| The price target from 24/7 Wall St. | $148.97 |
| Upside/Downside | 10.8% |
| Recommendation | BUY |
| Confidence Level | 90% |

The contrarian case depends on one thing: North American performance, starting with U.S. soft drinks. The international business is already strong. International organic revenue rose 8%, and management says international produced 45% of profit year to date.
If the U.S. catches up, a forward P/E near 15x looks cheap for a company that has raised its dividend 54 years in a row (we ordered ten members of that 50-year club by valuation in a free Dividend Kings report).
Shares Rally 6% in a Week Despite a Lowered EPS Outlook
PepsiCo rose 6.13% over the past week and 4.12% over the past month. Even so, it is down 3% year to date and 8.5% over one year. At about $135.10 midday, shares trade 18.8% below the 52-week high of $166.41 and 9.4% above the low of $123.47. On October 19, PepsiCo outperformed competitors.
In the third quarter, core EPS came in at $2.34 against a $2.30 estimate. Revenue of $25.27 billion beat expectations of $24.97 billion.
However, management lowered core constant currency EPS growth guidance to 1% to 2%, and North American snacks core operating profit fell 12%. Jim Cramer still said that “You could do a lot worse than buying the stock of PepsiCo down here.”
Why Bulls See $159 If U.S. Soft Drinks Turn
The repair work in North America is already showing results. Snacks volume has swung from low-single-digit declines to gains, which CEO Ramon Laguarta called “a major turnaround.” He also admitted that “we are not competing well in soft drinks,” and PepsiCo is now spending more behind Poppi, Pepsi, and Mountain Dew.
Advertising grew at a double-digit rate in both U.S. businesses. The CFO expects structural cost savings to start helping “as we turn the calendar year.” Our bull case reaches $159.19, an 18.4% return.
Wall Street is more conservative: 18 analysts rate the stock Hold, and only 5 have a bullish rating. That leaves room for upgrades if results improve.

Margin Pressure Is the Risk Worth Watching
Input-cost hedges are expiring, and a third-quarter tariff benefit will go away. Core operating margin fell by 35 basis points, and debt-to-equity is at 2.45. The bear case comes in at $137.62.
A good part of the margin fall is a deliberate choice, though. Management kept marketing budgets intact to drive growth. Similarly, the 19.57% drop in operating income for fiscal 2025 came mainly from impairments, which do not repeat.

PepsiCo Trades at a Steep Discount to Coca-Cola and Mondelez
Coca-Cola (NYSE:KO) is PepsiCo’s most direct beverage rival. It trades at 25x forward earnings with a 2.23% dividend yield.
Mondelez International (NASDAQ:MDLZ) competes with PepsiCo in global snacks and trades at 18x forward earnings. Our target values PepsiCo at about 17x forward EPS, still below both peers, so the peer group makes our target look conservative.
| Company | Forward P/E | Dividend Yield |
|---|---|---|
| PepsiCo | 15 | 4.41% |
| Coca-Cola | 25 | 2.23% |
| Mondelez | 18 | 3.16% |
Our Verdict: Valuation Gap and Dividend Tip the Scale
The 24/7 Wall St. price target is $148.97, with a buy rating and 90% confidence. The valuation gap to peers combined with a dividend yield above 4% tips the scale for me.
The case strengthens if U.S. soft drink volumes stabilize while cost savings protect margins. The case weakens if input-cost inflation forces another guidance cut. The model shows the potential reward outweighing the risk for now.
Here is where our model projects PepsiCo could trade if current trends hold:
| Year | The price target from 24/7 Wall St. |
|---|---|
| 2026 | $136.84 |
| 2027 | $148.97 |
| 2028 | $161.56 |
| 2029 | $173.93 |
| 2030 | $183.90 |
These projections assume PepsiCo keeps executing its current strategy. A lasting recovery in North America could drive results above this path, while sustained input-cost inflation could pull them below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.