Prediction: This Could Trigger NVDA’s Next Breakout by 2027
NVIDIA just posted triple-digit revenue growth and Wall Street keeps raising its price targets, yet the stock is drifting lower. One upcoming catalyst could change that trajectory in a dramatic way.

The quarter NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) just delivered would impress at a company one-tenth its size. Q2 fiscal 2027 revenue reached $96.22 billion, up 105.8% year over year. Data Center networking grew 138%, faster than compute.
Jensen Huang put it simply: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.”
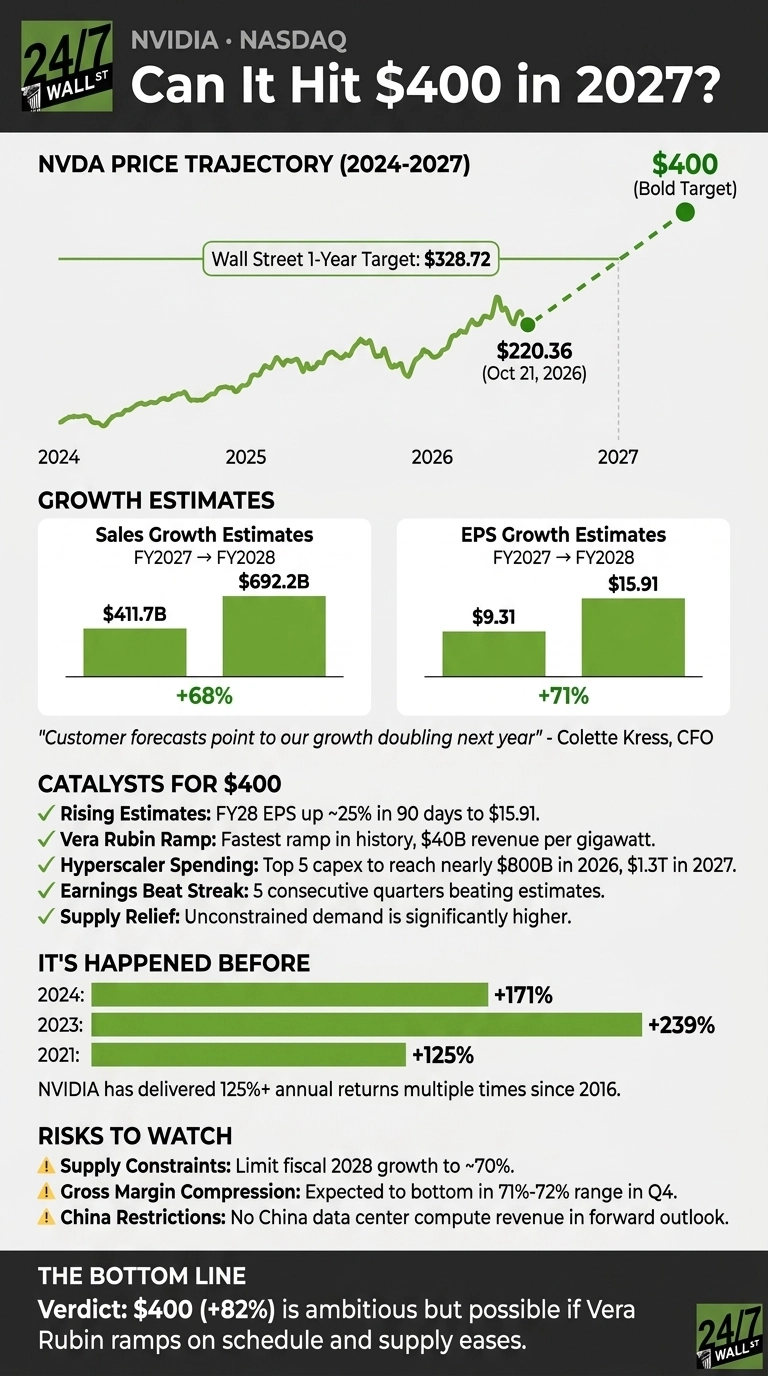
Shares are up 18.43% year to date at $220.36, but they fell 3.57% over the past week. Even rumors of a big China chip purchase failed to lift the stock. That break leaves room for a bigger move. NVIDIA’s path to $400 by late 2027 depends on rising earnings and a market-level multiple.
Wall Street Sees 49% Upside as Estimates Keep Climbing
The average analyst target is $328.72, which implies 49% upside. Ratings lean heavily positive, led by 10 Strong Buys, 49 Buys, 2 Holds and 1 Sell.

For fiscal 2028, analysts project revenue of $692.2 billion, up from $411.7 billion this year, or 68% growth. They expect EPS to rise about 71% to $15.9146. Management guides to similar growth.
CFO Colette Kress said “customer forecasts point to our growth doubling next year,” but NVIDIA expects roughly 70% because supply is tight.

Path to $400 Requires Only a Market-Level Multiple
NVIDIA currently trades at about 14x fiscal 2028 earnings. At $400, that rises to about 25x. That is a small premium to the S&P 500’s forward multiple of roughly 21-23x, and it would buy earnings growing at 71%.

What Could Push NVIDIA to $400?
- Rising estimates: 90 days ago, analysts expected fiscal 2028 EPS of $12.7636. Today the figure is $15.9146, about 25% higher, following 7 raised estimates and zero cuts in the past 30 days.
- Beat run: NVIDIA has beaten estimates for 5 consecutive quarters. In Q2 it earned $2.22 against an expected $2.09.
- Vera Rubin ramp: Management expects the fastest product ramp in company history. Rubin brings in $40 billion per gigawatt, compared with $25 billion for Blackwell.
- Hyperscaler spending: Capex at the top five hyperscalers is expected to reach nearly $800 billion in 2026 and $1.3 trillion in 2027.
- Supply relief and China: Huang said “the unconstrained number would be a lot higher.” The outlook includes no compute revenue from Chinese data centers, so any return there adds upside.
NVIDIA Has Topped This Gain Four Times Since 2016
Reaching $400 requires a gain of about 82%. NVIDIA has gone well beyond that before: shares rose 171% in 2024, 239% in 2023, 125% in 2021 and 224% in 2016.
With a market value of $5.33 trillion, repeating those returns is harder, but the stock has a track record of doing it.

$400 Is a Stretch, but the Math Holds Up
Hurdles remain: gross margin is expected to bottom at 71% to 72% in Q4, and days sales outstanding rose to 60 days. Reddit sentiment has also changed from bullish to neutral as concerns about AI financing grow.
Still, analysts already project 49% upside, and estimates are rising. NVIDIA trades at a forward multiple below the market’s. If Rubin ramps on schedule and supply eases, a 25x multiple on fiscal 2028 earnings would take the stock to $400.
That hyperscaler capex also has to be powered, cooled, and connected by someone, and we rounded up seven suppliers riding the same wave in a free report. Returns like this are rare, and this is how NVIDIA could deliver an outsized gain by 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.