Nobody Brags About Owning an HVAC Distributor. Watsco and Ferguson Shareholders Don’t Mind
Furnace parts and pipe fittings sound like the least exciting businesses imaginable, yet the companies stocking those shelves have quietly outpaced most of Wall Street over the past decade. Find out what makes replacement demand almost immune to consumer sentiment.

Furnace replacements look like a dull business. Still, the companies that stock the replacement parts have built long, quiet records. On an adjusted basis, Watsco (NYSE:WSO | WSO Price Prediction) shares have risen 221.06% over the past ten years, and Ferguson Enterprises (NYSE:FERG) has gained 426.31% over the same period. Both sell to contractors who fix broken air conditioners, furnaces, and pipes. A homeowner with no heat in January makes the call on whether the economy is doing well.
Watsco Stocks the Parts When the Air Conditioner Quits
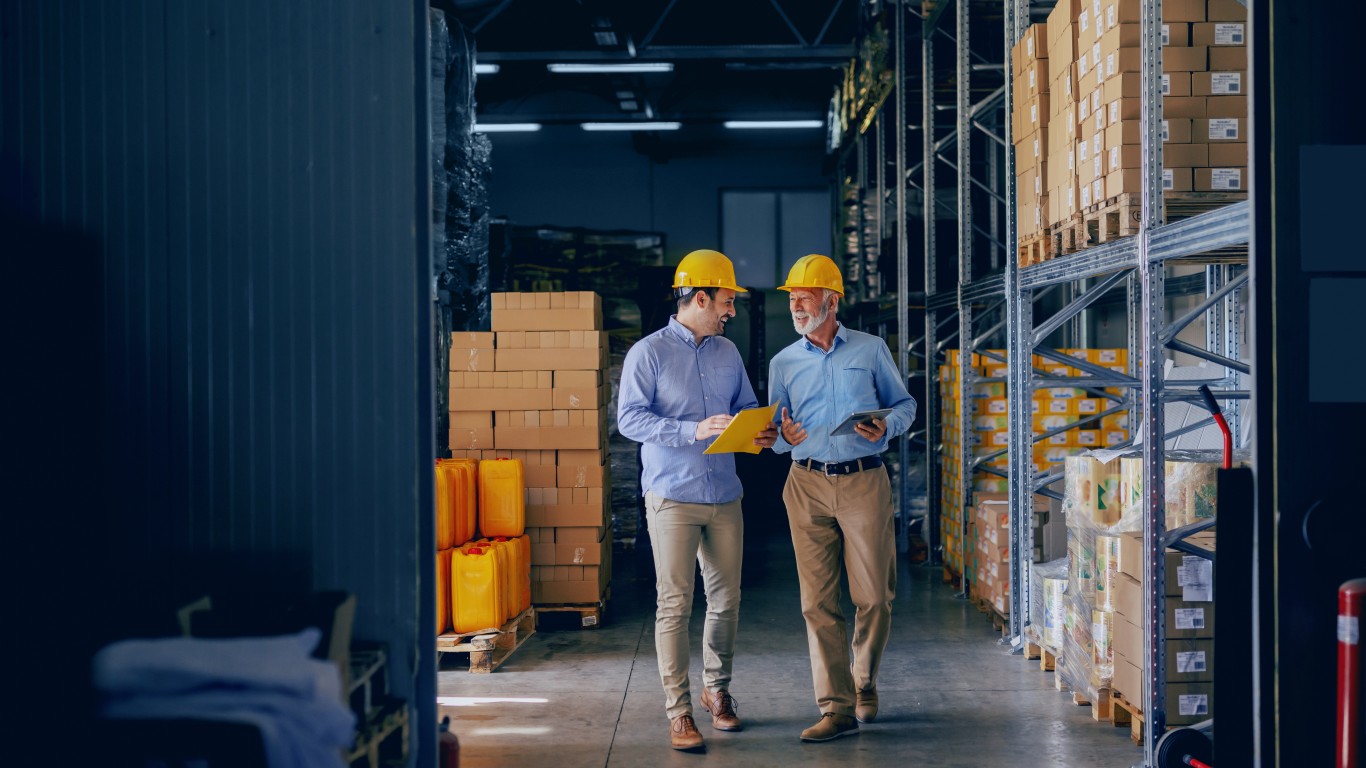
Watsco makes nothing. It buys heating, cooling, and refrigeration equipment from the major manufacturers and sells it, along with parts and supplies, to contractors. It is the largest distributor in the ~$74 billion North American HVAC/R market, operates from about 650 domestic locations, and serves over 70,000 contractors, installers, and technicians. HVAC equipment makes up about 67% of sales.

The market is still crowded, with more than 2,100 distributors, so Watsco continues growing the slow way: it buys regional operators and lets them continue running their businesses. In June 2026, it bought Jackson Supply, which has $230 million in annual sales and 25 Sunbelt locations.
Why Contractors Keep Coming Back
Replacement demand comes from equipment failure, not consumer sentiment. As Watsco’s president put it on the second-quarter call, “The products we sell are a necessity and the installed base continues to expand.”
The 2025 industry downturn tested that. Industry units were down 17% in the calendar year 2025 because, in the words of the chief financial officer, “The COVID period clearly borrowed replacement volume from the future.” Over that year, Watsco’s revenue fell 5.0% to $7.24B. It still earned $497M in net income, generated $570M in operating cash flow, and expanded gross margin 120 bps to a record 28.0%. That margin gain came from pricing optimization technologies and OEM pricing actions, which is about as close to proof of pricing power as a distributor gets. In the second quarter of 2026, domestic residential HVAC equipment unit volume rose 2%, and average selling prices rose 2%. Management described that price increase as “a very conventional level if I look back over a 10-, 15-year average.”
A Dividend Record Spanning Five Decades
In April 2026, Watsco raised its annual dividend 10% to $13.20/share, and management noted that “2026 marks our 52nd consecutive year of paying dividends.” That streak counts straight years of payments. The dividend history shows recurring quarterly ex-dividend records from 1999 through 2026, which means payments continued through both the 2008-2009 financial crisis and the 2020 pandemic. The quarterly payout has risen from 1.25 in 2017 to 3.3 per share now. The company carries zero debt.
Risk: Margins Are Settling Back Down
The 2025 margin record had help. Manufacturers raised prices aggressively that year, and Watsco’s gross margin fell to 27.5% in the second quarter of 2026, compared with 29.3% a year earlier. Diluted EPS of $4.00 missed the $4.39 consensus. New construction is also slowing in the company’s core markets, with the chief operating officer pointing to “a slowdown in new construction in the South, predominantly in Florida and in Texas.” Investors have noted that shares are down 11.52% over one year and were down 5.04% in the October 26 session. The third-quarter conference call is scheduled for Tuesday, October 27, 2026.
Ferguson Moves the Pipe, Valves, and Ductwork Behind Every Building
Ferguson calls itself North America’s largest value-added distributor of essential water and air solutions. It sells plumbing fixtures, HVAC equipment, pipe, valves, fittings, and water and wastewater products to professional contractors. It runs over 1,700 locations, employs about 35,000 associates, and generated approximately $31.3 billion in calendar 2025 sales.

Why Its Customers Stay
Its customers are specialists: plumbers, mechanical contractors, waterworks crews, and industrial buyers. Those customers face high switching costs due to Ferguson’s scale, local branch density, and project technical support. The chief executive summed up the model this way: “The scale-deployed local business model that we represent together with a multi-customer group approach continues to pay dividends.”
Selling to several end markets matters when housing stalls. In the fourth quarter of fiscal 2025, residential revenue fell 2% while non-residential grew 10%, and gross margin rose 90 bps to 30.6%. Management credited that to “disciplined execution and supplier price increase timing.” For the full year, gross margin expanded 70 bps, net income reached $2.01B, and operating cash flow came to $2.18B. In the quarter ended June 30, 2026, residential returned to 2% growth, non-residential rose 8%, and the HVAC customer group grew 11%. Adjusted diluted EPS of $3.39 beat the $3.30 consensus, and management raised its calendar 2026 outlook to mid-single-digit net sales growth.
A Short but Steady Payout Record
Ferguson’s regular quarterly dividend has risen once a year: from 0.75 in 2022-2023, to 0.79, then 0.83, and now 0.89 per share. Earlier distributions followed an irregular schedule, so the clean quarterly record is fairly new. Buybacks have done more of the work, with $0.9B bought back during 2025. The stronger long-run data point is the share price: up 70.46% over five years on an adjusted basis.
Risk: Housing Has Not Recovered
Management said residential markets remained weak across new construction and repair, maintenance, and improvement work, and Canadian revenue fell 1.9%. Ferguson also agreed to buy FloWorks, a valve and flow-control distributor, for an enterprise value of about $1.6 billion. That deal is expected to lift net debt-to-EBITDA from 1.3x to about 1.8x, still within its 1x to 2x target range. Shares are down 4.79% over one year.
What to Watch at Both Distributors
Both companies post steady, unflashy profits, and both stocks have been flat to down over the past year. They have steady demand from equipment that breaks on its own schedule, plus the scale to pass along price increases over time. The next things to watch are Watsco’s third-quarter margins and whether Ferguson’s guidance update after the FloWorks deal closes holds the line.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.