This Magnificent Seven Stock Could Have 100% Upside. Here’s the Case.
Alphabet just posted its fastest cloud growth in years, yet its stock trades at a fraction of what rivals command. Whether that gap is a rare opportunity or a warning sign depends on one number hiding inside the balance sheet.

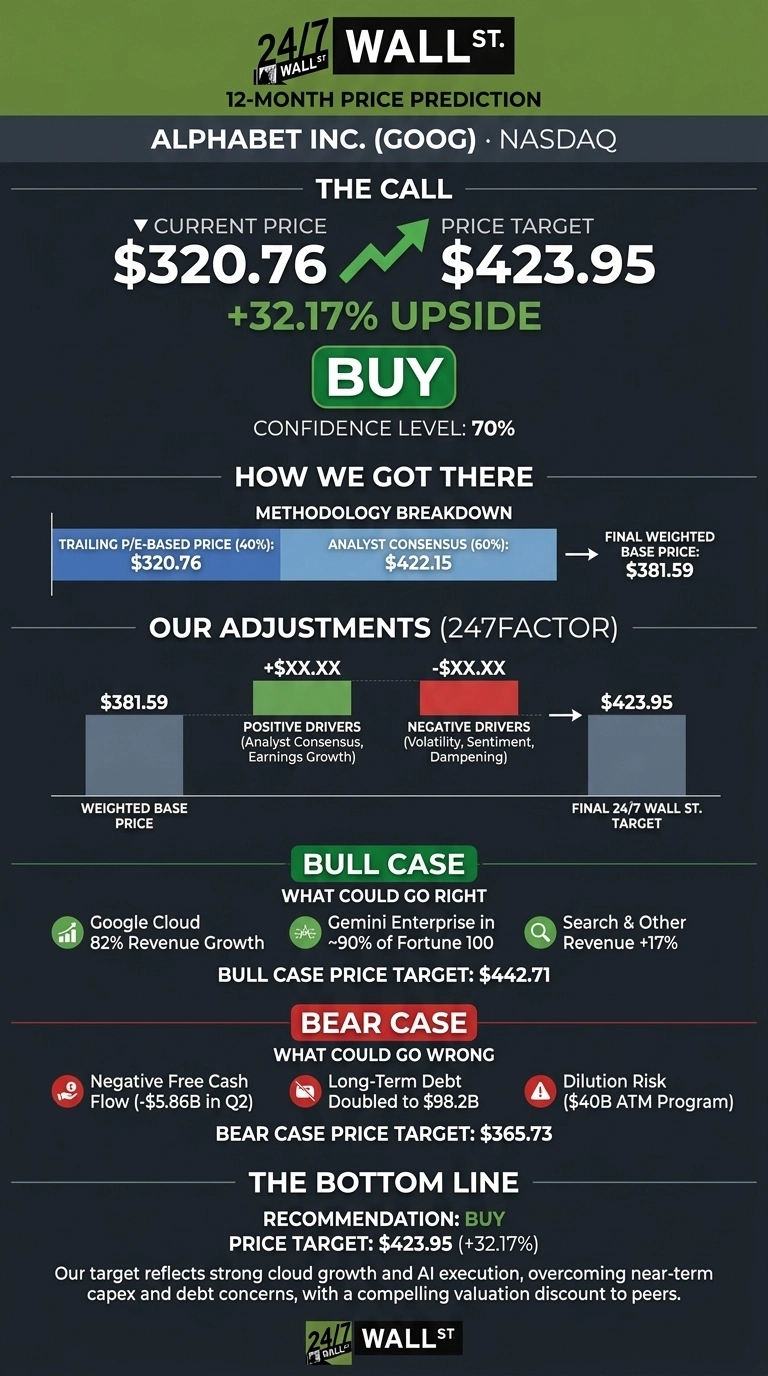
Our 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG | GOOG Price Prediction) is $423.95 over the next 12 months. The larger long-term upside case comes from our five-year model.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $320.76 |
| Price Target from 24/7 Wall St. | $423.95 |
| Upside/Downside | 32.17% |
| Recommendation | BUY |
| Confidence Level | 70% |
We rate Alphabet a buy with moderately high confidence. Our five-year base case reaches $710.20 by October 2031, a total return of 121.41%.
That is where the long-term upside in our headline comes from. Alphabet trades at 13x trailing earnings while Google Cloud grows 82%. I think that gap stands out.
An October Pullback Widens the Gap to Our Target
Shares changed hands at $318.28 early Friday. They are down 7.72% for the week and 8.38% for the month, which leaves them up just 1.63% year to date but 26.37% over 12 months. The stock sits below its 52-week high of $403.96 and well above its $255.43 low. The business itself keeps getting stronger.
Second-quarter revenue rose 24.2% to $119.80 billion, ahead of the $116.91 billion consensus. EPS came in at $9.11 against a $3.04 estimate, although a $99.03 billion unrealized equity gain inflated that number.
Even so, operating income grew 30.4%. Forbes is also among the outlets taking up the buy case this week.
Why Bulls See $442 and Beyond
Cloud is the engine. Segment revenue reached $24.77 billion, and the segment’s operating margin expanded to 35.6% from 20.7%. Its backlog stands at $514 billion. Nearly 90% of the Fortune 100 use Gemini Enterprise, and the Gemini app has 950M monthly users. Search revenue grew 17%, which runs against the fear that AI would disrupt it.
CEO Sundar Pichai described Alphabet as being in the “very early innings” of a secular shift. On Wall Street, 13 analysts rate the stock a strong buy, 44 rate it a buy and none rate it a sell, with a consensus target of $422.15. The bull scenario reaches $442.71.

Capex and Debt Are the Risks Worth Watching
Capex doubled to $44.92 billion, and free cash flow turned negative at $5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion. Alphabet also suspended its buyback and added a $40B at-the-market program, so dilution is possible.
The bear case is $365.73. That still sits above today’s price. There is also a balance to the cash burn: trailing 12-month free cash flow was $53.3 billion, and Alphabet holds $242.5 billion in cash and marketable securities.
Alphabet’s doubled capex is going straight into the data-center expansion, and the suppliers of power, cooling, and networking collect a check regardless of which hyperscaler wins. We featured seven of them in a free report, here.
Alphabet Trades Far Below Microsoft and Meta
| Company | P/E | Operating Margin |
|---|---|---|
| Alphabet | 13 | 32.06% |
| Microsoft | 29 | 46.78% |
| Meta | 24 | 41.44% |
Google Cloud’s most direct AI rival is Microsoft (NASDAQ:MSFT), and its full-year Azure revenue exceeded $100 billion. Microsoft’s margins are higher, but Alphabet’s cloud business is growing faster.
Meta Platforms (NASDAQ:META) is also chasing those ad dollars. It grew revenue 26.07% last quarter but posted negative free cash flow of $2.12 billion, so heavy AI spending is squeezing peers too. Our target means about 16x earnings, still below both peers, which makes it look conservative.
What Could Push Alphabet Toward Our Target
Our 24/7 Wall St. price target of $423.95 comes with a buy rating at 70% confidence. What tips the scale for me is Cloud’s margin expansion.
My confidence would grow if Cloud keeps converting its backlog at margins in the mid-30s. My confidence would weaken if free cash flow stays negative while debt keeps climbing. On balance, I think the discount looks too wide relative to the fundamentals.
The 24/7 Wall St. price target model projects Alphabet could trade here if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $423.95 |
| 2027 | $482.32 |
| 2028 | $548.72 |
| 2029 | $624.26 |
| 2030 | $710.20 |
The projections rest on Alphabet continuing to execute on its AI strategy. Antitrust action or weak returns on its infrastructure spending could change the path significantly.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.