Several Important Factors Protect Amazon’s Margins and Secure Its AI Moat
Amazon's stock has barely budged this year, yet the business underneath it is accelerating in ways that make most rivals look structurally overpriced. One looming risk, though, could unravel the entire thesis if a single market condition shifts.

I added to my Amazon (NASDAQ:AMZN | AMZN Price Prediction) position again. Every earnings report gives me another reason to keep doing it. The stock sits at $249.09, up only 7.92% year to date, while the business behind it speeds up. That gap is why I keep adding.
Three Moats Protecting Amazon’s Margins
My thesis is simple. Amazon controls its own costs in AI. The company designs its own chips, offers every major AI model through one platform, and uses robots to move physical goods at a scale I have not seen any retailer match.
Start with custom silicon. Amazon’s chips business runs at an annual revenue rate of over $25 billion, growing at triple-digit rates. Graviton is used by 98% of Amazon’s top 1,000 EC2 customers, and Anthropic and OpenAI both signed multi-year Trainium commitments measured in gigawatts. Cheaper in-house chips helped AWS post a 39% operating margin on $42.2 billion in revenue, which grew 36.7%. That was its fastest growth in 18 quarters.
Second, Bedrock works with any model. It added 10+ foundation models, including OpenAI GPT and Anthropic Claude, and customers spent more on it in Q2 than in all prior quarters combined. CEO Andy Jassy put it simply: “There is not going to be one model to rule the world.” Amazon gets paid whichever model customers pick. An AWS backlog of $496 billion tells me enterprises agree.
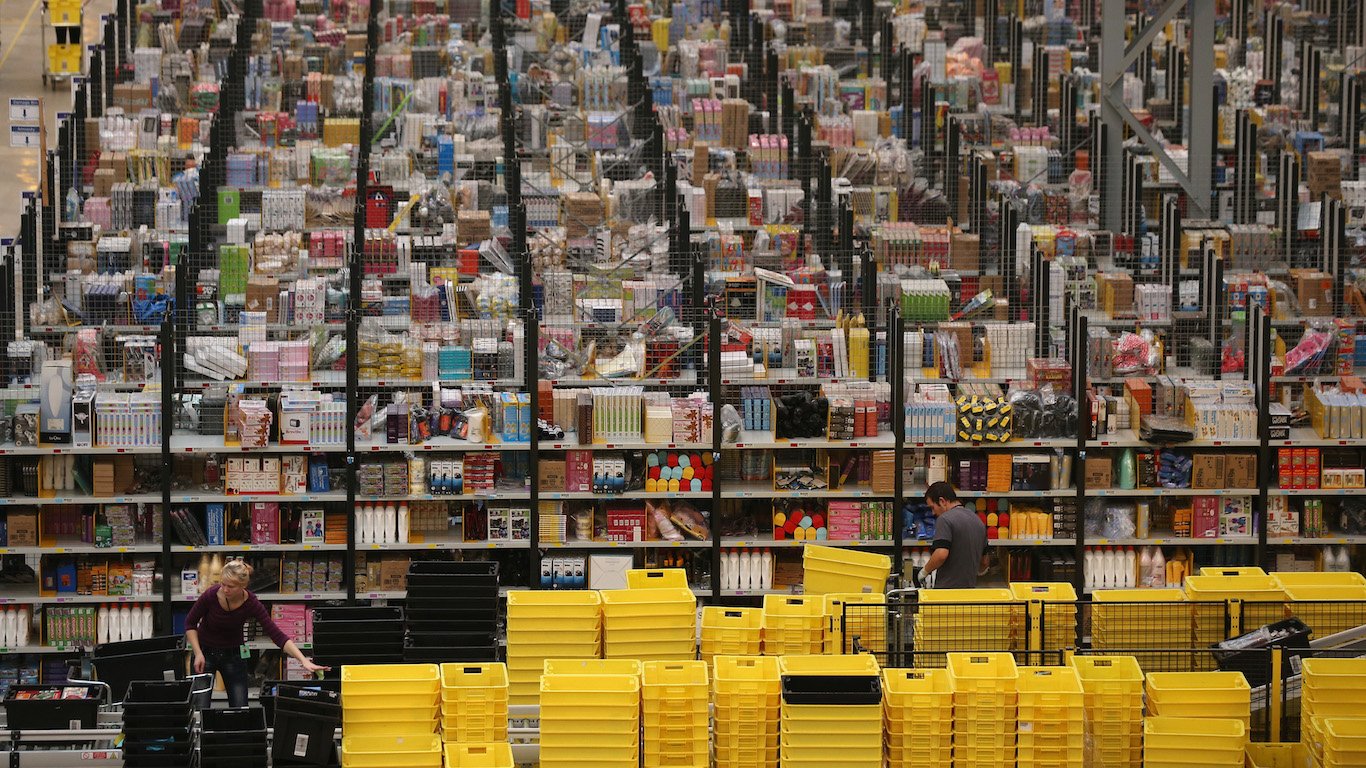
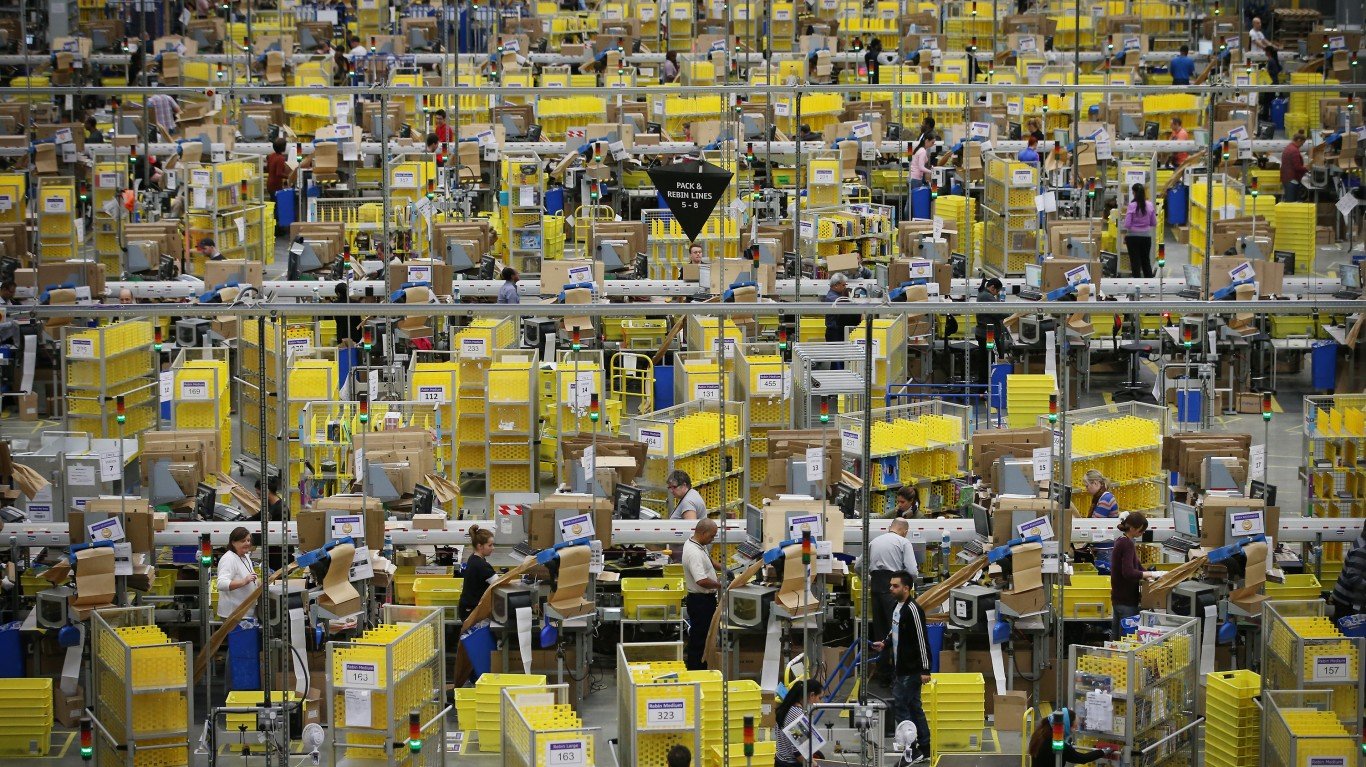
Third, automated logistics. Amazon delivered over 40% more items same day or overnight in the first half of the year, plans to more than double its robotic-arm fleet in 2026 and launched a next-generation Proteus robot. Operating income rose 43.24% to $27.46 billion while revenue grew 19.62%. Profits growing faster than sales is exactly what I want to own.
Why My Money Skips Walmart and Microsoft
Walmart (NASDAQ:WMT) trades at a P/E of 44, compared with Amazon’s 35. Walmart’s operating margin is 4.18% and Amazon’s is 11.16%, and Walmart’s revenue grew 5.94% last quarter. I see no reason to pay more for slower growth and lower margins with no cloud business attached.
The stronger rival is Microsoft (NASDAQ:MSFT), with Azure growing 43%. Still, Microsoft trades at 8.94 times book value, while Amazon trades at 6.54. Its More Personal Computing segment also contracted 4%. Every Amazon business line grew, from advertising at 26% to physical stores at 4%.
Free Cash Flow Is the Risk I Watch Most
Amazon now expects about $220 billion in 2026 capital spending, up from about $200 billion, because memory costs rose. Free cash flow for the past 12 months turned negative, at -$7.6 billion. Q2 GAAP EPS of $5.75 also included a $53.4 billion one-time gain on Amazon’s Anthropic stake, recorded before taxes. If AI demand cools, that spending leaves Amazon with idle capacity.
I still hold my thesis because Amazon builds against demand customers have already signed for. Jassy said most capacity coming online in 2027 is already reserved, most AI capacity sits under contracts of at least five years, and servers pay for themselves in a little under three years. All that spending has to be powered, cooled and connected by somebody, and we rounded up seven suppliers riding the same expansion in a free AI infrastructure report. Debt-to-equity of 0.37 leaves room to fund the expansion.
What Keeps My Buy Button Active
Q3 guidance calls for operating income of $22.5 billion to $26.5 billion, up from $17.4 billion a year earlier. Jassy now believes AWS could become “a trillion-dollar annual revenue business for us in time.” Amazon builds the chips, hosts the models and delivers the boxes, and I plan to keep buying more of all three.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.