Costco Stock’s Long-Term Upside Could Come From These 3 Competitive Advantages
Costco commands a valuation premium that makes even its biggest fans nervous, yet three structural advantages keep analysts bullish and renewal rates near record highs. Understanding what actually drives that loyalty reveals whether the stock deserves its lofty price or…


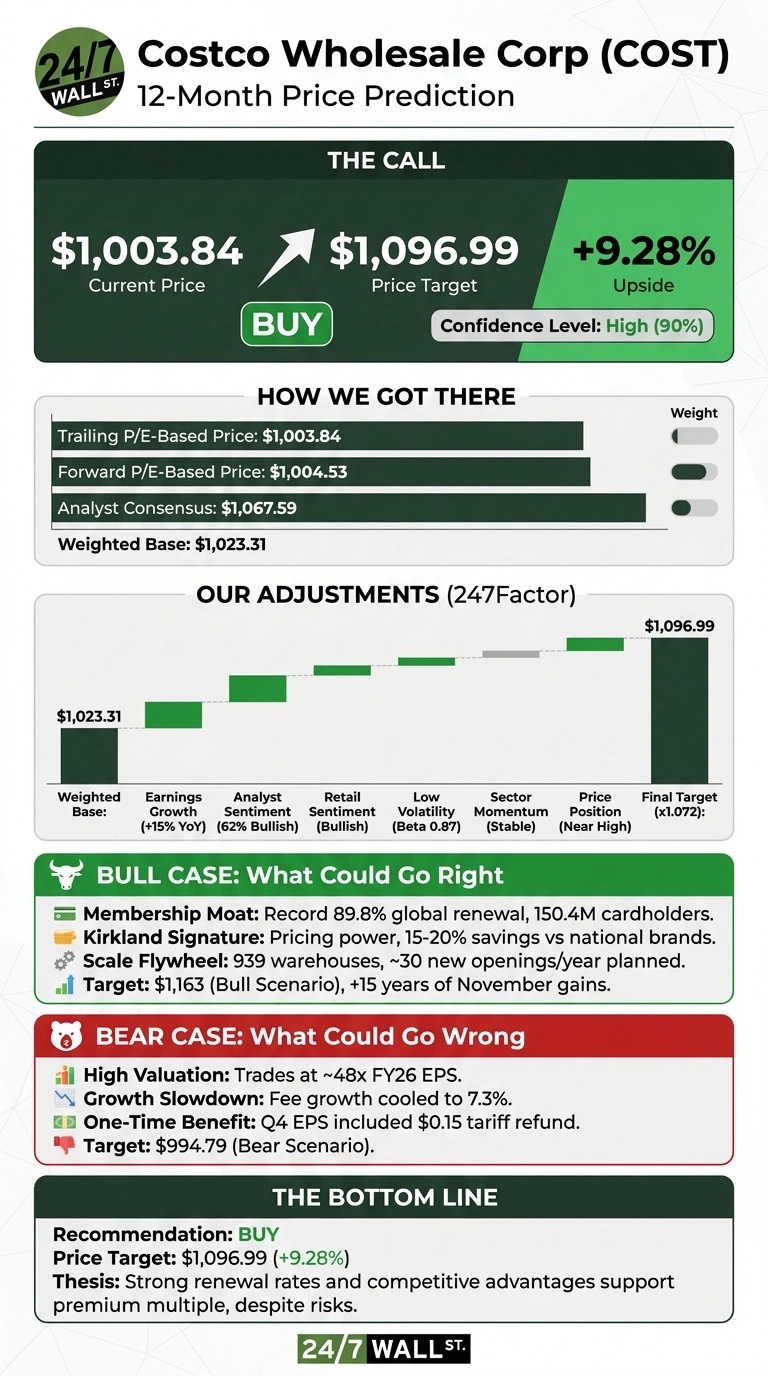
Our 24/7 Wall St. price target for Costco (NASDAQ:COST | COST Price Prediction) is $1,096.99. That is 9.28% above the model’s reference price of $1,003.84, and it comes with a buy rating and high confidence.
| Metric | Value |
|---|---|
| Current Price | $1,003.84 |
| Price Target from 24/7 Wall St. | $1,096.99 |
| Upside/Downside | 9.28% |
| Recommendation | BUY |
| Confidence Level | 90% |

Three competitive advantages support that call. The first is a membership moat. The second is Kirkland Signature, a private label that gives Costco pricing power.
The third is a scale flywheel that keeps traffic growing. Together they explain why investors keep paying a premium multiple for a grocer.
Costco Is Up 16% in 2026 as Traffic and Digital Sales Accelerate
Shares traded at $998.45 Tuesday morning. They are up 8.2% over the past month and 16.29% year to date. That leaves Costco 8.8% below its 52-week high of $1,094.76 and 18.8% above its low of $840.35.
Fiscal fourth-quarter EPS came in at $6.75, beating the $6.53 estimate, and revenue of $95.72 billion grew 11.1%. Comparable sales rose 9.4%, traffic increased 3.3% and digitally enabled comps climbed 19.5%.

Three Advantages Behind the Bull Case for $1,163
Membership moat: Costco ended the year with 150.4 million cardholders and a worldwide renewal rate of 89.8%. Paid executive members rose 9.4%. On the September call, CEO Ron Vachris said “Our membership continues to be the most important item we sell.”
Kirkland Signature: Kirkland products save members at least 15% to 20% compared with national brands. Vachris called new Kirkland items “effective tools for us to fight back on pricing.”
Scale flywheel: Costco runs 939 warehouses and plans 33 openings in fiscal 2027. Management projects a path to about 30 new warehouses a year for the next five to ten years.
Analysts lean bullish. Their consensus target is $1,067.59, with 24 Buy or Strong Buy ratings. A technician on CNBC’s Fast Money noted that Costco has risen in November 17 years in a row. Our bull scenario reaches $1,162.99.

A 48x Multiple Leaves Little Room for Error
Costco trades at about 48 times fiscal 2026 EPS of $20.76. Even a small slowdown in growth could pull that multiple lower, and our bear scenario points to $994.79. Fourth-quarter EPS also included a $0.15 one-time benefit from tariff refunds.
Membership fee growth cooled to 7.3% from 14.0% in the first quarter, though much of that slowdown comes from comparing against the earlier fee increase. Capex is set to rise to about $7.5 billion, but free cash flow still grew 19.82%, so Costco is funding that spending from strength.
How Costco Compares to Walmart and BJ’s Wholesale Club
Walmart (NASDAQ:WMT) competes directly through Sam’s Club. It trades at about 44 times earnings, while its U.S. comps grew 2.6%. Costco’s premium looks earned against that slower growth.
BJ’s Wholesale Club (NYSE:BJ) is the purest warehouse-club peer. Its comps rose 3.1% excluding gas, about half of Costco’s adjusted 6.7%. Against both peers, our target looks reasonable.
| Company | Market Cap | Latest Comps |
|---|---|---|
| Costco | $442.8B | 6.7% (adj.) |
| Walmart | $951.4B | 2.6% (U.S.) |
| BJ’s | $13.4B | 3.1% (ex-gas) |
Costco Earns Our BUY Rating
Our 24/7 Wall St. price target of $1,096.99 carries a buy rating with 90% confidence. What tips the scale for me is renewal rates near record highs.
The bull case strengthens if traffic keeps growing and executive penetration keeps climbing. The case weakens if comps fall back toward peer levels while the multiple stays near 48x.
Assuming current trends hold, our model’s year-end targets for Costco are below:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,029.51 |
| 2027 | $1,114.18 |
| 2028 | $1,200.97 |
| 2029 | $1,281.44 |
| 2030 | $1,372.51 |
These projections assume Costco keeps opening around 30 warehouses a year. A drop in renewals or a correction in its premium multiple could change the path in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.