Costco Stock Looks Expensive. Here’s Why Investors Keep Buying
Costco trades at a valuation that would make most investors flinch, yet buyers keep stepping in and analysts keep raising targets. The reason comes down to one membership metric that changes the math entirely.

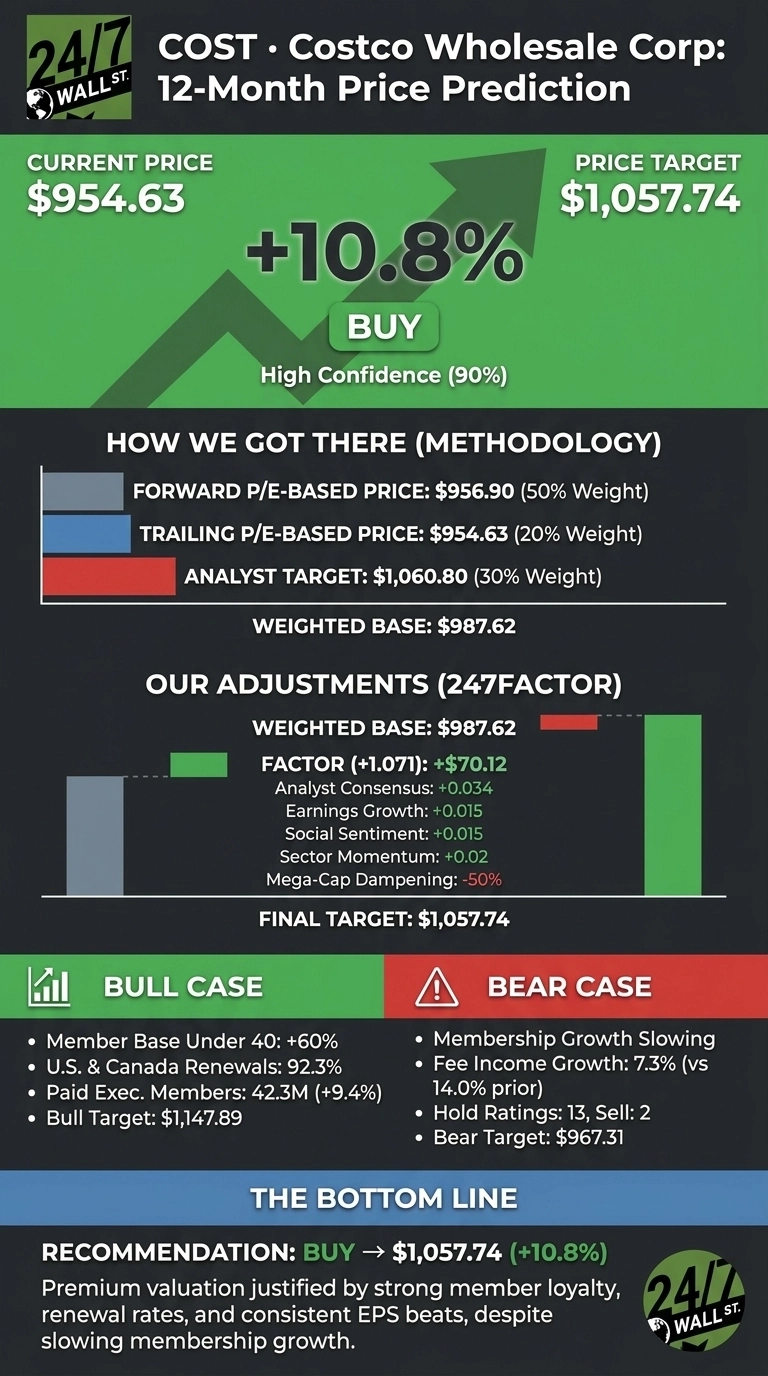
Costco (NASDAQ:COST | COST Price Prediction) closed its latest full session at $954.63. The 24/7 Wall St. price target for Costco is $1,057.74 over the next 12 months, which implies 10.8% upside. The stock earns a buy rating with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $954.63 |
| Price Target from 24/7 Wall St. | $1,057.74 |
| Upside/Downside | 10.8% |
| Recommendation | BUY |
| Confidence Level | 90% |

Valuation is the main point. Costco trades at roughly 46x trailing earnings and 42x forward EPS of $22.7822. Our model still sees upside because membership loyalty, steady traffic gains and a six-quarter EPS beat run keep justifying that premium.
A Strong Fiscal Year Finish Revived the Rally
Shares rose 1.32% to $967.21 in Wednesday trading and are up 3.37% over the past week, 6.9% over the past month and 12.66% year to date. At its latest close, Costco sat 12.8% below its 52-week high of $1,094.76 and 13.6% higher than its low of $840.35.
The fiscal fourth quarter, reported September 24, delivered EPS of $6.75 versus the $6.53 estimate, including a $0.15 one-time tariff refund benefit.
Revenue of $95.72 billion beat expectations and grew 11.1%. Comparable sales rose 9.4%, or 6.7% excluding gas and currency. That resilience recently gave CNBC’s Jim Cramer a reason to feel better about the stock.
Why Bulls See $1,147 Within Reach
Membership quality keeps improving. Paid executive members reached 42.3 million, up 9.4%, and U.S. and Canada renewals hit 92.3%. CEO Ron Vachris noted that “our member base under 40 has grown nearly 60% since COVID,” which builds a pipeline of future high spenders.
Costco plans 33 openings in fiscal 2027, and online enabled sales exceeded $33 billion. With 24 Buy or Strong Buy ratings on the stock, the bull case reaches $1,147.89.

What Could Keep Costco Stuck in Its Range
A 46x multiple leaves little room for error. Analysts also noted that membership growth has slowed for eight consecutive quarters, and fee income growth cooled to 7.3% from 14.0% in fiscal Q1.
As a counterpoint, much of that deceleration reflects lapping the 2024 fee increase. Excluding the increase and currency, fee income still grew 6.8%. With 13 Holds and two Sell-side ratings, our bear case stands at $967.31.

Costco’s Premium Over Walmart and BJ’s Looks Earned
Walmart (NASDAQ:WMT) is the closest big-box rival and has Sam’s Club. It trades at about 41x earnings, yet Walmart U.S. comps grew just 2.6% last quarter. Costco’s small premium buys far faster comp growth, which makes our target look reasonable.
BJ’s Wholesale Club (NYSE:BJ) is the pure-play warehouse peer. BJ’s grew fee income 9.9% to a record 8.5 million members, but comps excluding gas rose only 3.1%. Costco’s ex-gas growth more than doubles that, supporting a conservative read on our target.
| Company | P/E | Latest Comp Sales |
|---|---|---|
| Costco | 46x | 9.4% |
| Walmart (U.S.) | 41x | 2.6% |
| BJ’s (ex-gas) | Not available | 3.1% |
Premium Price, Premium Business: BUY
The 24/7 Wall St. price target of $1,057.74 supports a buy rating with 90% confidence. Renewal strength tips the scale.
I’d view the stock even more favorably if executive penetration keeps climbing and renewals improve further. I’d turn conservative if membership growth keeps slowing without offsetting spend gains. Costco is expensive, and I think the business keeps earning that premium.
Here is where the 24/7 Wall St. price target model projects Costco could trade, assuming current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (December) | $954.59 |
| 2027 | $1,061.05 |
| 2028 | $1,156.13 |
| 2029 | $1,219.90 |
| 2030 | $1,312.05 |
These estimates assume Costco keeps executing on warehouse expansion and membership growth. Multiple compression or a faster international rollout could move results meaningfully in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.