Prediction: ASTS Could Be Entering Its Biggest Growth Phase Yet
AST SpaceMobile has shed more than 40% this year, but a funded constellation, 60-plus carrier partners, and potential billion-dollar government contracts suggest the selloff may have punished the stock far beyond what the fundamentals warrant.

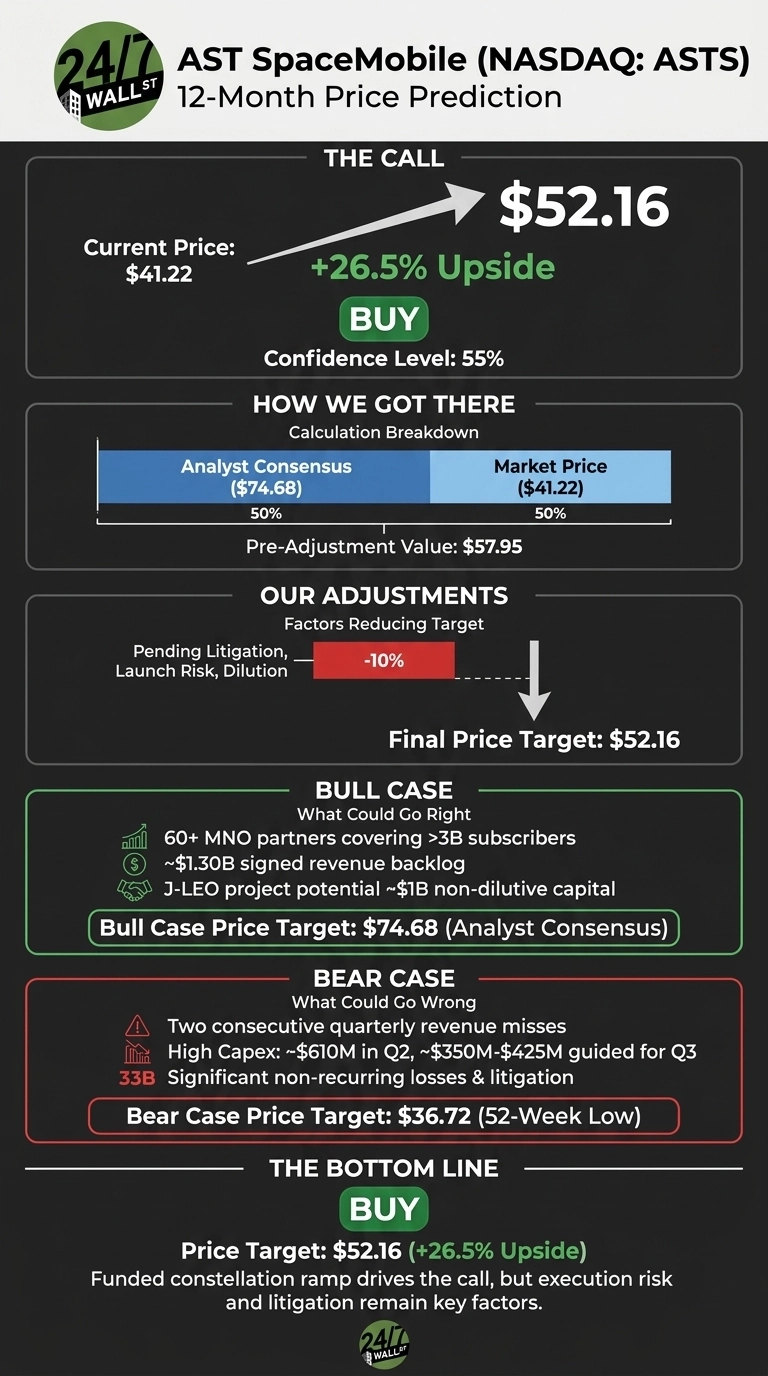
Our 24/7 Wall St. price target for AST SpaceMobile (NASDAQ:ASTS) is $52.16. That implies 26.5% upside from the current $41.22.
| Metric | Value |
|---|---|
| Current Price | $41.22 |
| 24/7 Wall St. Price Target | $52.16 |
| Upside/Downside | 26.5% |
| Recommendation | BUY |
| Confidence Level | 55% |
ASTS earns a buy rating with moderate confidence of 55%, which shows real execution risk.
AST SpaceMobile is moving from prototype to scaled constellation. They have 13 spacecraft in orbit, BlueBirds 17 through 46 in production, and a target of 45 satellites in orbit by early 2027. In my view, the recent sell-off places too much weight on the risks and too little on the build-out.
A 33% Monthly Slide Resets the Entry Point
ASTS fell 33.31% over the past month and 43.25% year to date, though it has steadied with a 0.22% gain this week. Shares trade 69.2% below the 52-week high of $133.86 and 12.3% above the $36.72 low.
Second-quarter revenue of $31.52M missed the $34.40M consensus, and GAAP EPS of -$0.77 missed the -$0.2873 estimate. Several securities class actions now cover a class period from March 4, 2025 to July 15, 2026, and the lead-plaintiff deadline falls on November 13, 2026.
Why Bulls See $75 and Beyond
AST SpaceMobile has 60+ MNO partners covering >3B subscribers and about $1.30B in signed backlog. Japan’s J-LEO project could bring in up to approximately USD 1 billion in non-dilutive, non-debt government capital.
The company’s president said government work could scale into “a recurring multibillion dollar a year opportunity starting in 2027.” Management also expects revenue approaching $1 billion in the first full year of commercial service, supported by pro forma liquidity above $3.70B.
Five analysts have bullish ratings on the stock. My bull case is the $74.68 consensus target.
What Could Push ASTS Back to Its Lows
Revenue has missed estimates in two straight quarters, which puts pressure on the $150M-$200M full-year guidance. Spending is also heavy: capex was about $610 million in the second quarter, with another $350 million to $425 million guided for the third.
The GAAP loss looks better on closer inspection, though. It included a $125.9M BB7 involuntary-conversion loss and $88.7M in induced conversion expense, and both are non-recurring. Seven analysts rate the stock a Hold and two rate it bearish. My bear case is a retest of $36.72.
Is ASTS Too Expensive Next to Iridium and Viasat?
| Company | Price/Sales | EV/Revenue |
|---|---|---|
| AST SpaceMobile | 133.16 | 109.58 |
| Iridium | 5.22 | 7.11 |
| Viasat | 1.977 | 2.951 |
Iridium Communications (NASDAQ:IRDM | IRDM Price Prediction) is the mature, profitable version of direct satellite connectivity. The stock is valued at 23x forward earnings on $902.97M in trailing revenue. That revenue base is close to where AST SpaceMobile hopes to be in its first full year of commercial service.
Viasat (NASDAQ:VSAT) competes for the same government and mobility dollars and brings in $4.63B in trailing revenue. Yet its market cap of $9.15B sits below AST SpaceMobile’s. This group shows that ASTS is priced on its future network. Our target makes sense only if that revenue ramp shows up, and with that condition I see the target as reasonable.
Growth Phase Tilts the Scale Toward Upside
I rate ASTS a buy, with a 24/7 Wall St. price target of $52.16 and 55% confidence. The funded constellation ramp is the key reason for my call.
I would turn more constructive if beta service launches on schedule and fourth-quarter revenue lands within guidance. I would get cautious if launches slip again or MNO agreements stall before becoming final contracts. On balance, I think the decline has gone further than the fundamentals justify.
AST SpaceMobile Price Prediction 2026-2030
Looking further out, here is where the 24/7 Wall St. price target model projects ASTS could trade if current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $46.69 |
| 2027 | $52.16 |
| 2028 | $65.20 |
| 2029 | $81.50 |
| 2030 | $101.88 |
The projections rest on AST SpaceMobile continuing to execute on its constellation plan. Results could swing sharply higher or lower depending on when commercial service starts, how government contracts scale, and how the litigation is resolved.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.