Vertiv Staged a Small Comeback After Cratering for 6 Months: This Wall Street Team Predicts 76% Gains From Here
Vertiv cratered 36% from its peak as a revenue miss, quality concerns, and an 11-session losing streak piled up against a stock with a beta above 2. Now one Wall Street team sees a path that leaves the consensus target…

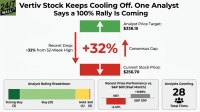
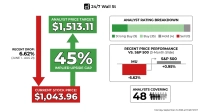
Vertiv (NYSE:VRT | VRT Price Prediction) currently trades at $243.17. The average price target among analysts is $333, which implies 36.9% upside.
Vertiv makes the power systems, thermal management gear and services that keep data centers running. That makes it one of the most direct ways to own the AI infrastructure expansion. The headline number comes from Melius Research, which has a street-high target of $427. From today’s price, that works out to 75.6% upside.
Both figures follow a sharp drop. Shares sit about 36% below their 52-week high of $379.76.
A Q2 Revenue Miss Started Six Months of Selling
The biggest hit came from second-quarter revenue. Vertiv reported $3.27 billion, below a consensus estimate of about $3.38 billion. Shares dropped even though EPS beat and guidance went up (the revenue miss outweighed the beat). Management later cited supply chain issues and said it recovered roughly $100 million to $150 million of that delayed revenue in Q3.
Quality concerns made things worse. On the latest call, analysts asked about reports of compressor failures and overheating UPS systems. Shares lost 20.32% over six months, including an 11-session losing run that was the longest since the company began trading. A beta of 2.048 helps explain why Vertiv swung harder than the rest of the sector.
The rebound came with Q3. Adjusted EPS of $2.21 beat the $1.82 consensus, revenue of $4.31 billion beat the $3.76 billion estimate, and organic orders more than doubled. The stock rose 16.59% in a single session.
Why 25 of 29 Analysts Still Rate Vertiv a Buy
Of the 29 analysts covering the stock, 25 rate it a Buy or Strong Buy, 4 rate it a Hold and none rate it a Sell. Estimates are rising. Over the past 30 days, the full-year 2026 EPS estimate saw 4 up revisions and no cuts. The 2027 consensus rose to $9.1945 from $8.8234 90 days ago.
Management’s new guidance of $7.10 to $7.20 in adjusted EPS is above the current $6.7341 consensus, leaving a gap between guidance and current estimates. The CEO expects “continued significant above-market organic sales growth in 2027.” Native 800-volt DC power is expected to start producing revenue during 2027, with wider release in 2028.
Melius looks two years out. It applies a 35x multiple to projected 2028 EPS of $12.20. Its argument is that racks like the NVL72 from NVIDIA (NASDAQ:NVDA) produce too much heat for air cooling, which drives buyers toward Vertiv’s liquid cooling units and chillers. Executive chairman Dave Cote summed it up on the call: “No data centers, no digital age. And Vertiv supplies the picks and shovels.” Still, a target based on earnings two years away depends on everything going right, and no price target is guaranteed.
Vertiv is the clearest picks-and-shovels name here, but it is one of several infrastructure suppliers riding the same build cycle (we covered seven of them, from power to cooling to networking, in a free report you can grab here).
Electrical Peers Fell Too, and nVent Shows More Upside on Paper
Peers slid over the past month, while Vertiv also faced its own company-specific problems.
Eaton (NYSE:ETN) has fallen 8.93% over the past month. With shares at $392.97 and a target of $485.47, it offers 23.5% implied upside. 23 analysts rate it a Buy, 4 a Hold and 1 a Strong Sell. That is less upside than Vertiv.
nVent Electric (NYSE:NVT) has dropped 12.55% over the past month. With shares at $140.13 and a target of $203.29, it offers 45.1% implied upside. 16 analysts rate it a Buy, with one Hold and one Strong Sell.
On consensus targets, nVent has the most upside among these names. Vertiv only leads if you accept Melius’s longer timeline.
Vertiv Is Still Up 50% This Year After the Pullback
Vertiv trades at $243.17 against a $333 consensus target from 29 analysts. That is 36.9% implied upside. Shares are up 50.2% year to date, while the S&P 500 is up 13.27%.
The stock gained 14.62% in the past week but is down 0.36% over the past month. The shares change hands at 22x forward earnings, less than half its trailing multiple of 47x.
Vertiv Rebound Hinges on Supply Recovery and Quality Fixes
Shares look more compelling if Q3’s supply recovery holds and record orders keep turning into revenue near the $4.31 billion to $4.51 billion Q4 guidance range. Liquid cooling share gains and 800-volt DC revenue in 2027 would give the stock a path back toward $333.
The bear case gains weight if the quality reports grow into warranty costs or customer losses, or if hyperscalers slow their capital spending. A stock with a beta above 2 gets hit hard when either happens.
The data leans positive. Estimates are rising, guidance is above consensus, and the forward multiple of 22x sits well below the trailing 47x. Fundamentals line up with the bullish analyst consensus. Next quarter’s delivery pace is worth monitoring before giving full weight to Melius’s $427 target.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.