Seagate Technology Fell 25% in The Last Month But One Wall Street Analyst Says 140% Gains to Come
Seagate just posted record earnings and guided well above Wall Street expectations, yet the stock cratered anyway. One analyst sees a path to 140% gains from here, but the market is sending a very different signal.

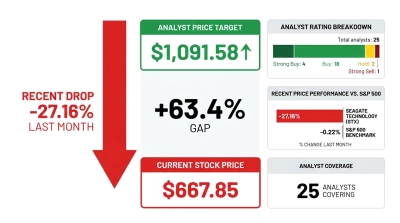
Seagate Technology (NASDAQ:STX | STX Price Prediction) trades at $667.85. Wall Street’s average price target is $1,091.58, which implies 63.4% upside to where analysts think it belongs.
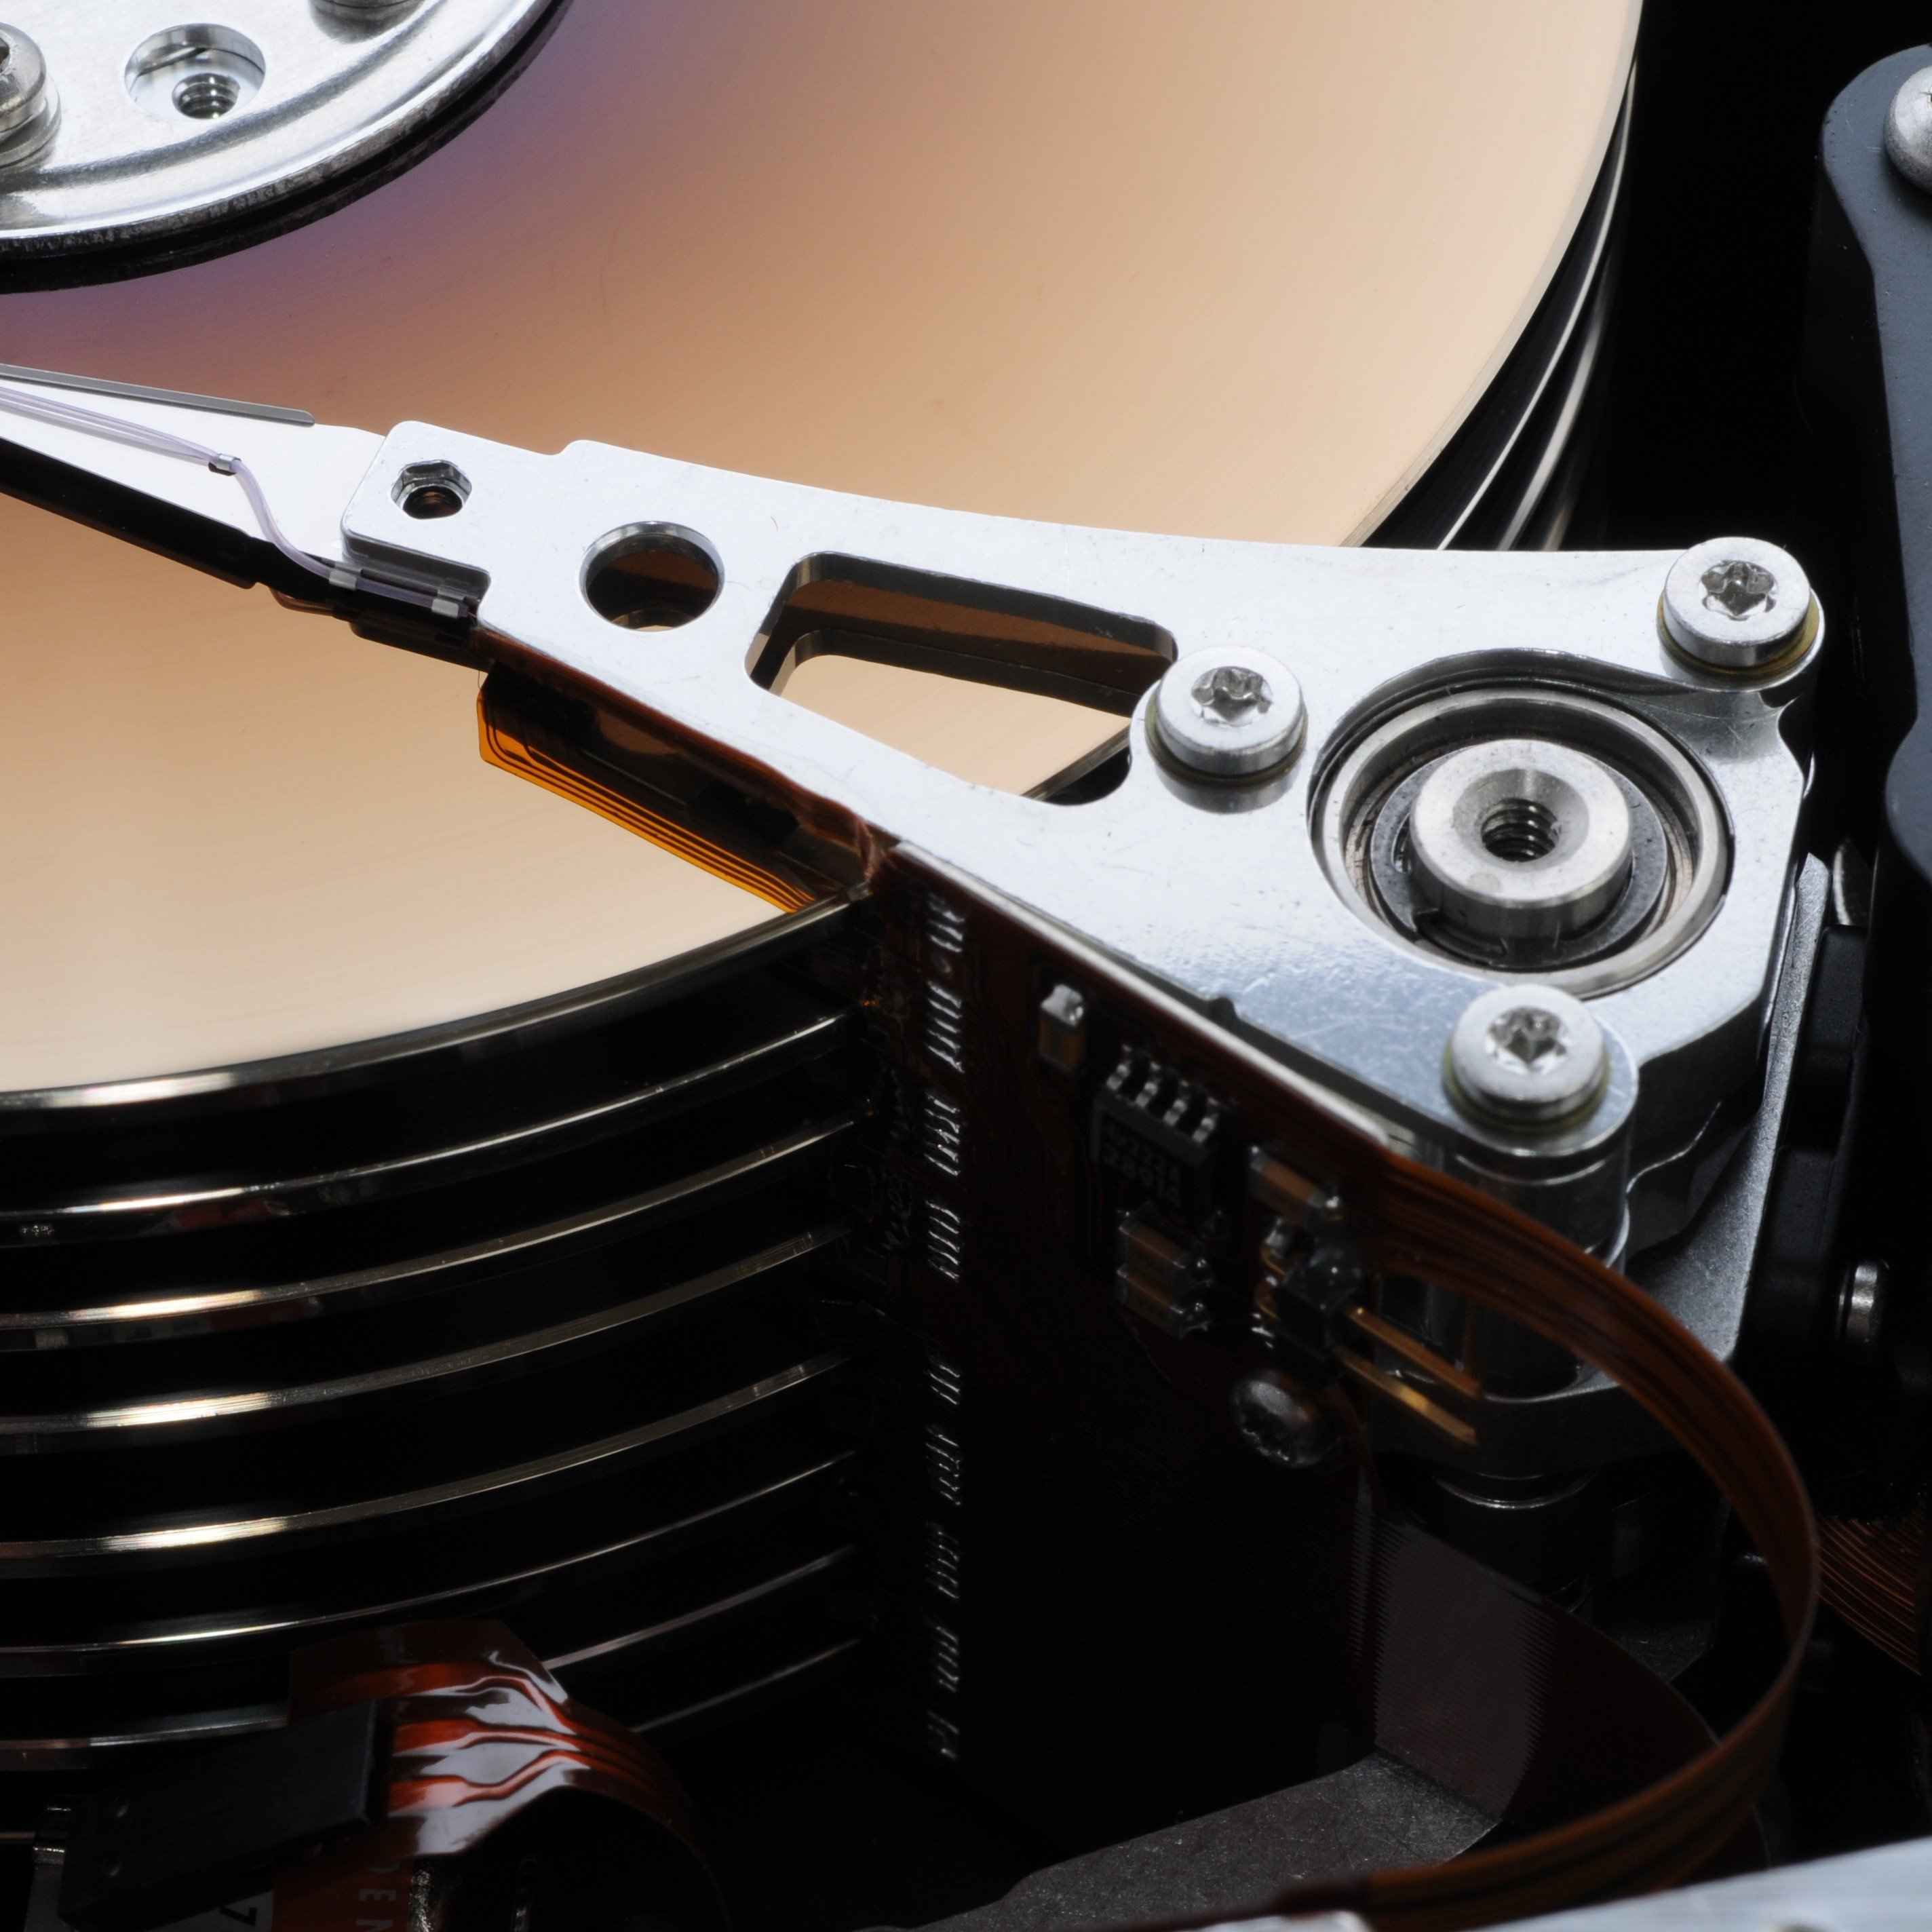
Seagate makes mass-capacity hard drives, and data-center customers took 90% of the capacity it shipped last quarter. AI-driven storage demand drove fiscal Q1 2027 revenue up 61.0% year over year. Melius Research holds the Street-high target of $1,600, which implies 139.6% upside. When the fundamentals keep accelerating while the stock keeps falling, investors need to figure out which side is wrong.
Record Earnings Could Not Stop a Storage Stock Exodus
Seagate is falling mainly because investors no longer trust that AI infrastructure spending will last. Shares have dropped 27.16% in the past month and sit 41.6% below the 52-week high of $1,143.27. A drawdown of more than 30% from the peak is a violent move for a company that is still beating estimates.
The damage hit the whole group. Seagate, Western Digital (NASDAQ:WDC) and other storage names led the market in the first half, then slid into the S&P 500’s bottom 10% as investors started wondering debt-funded AI buildouts (per Bloomberg reporting). One major bank cited “growing uncertainty around competition and AI funding” even as hard drive fundamentals got stronger.
The quarterly report did little to turn sentiment around, according to Barron’s. Non-GAAP EPS of $7.68 beat the $7.40 estimate, and revenue of $4.23B exceeded expectations of $4.14B. The size of the beat narrowed, though. The EPS surprise was 3.74%, down from 12.11% the quarter before.
Wall Street Says the Hard Drive Upcycle Has Years Left
Analysts remain overwhelmingly bullish. Here is how they rate the stock:
- Strong Buy: 4
- Buy: 18
- Hold: 2
- Strong Sell: 1
Recent revisions point higher. Fiscal 2027 EPS estimates average $36.6633, up from $28.5848 90 days ago, with zero down revisions in the past 30 days. That same bank raised its Seagate target during the selloff and said it would remain “aggressive buyers”. Melius’s thesis rests on hyperscale AI storage demand, pricing power from HAMR technology, and free cash flow growth backed by supply discipline (per its initiation).
Management’s guidance supports that view. For the December quarter, Seagate guided to revenue of $4.80B and EPS of $9.20, well above the prior consensus of $8.5389. Most nearline supply is “allocated under long-term supply agreements through calendar 2028”. On top of that, Microsoft (NASDAQ:MSFT) qualified a Seagate and Broadcom (NASDAQ:AVGO) solution built on HAMR-based Mozaic drives.
Analysts are watching three milestones: Mozaic 5 qualification shipments “towards the end of calendar 2027”, a net cash position by the end of calendar 2026, and larger buybacks starting in calendar 2027. One caution: fiscal 2028 EPS estimates range from $41.50 to $80.10. That spread shows deep disagreement about how long the cycle runs.
Western Digital Sank Alongside Seagate While NetApp Rallied
The two hard drive makers fell together. The more software-heavy name moved the other way.
Western Digital fell 16.62% over the past month to $380.88, against an average target of $610.04. That implies 60.2% upside. Analysts count 4 Strong Buys, 17 Buys and 5 Holds, although one major bank recently cut its target. Its upside is close to Seagate’s but slightly smaller.
NetApp (NASDAQ:NTAP) rose 13.39% over the past month to $227.58, which is 7.0% above its $211.69 average target. Analysts are lukewarm, with 12 Holds against 8 combined Buy ratings.
Seagate offers the biggest expected gain among analysts, and it also fell the hardest. Price targets are estimates that can change. Still, the gap points to an HDD-specific discount across the hard drive group.
Seagate Still Trounces the S&P 500 Despite the Plunge
At $667.85, Seagate could rise 63.4% to reach the $1,091.58 consensus target set by 25 analysts. It trades at about 18 times forward earnings, compared with a trailing multiple of 46.
The stock is down 27.16% over one month and still up 143.32% year to date. The S&P 500 is down 0.22% over the past month and up 12.87% year to date. A beta of 2.081 means swings like this come with having the stock.
Seagate’s Cash Machine Outweighs the AI Funding Scare
The bull case holds if hyperscalers keep honoring supply agreements through 2028 and the Mozaic 4 ramp delivers the December-quarter guidance. That combination supports the mid-50% operating margins management expects and a path back toward the consensus target. The bull case weakens if AI capital budgets narrowed, spot pricing cools, or competitors add capacity faster than expected. Any of those would turn today’s earnings peak into a cyclical high, which is the risk the selloff reflects.
The company is producing record free cash flow of $1.48B a quarter and guiding sequential growth, and that contrasts with a forward multiple near 18. Anyone following the stock should keep an eye on hyperscaler capex commentary, because that will decide whether the gap closes.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.