Elizabeth Warren Wants to Break Up UnitedHealth, and One Day Later a Nonprofit Called It Undervalued
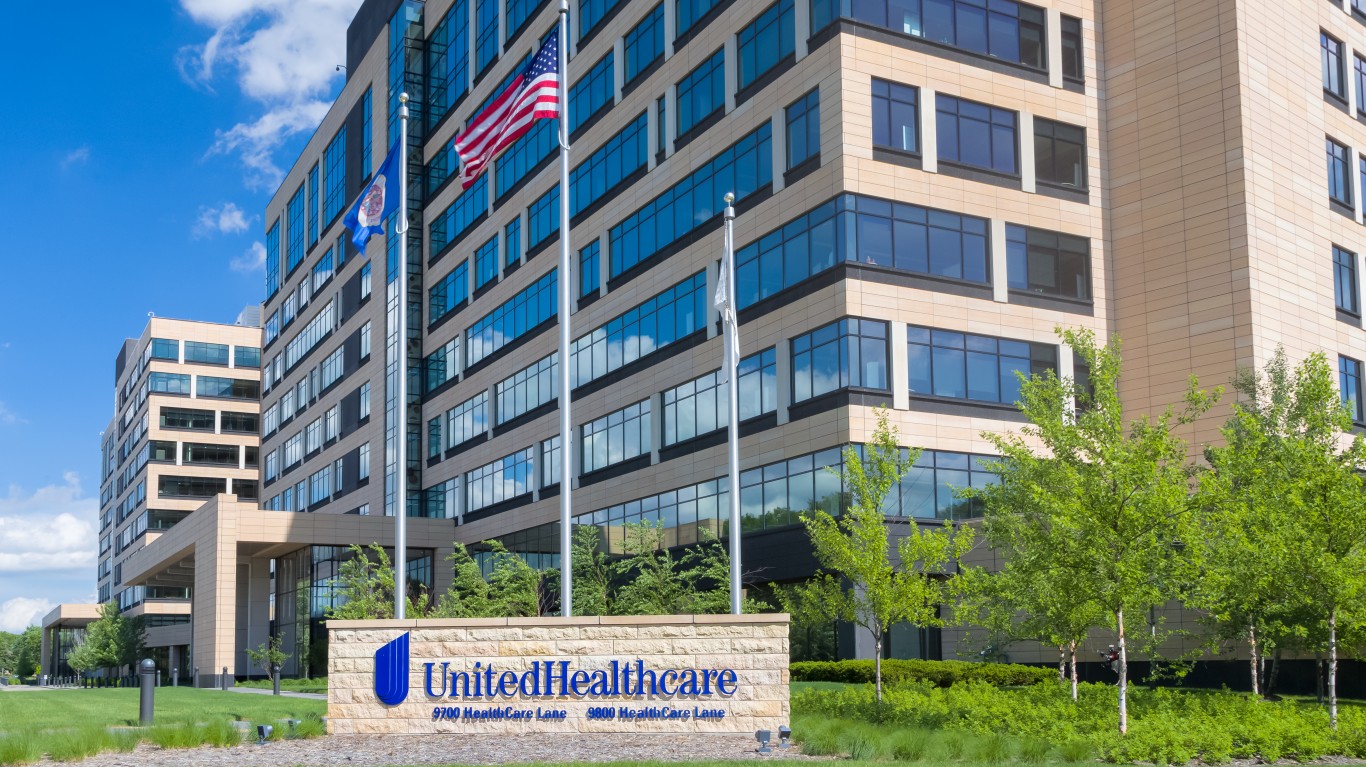
Elizabeth Warren is pushing to dismantle UnitedHealth Group just as a nonprofit investor education group moves in the opposite direction, naming the embattled insurer its top undervalued pick for early 2027. The timing raises a question every UNH shareholder needs…

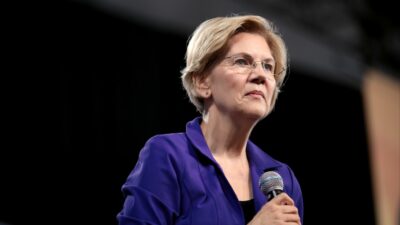
Senator Elizabeth Warren opened November by targeting UnitedHealth Group (NYSE:UNH | UNH Price Prediction) again. In a Sunday post on X, she went after the company’s purchase of Amedisys:
“Now Trump’s DOJ let them buy home health and hospice giant Amedisys for $3.3 BILLION”
She argued that the deal hands the company “MORE power to raise costs and deny care” and ended with a demand: “We need to break up Big Medicine.”
That framing is Warren’s own. Benzinga reported that the Justice Department sued to block the deal in November 2024, reached a proposed settlement in August 2025, and won court approval in December 2025. The settlement required the sale of 164 home health and hospice locations in 19 states.
Nonprofit Puts UnitedHealth in Front of Members Right Now
On November 2, 2026, BetterInvesting named UnitedHealth its “Undervalued Stock” for the January February 2027 issue of its magazine, with Amazon.com (NASDAQ:AMZN) as its “Stock to Study.” The BetterInvesting release makes no mention of Warren. It says the picks are:
“for the informational and educational uses of investors” and “are not to be considered as endorsed or recommended for purchase by NAIC/BetterInvesting.”
The pick lands with the stock in an awkward spot. Shares traded at $399.90 this afternoon, down 1.74% on the day and 4.35% over the week. They are still up 23.51% this year but down 4.92% over five years.

Earnings Rebound Drives the Valuation Case
Third-quarter adjusted EPS came in at $4.69, ahead of the $4.15 estimate. The medical care ratio improved to 88.4% from 89.9%, a figure that includes $610M of favorable reserve development. Management raised 2026 adjusted EPS guidance to at least $20.50, which puts the stock at about 20x this year’s earnings. The CFO also pointed past 2026:

“We would offer that current analyst consensus for 2027 may understate the opportunity ahead, and we see the lower end of our long-term 13%-16% growth rate as a more reasonable starting point.”
Integration Sits at the Center of the Breakup Fight
Warren’s target is the same structure management says drives its results. Chief executive Stephen Hemsley said the company serves healthcare “as one enterprise and one leadership team.” An Optum executive put it more bluntly: “Integrated value-based care means just that: integrated.” Optum Health operating earnings rose to $735M from $41M, and more than 50% of Optum Rx membership now comes from outside UnitedHealthcare.
The peers show why diversification matters. Humana (NYSE:HUM), the Medicare pure-play, posted a second-quarter insurance benefit ratio of 91.2%. Elevance Health (NYSE:ELV) reported a 89.7% benefit expense ratio and a Health Benefits operating margin of just 2.1%. UnitedHealth’s insurance business is also shrinking: Medicare Advantage membership has fallen by 935,000 since year-end 2025.
Pending Legislation Investors Need to Track Now
Warren co-sponsored the Patients Before Monopolies Act (S. 4509) with Senator Josh Hawley. The bill would bar PBMs and pharmacies from common ownership and force divestitures within a year. UnitedHealth’s filings already flag “DOJ legal actions concerning participation in the Medicare program” every quarter. The company has also committed to passing through 100% of drug rebates by January 1, 2028. Investors should keep an eye on whether either breakup bill gains support and whether fourth-quarter margins hold without help from reserve releases.

Data Sources
- BetterInvesting Magazine release: the Undervalued Stock and Stock to Study picks, the issue date, and the educational disclaimer.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)