SanDisk Is Back in the Spotlight. Here’s Where I See SNDK Stock Heading Next
SanDisk just posted six straight earnings beats and a 372% revenue surge, yet the stock sits 41% below its 52-week high. Whether that gap is a warning sign or a rare entry point depends on one risk that the bulls…

The AI trade is back, and memory stocks are moving with it. Shares of SanDisk (NASDAQ:SNDK | SNDK Price Prediction) rose 5.79% in today’s session, and Barron’s tied the rally to renewed AI enthusiasm ahead of Big Tech earnings.
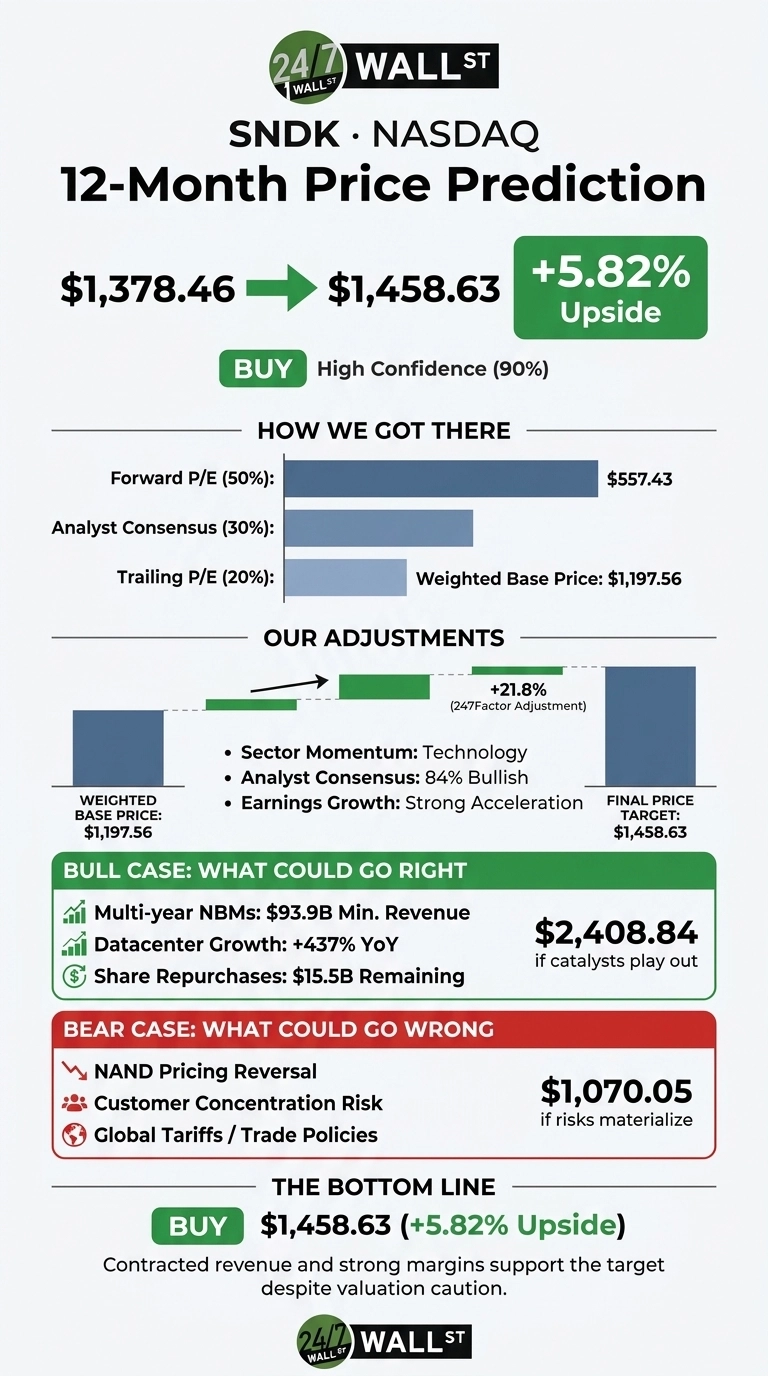
The 24/7 Wall St. price target for SanDisk is $1,458.63, compared with a current price of $1,378.46.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,378.46 |
| Price Target from 24/7 Wall St. | $1,458.63 |
| Upside | 5.82% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model rates SanDisk as a high-confidence buy, though the upside is moderate. SanDisk now earns software-like margins, and multi-year contracts give it far better visibility into future revenue than it had a year ago.
The model offsets that strength by assuming the market will keep valuing peak-cycle memory earnings cautiously.

A 22% Monthly Slide Despite Record Earnings
Shares are up 481.53% year to date and 1.1% over the past week. Over the past month, though, they fell 22.35%, which leaves the stock about 41% below its 52-week high of $2,354.39.
Fiscal Q4 revenue came in at $8,965 million, up 372% year over year. Non-GAAP EPS was $39.25, beating the $33.28 consensus and extending SanDisk’s run of earnings beats to six straight quarters.

Why Bulls See $2,400 Within Reach
SanDisk’s New Business Model agreements carry minimum expected revenue of $93.9 billion at floor pricing, and management expects gross margins on those deals of around 80%. Management also expects the NAND market to approach $500 billion in 2027.
Guidance for fiscal Q1 calls for EPS of $44 to $46, and the company has $15.5 billion left on its buyback authorization. The consensus analyst target of $2,143.83 is backed by 17 Buy and 4 Strong Buy ratings. The bull case reaches $2,408.84.

Pricing Risk Could Drag Shares Toward $1,070
Higher prices drove about two-thirds of SanDisk’s latest revenue growth, so a reversal in NAND pricing would hit earnings hard. Other risks include tariffs, SanDisk’s reliance on its Kioxia partnership and customer concentration.
GAAP results were also lifted by a one-time $807 million gain on SanDisk’s Nanya investment. Even so, the cleaner non-GAAP figures still beat estimates comfortably. Our bear case points to $1,070.05.
How SanDisk Compares to Micron and Western Digital
Micron Technology (NASDAQ:MU) is SanDisk’s most direct NAND competitor. Its forward P/E of 5 is about in line with SanDisk, though it carries a lower EV/EBITDA.
Western Digital (NASDAQ:WDC), SanDisk’s former parent, guided for 66% to 72% revenue growth next quarter. Its forward P/E of 17 shows what investors will pay for storage earnings they see as more durable. Measured against these two peers, our target looks reasonable.
| Company | Forward P/E | EV/EBITDA |
|---|---|---|
| SanDisk | 5x | 13x |
| Micron | 5x | 9x |
| Western Digital | 17x | 11x |
What Could Push SanDisk Toward Its Price Target
The 24/7 Wall St. price target of $1,458.63 supports a buy rating at 90% confidence. Contracted revenue is what tips the balance in SanDisk’s favor.
Upside increases if NBM volumes keep growing and margins hold near 80%. Downside risk grows if NAND prices start to fall. At today’s price, our model sees the reward outweighing the risk.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,402.45 |
| 2027 | $1,476.77 |
| 2028 | $1,519.93 |
| 2029 | $1,651.96 |
| 2030 | $1,690.13 |
SanDisk needs to keep executing on its current strategy for these projections to hold.
The rate of AI inference demand or a reversal in NAND pricing could drive large moves in both directions. The same AI expansion driving NAND demand is lifting the power, cooling, and networking suppliers behind it, which we covered in a free report on seven non-chip AI winners here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.