Here’s Why You Buy Amazon Even As It Spends More on AI Than It Generates From Operations
Amazon just posted its highest ever operating margin while burning through more cash than its operations generate, and that contradiction sits at the heart of one of the most important investment decisions in tech right now.

Amazon (NASDAQ:AMZN | AMZN Price Prediction) is a Buy at $245.63, even though its AI buildout currently uses up more cash than its operations bring in. It just posted its highest ever operating margin while running a trailing free cash outflow of $42.4 billion. Investors now have to decide whether that spending is building a moat or digging a hole.
Amazon runs AWS, the cloud and AI infrastructure leader, alongside its e-commerce, advertising and subscription businesses. Third-quarter revenue rose 12.1% to $201.94 billion. Capex of $77.26 billion far topped operating cash flow of $42.42 billion. Management repeated about $220 billion in 2026 cash capex and expects to spend meaningfully more in 2027 (all of that data-center spend has to be powered, cooled and networked, and that is the whole basis of our free report on seven AI infrastructure suppliers that aren’t chipmakers: grab it here).
AWS Acceleration Turns Capex Into Contracted Growth
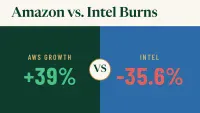
AWS revenue climbed 39% to $45.98 billion, its sixth consecutive quarter of acceleration. Its backlog hit $578 billion and is growing at triple digits. CEO Andy Jassy projects AWS growth above 40% in each of 2027 and 2028 and says customers take in capacity “almost as fast as we install it.”
Profits are growing with the spending. Operating income rose 61.2% to $28.08 billion, and AWS posted a 38.7% operating margin. Fourth-quarter guidance calls for $28.5 billion to $33.5 billion in operating income, compared with $25.0 billion a year ago. At a forward P/E of 22, investors pay a modest multiple for that growth. Barron’s reports that Wall Street is coming back around on the stock.
Cash Burn and Rising Debt Could Pressure Shares Further
The bears’ main exhibit is the balance sheet. Third-quarter financing inflows totaled $48.94 billion, and quarterly interest expense rose to $1.691 billion from $538 million a year earlier. Price-to-free-cash-flow sits near 345, and capex will climb again in 2027.
Execution was uneven as well. GAAP EPS of $1.89 missed the $1.96 consensus, and Online Stores grew only 2%. Management admits AI margins trail core AWS margins. Memory chip supply and energy prices add cost risk on top of that.
Patience Makes Sense Until Free Cash Flow Turns
Shares trade below their 50-day moving average of $254.28 and the 52-week high of $287.20, so the market is still waiting for proof. The business is too strong to justify a Sell. Negative free cash flow, though, makes high conviction hard to reach. Fourth-quarter results, the 2027 capex figure and Trainium’s planned availability outside AWS late in 2027 will show whether returns arrive on schedule.
Analysts See 33% Upside While Shares Lag the S&P 500
The average analyst target of $327.70 implies 33.4% upside from current levels. Coverage from 60 analysts breaks down as follows:
- Strong Buy: 16
- Buy: 42
- Hold: 2
- Sell or Strong Sell: 0
Shares are up 6.42% year to date, while the S&P 500 is up 10.3%. Over the past year Amazon gained 0.58%, compared with 10.28% for the index. Price targets are estimates, so treat them as one data point among several.
Amazon Earns a Buy Because the Backlog Covers the Bill
At $245.63, Amazon is a Buy. Here is why. The $578 billion backlog ties today’s capex to revenue customers have already committed. Jassy points to visibility into capacity needs through 2027, 2028 and part of 2029, and he says simply, “We can fund this plan.”
The path higher runs through 2027. Suppose AWS delivers 40%-plus growth and margins hold near current levels. In that case, operating income should outpace rising depreciation, and free cash flow should recover once spending levels off. Management also expects advertising growth to return to the high teens in the fourth quarter.
The entry price helps the risk/reward. After a year of lagging the index, much of the cash-burn worry already looks priced in. Meanwhile, a forward multiple of 22 asks little of a company growing operating income by more than 60%.
The argument weakens if AWS growth slows in 2027 while capex keeps rising, or if a greater AI mix squeezes AWS margins sharply. Amazon is spending more than its operations generate because customers have already contracted for what it is building, and at $245.63 investors can own that backlog at a steep discount to Wall Street’s targets.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.