Why Microsoft Was Rewarded for Spending Less on AI
Wall Street has drawn a sharp line between hyperscalers that fund AI expansion with their own cash and those that borrow or sell stock to pay for it, and the gap in stock performance tells the whole story.

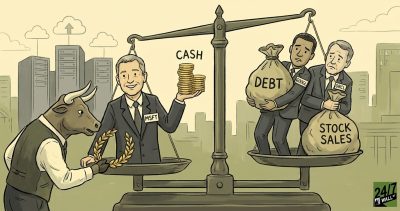
Wall Street’s take on the latest hyperscaler earnings is that investors now reward discipline on artificial intelligence (AI) spending and punish companies that borrow or sell stock to pay for it. On Mad Money, Jim Cramer said, “The only hyperscaler that did dial back its CapEx plans, Microsoft, saw the best reaction from the market for doing so. It didn’t go up, of course, but it went down the least.”
Capex, short for capital expenditures, is the money a company spends on long-lived assets such as data centers, chips, and power equipment. For retirement savers who own megacap tech, the central question is whether that spending pays for itself or drains cash.
A Small Pullback Still Earned a Premium
The cut was small. On Halftime Report, Jim Lebenthal called the decrease “very slight” and “basically based on supply chain.” Microsoft (NASDAQ:MSFT | MSFT Price Prediction) CFO Amy Hood said fiscal first-quarter capex reached $45.2 billion because some third-party capacity deliveries slipped. She guided full-calendar-year spending to approximately $170 billion, with second-quarter capex expected to exceed $50 billion. Investors rewarded a reduction that came mostly from timing.
Three Data Points Behind the Smart Money Call
1. Microsoft pays for its expansion with its own cash.
Operating cash flow rose 29% to $58 billion, and free cash flow came to $18.6 billion. Azure revenue grew 48%, and commercial remaining performance obligations, meaning contracted future revenue, rose 73% to $677 billion. Hood said, “We’re feeling good that we’re free cash flow positive.”
2. Peers are burning cash and raising outside money.
Alphabet (NASDAQ:GOOGL) posted free cash flow of negative $9.07 billion on $51.36 billion of capex and raised $28.7 billion in notes plus $12.4 billion through stock sales. Oracle (NYSE:ORCL) reported free cash flow of negative $5.40 billion and filed to sell new stock and bonds to finance its AI expansion. Discussing Oracle, Cramer said the market has adopted a stance “skeptical of major capital spending plans, especially if a company has to issue stock or new debt to pay for them.” Issuing new shares reduces each existing owner’s slice of future profits. Borrowing adds fixed costs: Oracle’s interest expense rose 55% to $1.4 billion.
3. Hedge fund positioning fell behind the shift.
As of June 30, Microsoft had six buyers and nine sellers among tracked funds. Amazon (NASDAQ:AMZN) had 15 buyers and seven sellers. Those filings predate this earnings season, so the positioning may have since shifted.
Prices Lag the Discipline Story
Over the past week, Microsoft shares fell 4.7% to $507.12. Alphabet dropped 12.1%, and Oracle lost 6.3%. Oracle is down 39.1% year to date. Amazon gained 8.5% as Wall Street warmed back up to the stock. Microsoft trades at a trailing P/E of 26, while Alphabet trades at 15.
The bull case for heavy spending still has supporters. Lebenthal said Alphabet and Amazon are “not backing off on the capex” and called those plans “the biggest positive of all.” On Fast Money, Evercore ISI’s Julian Emanuel said a reduction “might be good for those stocks” but added that “the GDP growth attributable to AI is so significant that you are likely to have a knock-on effect that causes growth economy-wide to slow more than the market would be comfortable with.” William Blair’s Tim Mulrooney said that in a worst-case scenario, about 9% of planned AI capacity is at risk from governors who favor data center moratoriums, and he expects much of it to move if needed. (All that expansion still has to be powered, cooled, and networked by somebody, which is the whole point of the seven suppliers we pulled into a free AI infrastructure report.)
Cash-Funded Growth Wins, So Track Two Signals
Microsoft is growing Azure at a near-50% pace and still producing free cash, while Alphabet and Oracle are tapping debt and equity markets. That funding gap explains why investors now treat capex efficiency as the deciding metric. Microsoft’s weaker one-week performance compared with Amazon shows that the reward has its limits.
Two things to watch next:
- Whether Microsoft’s spending ramp holds Azure growth near its guided 49% to 50% range
- How each hyperscaler pays for its next round of data centers
Spending funded by operating cash has earned a premium. Spending funded by new shares and bonds has been marked down.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.