52 Analysts, Zero Sells: What Microsoft’s Price Target Really Implies
Fifty-two analysts cover Microsoft and not one recommends selling, yet the stock has gone nowhere for a year while Azure just crossed a historic revenue threshold. Something in that gap between Wall Street conviction and share price stagnation does not…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
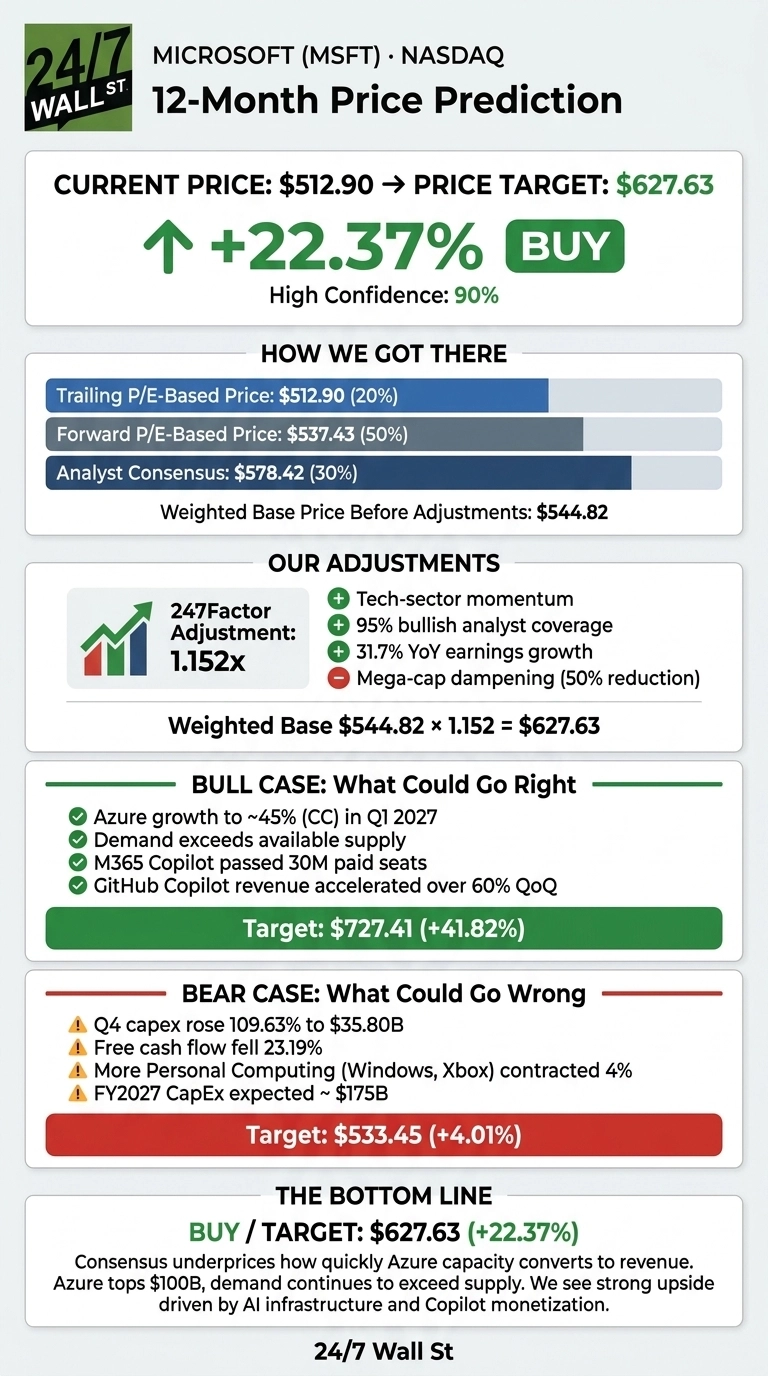
The 24/7 Wall St. price target for Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is $627.63 over the next 12 months. The target stands 22.37% above the current price of $512.90. Our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $512.90 |
| Price Target from 24/7 Wall St. | $627.63 |
| Upside/Downside | 22.37% |
| Recommendation | BUY |
| Confidence Level | 90% |

Wall Street agrees. Microsoft has 14 Strong Buy, 38 Buy and 3 Hold ratings, with zero Sells. The consensus target is $578.42, implying about 12.8% upside. Our target stands above the Street because consensus is underpricing how quickly Azure capacity will convert to revenue.

Azure Tops $100 Billion While Shares Tread Water
The stock is up 2.56% over the past week and 6.83% year to date, but about flat for the full year at -0.06%. The 52-week range runs from $348.54 to $549.20.
The business grew much faster than the stock. Microsoft reported fiscal Q4 2026 results on July 29. Revenue came in at $90.01 billion, up 17.75%, beating the $87.63 billion estimate. EPS of $4.74 beat the $4.24 estimate. Azure grew 43% and passed $100 billion in annual revenue. Commercial backlog rose 84% to $678 billion.

Why Bulls See $727 Within Reach
In our bull case, the stock hits $727.41. Supply is the main driver. Management guided to Azure growth of about 45% in constant currency for fiscal Q1 2027. CFO Amy Hood said “demand continues to exceed available supply.” Each new gigawatt of capacity sells almost as soon as it comes online.

AI products are making real money. Microsoft 365 Copilot has passed 30 million paid seats, with net additions more than doubling from the prior quarter. GitHub Copilot revenue grew over 60% quarter over quarter.
Capex and Free Cash Flow Are the Pressure Points
Our bear case comes to at $533.45. Q4 capital spending rose 109.63% to $35.80 billion, and free cash flow fell 23.19%. Management expects fiscal 2027 capex of about $175 billion. More Personal Computing, which includes Windows and Xbox, contracted 4%. Excluding OpenAI, backlog grew a more modest 25%.
Operating cash flow rose 30% to $55.44 billion, and Microsoft expects free cash flow to stay positive. Hood said spending is flexible: “If the demand environment changes, you just slow down what is, in fact, the largest component.”
Microsoft Pairs Growth With Positive Free Cash Flow, Unlike Amazon and Alphabet
Amazon (NASDAQ:AMZN) runs AWS, Azure’s closest rival. AWS grew 37%, slower than Azure, yet Amazon trades at 35x trailing earnings versus Microsoft’s 28x. Amazon’s trailing free cash flow was negative $7.6 billion.
Alphabet (NASDAQ:GOOGL) trades at 15x earnings, and Google Cloud grew 82%. A $99.03 billion gain on equity securities inflated those earnings. Alphabet had negative Q2 free cash flow of $5.855 billion and suspended its buyback.
| Company | Trailing P/E | Cloud Growth |
|---|---|---|
| Microsoft | 28 | 43% (Azure) |
| Amazon | 35 | 37% (AWS) |
| Alphabet | 15 | 82% (Google Cloud) |
Against these peers, our target looks reasonable. Microsoft has premium-quality cash flow at a valuation between the two.
Microsoft Price Prediction 2026-2030
I stand by our 24/7 Wall St. price target of $627.63, a buy rating and 90% confidence. Capacity selling as soon as it arrives tips the scale. My confidence would rise if Azure delivers the guided acceleration and Copilot seat additions keep compounding.
I would get more conservative if capex keeps growing while free cash flow contracted for several more quarters. For now, the evidence supports the bull side.
Our model projects where Microsoft could trade if current growth and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $542.26 |
| 2027 | $629.19 |
| 2028 | $727.64 |
| 2029 | $820.67 |
| 2030 | $895.81 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.