BYD Does Many Things Better Than Tesla But It Doesn’t Matter
BYD outguns Tesla on vehicles, pricing, and battery technology, yet one structural reality keeps American investors from benefiting. Understanding that gap changes how you should think about both stocks.

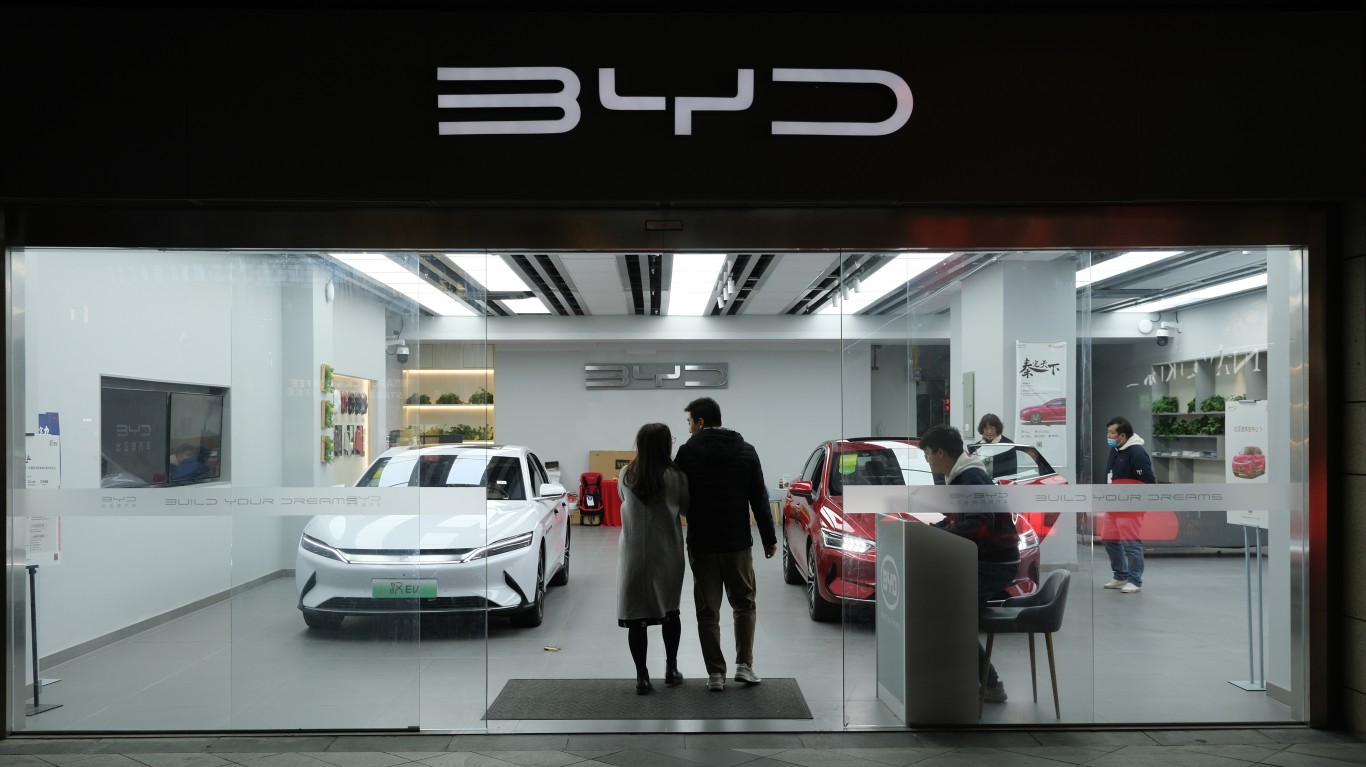
BYD (OTC:BYDDF) and Tesla (NASDAQ:TSLA | TSLA Price Prediction) both reported third-quarter results in late October. BYD grew profit as overseas shipments more than doubled. Tesla delivered 486,532 vehicles and kept pouring cash into robotaxis and robots. One company is winning the global car business. The other is selling a different future, and Wall Street is paying for it.
BYD Wins on Cars While Tesla Wins on Software
BYD’s quarter showed an automaker built for global scale. Profit rose year over year but fell short of analyst expectations, and inventory climbed sharply. BYD blamed the inventory build mainly on growth in its overseas automobile business. With demand at home soft, exports now carry the load. BYD also doubled its market share in Brazil, with a new plant eyed. Its formula of cheap EVs, plug-in hybrids, and in-house Blade batteries sells well abroad.
Tesla’s revenue of $28.05B was essentially flat YoY, so the car business is treading water. Adjusted EPS of $0.48 beat the $0.4511 estimate. Even so, operating income fell 55.79% to $718M as R&D rose to $2.76B from $1.63B. Management chose that squeeze on purpose. Elon Musk told analysts, “The biggest driver for demand is full self-driving.” Active FSD subscriptions reached 1.74M, up from 1.04M, so buyers seem to agree.
| Business Driver | BYD | Tesla |
|---|---|---|
| Growth Engine | Overseas exports | FSD, Robotaxi, energy storage |
| Product Range | Budget EVs, hybrids, Yangwang luxury | Model 3, Model Y, Cybertruck, Cybercab, Semi |
| Pressure Point | Rising inventory | R&D squeezing margins |
A Better Automaker That Never Reaches American Driveways
On product range, pricing, battery integration, and hybrids, you can argue BYD beats Tesla. It sells everything from budget hatchbacks to luxury models, and it builds factories close to new customers. U.S. buyers will never see any of it, because BYD automobiles can’t be imported into the U.S. The shares also trade over the counter, which makes them harder to buy and less liquid for many Americans.
Tesla’s valuation shows what the market rewards. Its P/E sits around 415, a multiple that depends on Cybercab, Optimus, and energy. Storage deployments reached 13.7 gigawatt-hours, and Musk said Tesla is “almost sold out of all Megapacks for 2027.” BYD shares have dropped 24.31% year to date, while Tesla is down 11.39%. Barron’s put it simply: BYD’s massive EV exports aren’t helping the stock.
Dallas Robotaxis and BYD Inventory Set Up the Next Test
I will be following Tesla’s planned Cybercab launch in Dallas. Management expects Robotaxi revenue to become noticeable in Q2 of next year, and I want to see that happen. With BYD, track whether the overseas inventory turns into sales and whether Brazil can make up for weakness in China.
Why I Still Lean Toward Tesla Despite BYD’s Edge
If I judged on cars alone, I would pick BYD. It builds cheaper vehicles, makes its own batteries, and is growing faster abroad. For an American shareholder, though, that growth happens in markets you rarely see, and the tariff walls around it are high. Tesla’s car margins look thin, and I am skeptical of its robotaxi timelines. Still, I can track its catalysts closely from here. I would take another look at BYD once its inventory clears and U.S. investors can buy the shares more easily.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.