Forget The Short-Term Noise: This is Where Amazon Will Be in 2028
Amazon just posted its highest operating margin ever and AWS revenue surged 39%, yet the stock barely moved. There is a specific combination of factors that could push shares to a level most analysts have not priced in.

The stock fell anyway after Amazon (NASDAQ:AMZN | AMZN Price Prediction) just posted its highest operating margin ever, 13.9%.
Shares trade at $237.81 this morning, up only 5.62% year to date, even as AWS revenue grew 39% to $45.98B. I see an opening in that gap between the price and the business. Can Amazon reach $500 per share in 2028?

What’s Holding Amazon Back Right Now
The problem is spending. Amazon guided to about $220 billion of 2026 capex and expects to spend meaningfully more in 2027. Trailing free cash flow is an outflow of $42.4B. Q3 EPS of $1.89 missed the $1.96 consensus, and online stores grew just 2%. Coverage has zeroed in on soaring spending amid slowing online growth and a lower Christmas sales forecast.
The stock’s recent performance reflects it. Shares are down 2.63% over the past week, 1.17% over the past month and 2.45% today. With a beta of 1.456, Amazon swings harder than the market when sentiment turns.
Analysts See $332, but My Model Goes Further
Wall Street’s consensus target is $332.41, backed by 16 Strong Buys, 43 Buys, 2 Holds and 0 Sells. Our model’s base case is $377.20, meaning 54.72% upside from Thursday’s close, with a one-year range of $316.96 to $425.16. Model confidence is high.

I think the Street is too conservative. Analysts are 97% bullish, earnings growth adds 0.03 to our factor, and the 2027 EPS estimate has rose from $10.0087 to $10.5588 in 90 days. Price targets are trailing those revisions.
Here’s What It Takes for Amazon to Reach $500
Reaching $500 from today’s price of $237.81 would require a gain of 110.3%.
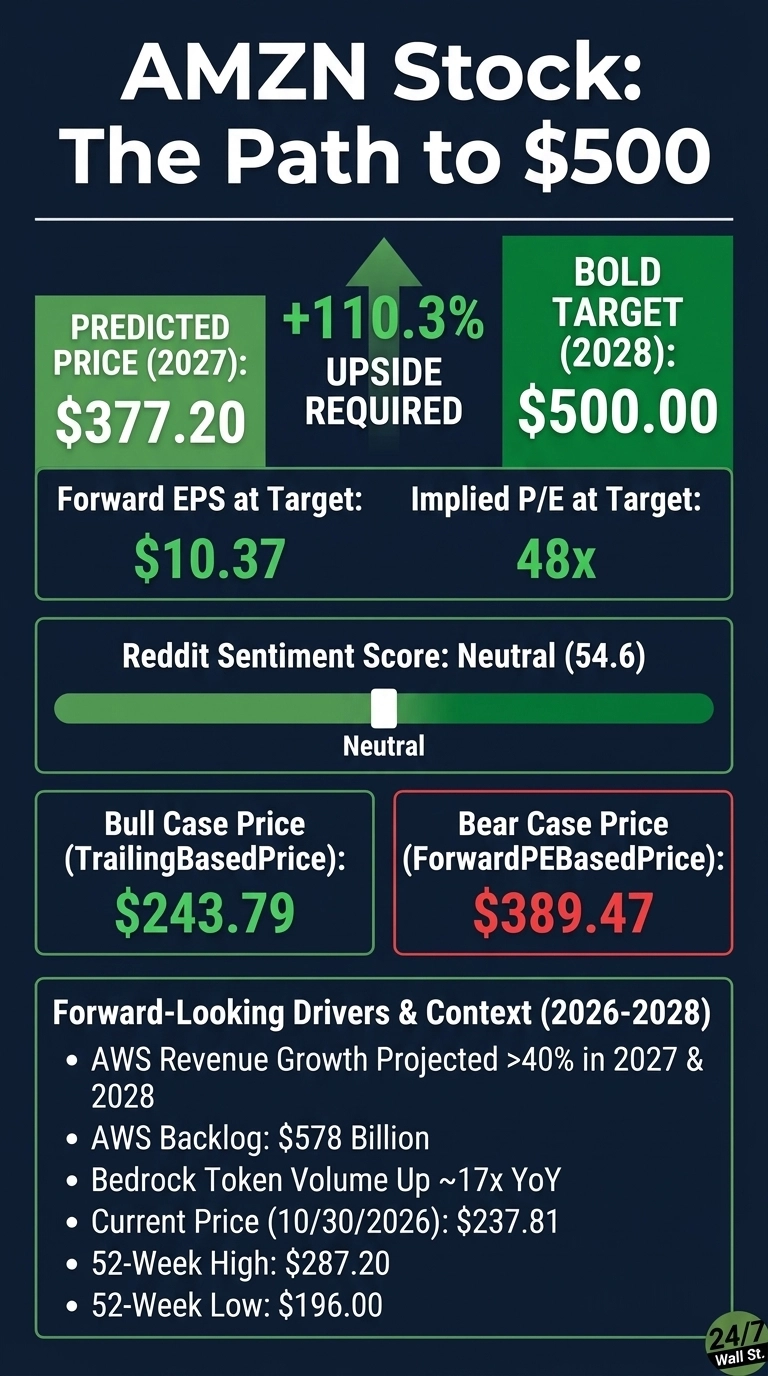
With forward EPS of $10.3697, a $500 target would carry a forward P/E of 48x. The base case already meaning 20x, so the bold target needs roughly 29x of additional multiple expansion on today’s earnings.

Earnings growth closes that gap. The 1.099 adjustment factor is driven mostly by analyst consensus, and management projects AWS growth above 40% in both 2027 and 2028. If earnings keep pace, $500 looks far cheaper on 2028 profits than 48x does today.
Key drivers include a $578 billion AWS backlog, Bedrock token volume up nearly 17 times, and external Trainium sales starting in late 2027. Andy Jassy put it simply: “There has never been a trillion dollar revenue business, and we may have two of them in the next 5 to 10 years.” Our own five-year base path reaches $518.19 by October 2028.
The primary risk is that capex rises faster than AWS profits can absorb it.
Where Amazon Trades Today vs. Its Earnings Power
Amazon currently trades at 23x forward earnings. That is a modest multiple for a company with cloud revenue growing near 40%.
Shares sit between a 52-week low of $196 and a high of $287.20. Over 10 years, the stock has returned 517.33%. A low starting multiple leaves room for the stock to run.
$500 Is a Stretch, but Here’s Why It’s Possible
Hitting $500 requires a 110.3% gain. My verdict: a stretch, but a credible one. Three things need to go right. AWS must deliver its 40%-plus growth, capex returns must show up in free cash flow, and retail margins must keep expanding. A sharp decline in enterprise AI spending would disrupt it.
Such strong returns are rare in any single year, and we’ve outlined the blueprint for how Amazon could reach $500 in 2028.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.