Applovin Bounces Back Following Strong Quarterly Results: This Wall Street Desk Says 120% Gains Still to Come
A second-quarter stumble wiped out more than half of AppLovin's value, yet analysts keep their Buy ratings even as they slash targets. One cheap forward multiple and a buyback surge raise the question of whether the market is overreacting.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
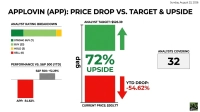
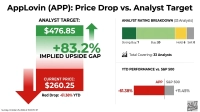
AppLovin (NASDAQ:APP | APP Price Prediction) now changes hands at $271.75. The consensus price target sits at $448.43, implying upside of 65.02%.
AppLovin runs an AI-driven advertising platform built on its AXON engine. It matches advertisers with mobile game players and, more and more, with consumer audiences. Its third-quarter report showed revenue of $2.18 billion, up 55.5% from a year ago. GAAP EPS came in at $4.30, beating the $4.0337 consensus.
Wells Fargo has the most aggressive active target at $600. It implies 120.79% upside. With even the consensus implying more than 40%, the bull case deserves a close look.
A Second-Quarter Miss Deepened a 59.67% Slide
The damage traces back to a second-quarter revenue miss. Revenue of $1.92B missed estimates by 0.94%, ending a long run of clean beats. Investors were already worried about mobile-game growth and competition. The stock went from $483.10 at the first-quarter report to $245 just before the latest one.
For the year, shares are down 59.67%, well past the 30% line for a violent selloff. A beta of 2.498 made every swing bigger. Most of the decline came from AppLovin’s own problems, since the S&P 500 rose over the same stretch.
Analysts Are Trimming Targets but Keeping Buy Ratings
Management summed up the turnaround on the call: “A quarter ago, we stood here answering questions about a miss. We told you what had happened, that it was fixed, and that the business was re-accelerating.” Gaming revenue grew nearly 50% as next-generation models began rolling out. Consumer advertiser spending grew at a triple-digit rate from a year ago.
The bull case rests on AXON spreading into e-commerce and other non-gaming ad spend. It also counts on 84% adjusted EBITDA margins paying for buybacks. The board added $3.2B to the repurchase authorization, bringing it to $3.6B. Fourth-quarter revenue guidance of $2.365B to $2.395B sits above the $2.247 billion consensus.
Of the 33 covering analysts, 7 rate it Strong Buy, 20 have it as a Buy and 6 rate it Hold. There are no Sells. Even so, targets keep falling. Wells Fargo cut from $860, UBS analyst Stephen Ju cut from $790 to $414.00, and Deutsche Bank, Scotiabank and KeyBanc each lowered $775 models into the $500 to $515 range. The average 2027 EPS estimate has slipped to $19.6136 from $21.1644 90 days ago. Price targets are one input among many, and these ones are still moving lower.
Ad Tech Peers Split Between Steep Losses and Recovery
The peer group moved in different directions, so AppLovin’s slide was largely its own.
The Trade Desk (NASDAQ:TTD) is down 65.15% this year at $13.23. Its average target of $13.53 implies only 2.27% upside. 23 analysts rate it Hold and 8 rate it Sell or Strong Sell, after revenue grew just 3.03%.
Magnite (NASDAQ:MGNI) is up 40.42% this year at $22.79. Its average target of $29.67 implies 30.19% upside. It has 13 Buy or Strong Buy ratings against 2 Holds. That upside is solid, though smaller than AppLovin’s.
AppLovin shows the biggest upside potential among these stocks. It also pairs that upside with revenue growth of 55.5%.
AppLovin’s Rebound Barely Dents a 59.67% Annual Decline
At $271.75, AppLovin has 65.02% implied upside to the $448.43 average target from 33 analysts. The stock rose 10.69% in the latest session as results came out. It is up 4.53% over a week but down 3.62% over a month.
Year to date, AppLovin is down 59.67%. The S&P 500 is up 12.45%. The stock trades at a forward P/E of 11, a low multiple for a company growing revenue at 55.5%.
AppLovin’s Cash Machine Outweighs Shrinking Targets
Bulls get a boost if the new model rollout keeps advertisers spending and consumer revenue keeps growing. The bear case gains weight if gaming growth stalls again or if falling estimates turn out to be the start of a longer downtrend.
The path back to $448.43 runs through two more quarters of beats and a full model transition. Management calls it a “very early” transition and says “the headroom is real.” The bear case points to falling targets, rising stock-based compensation and a beta that punishes any slip.
My outlook is bullish. A forward multiple of 11 and an “opportunistically” increased buyback suggest the market is pricing in more damage than the latest numbers show. The $600 call is the outer edge. The consensus target looks reachable if the execution holds.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.