Salesforce Vs. ServiceNow: You Can Trust Both Following The Recent Drop
Both software giants promised agentic AI would fuel their next chapter, and investors answered with a sell-off. One company guards the data agents need, the other polices the agents themselves. Which bet has Wall Street underpricing?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
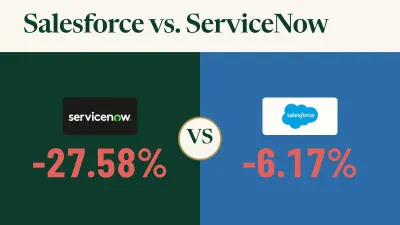
Salesforce (NYSE:CRM | CRM Price Prediction) and ServiceNow (NYSE:NOW) both reported recently and made the same pitch: agentic AI will power their next phase of growth. Investors have pushed back since. ServiceNow fell 27.58% over the past week, and Salesforce slipped 6.17%. The businesses below look stronger than either move suggests.
Agentforce Lifts Salesforce While One Guide Spooks ServiceNow Holders
Salesforce posted Q2 revenue of $11.345B, up 10.8%. That pace is steady but modest. The AI layer is growing much faster. Combined Agentforce and Data 360 ARR reached nearly $3.9B, up over 210%, and 50% of Agentforce bookings came from customers buying more credits. That tells me customers keep using agents after they go live. Marc Benioff said “We’re seeing incredible demand for our AI and data products, with ARR about to cross $4 billion.”
ServiceNow grew subscription revenue 21% to $3.988B, which is faster than Salesforce. It also raised its 2026 AI net new ACV target for the second time this year, to $1.7B. Still, non-GAAP EPS of $1.00 came in below the $1.02 estimate, and the Q4 cRPO guide slowed to 18.5%. Management blamed early renewals and public-sector deals that run on customers’ own servers. That explanation sounds reasonable, but I want to see it confirmed.
| Business Driver | Salesforce | ServiceNow |
|---|---|---|
| Growth Engine | Agentforce and Data 360 | Super Intelligence Control Tower, EmployeeWorks |
| Headline AI Partner | ClaudeForce with Anthropic | Expanded OpenAI partnership |
| Pricing | Per user, per agent, consumption, results | Seat-based plus consumption |
| Forward P/E | 14 | 21 |
Data Keeper Versus Agent Governor
Salesforce argues that AI makes its customer data more valuable. Legora’s CFO put it simply: “the agent is only as good as the context that you give it.” With Headless 360, customers can work with Salesforce data inside Slack, ChatGPT, or Teams, so Salesforce gets paid whichever chat tool wins.
ServiceNow wants to manage every AI agent a company runs. AI Passport gives each agent a record of what it can access, which management called “the most capable kill switch available in the enterprise today.” Through its Action Fabric tool, work that starts in ChatGPT still runs, and earns money, inside ServiceNow.
Capital allocation separates the two companies. Salesforce’s $25B buyback cut diluted shares to 821M from 962M. ServiceNow’s acquisitions shrank its GAAP operating margin to 9.5% from 17%, a real cost of buying growth.
Premium Upgrades and Q4 Backlog Decide the Next Move
Salesforce’s push to move customers onto premium editions will be worth watching. Only 5% of sales and service users have upgraded, and those tiers cost 60% to 80% more. That leaves plenty of room to grow. For ServiceNow, keep an eye on whether Q4 cRPO meets the guide. Bill McDermott said the “true acceleration” arrives in 2027.
Why I Trust Both, for Different Reasons
On valuation metrics, Salesforce screens as the cheaper of the two. A forward P/E of 14 and a big buyback limit the downside. ServiceNow screens as the faster grower. A 98% renewal rate shows customers stick around, and the selloff lowers the price investors pay for that growth. I would change my view on ServiceNow if Q4 cRPO falls short of the guide, and on Salesforce if Agentforce refills slow down.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.