This Year’s Worst S&P 500 Stock Just Got a Huge Reprieve
AppLovin beat on every line and guided higher, yet its stock has crushed investors after earnings before. Two specific markers will show whether this after-hours surge becomes a real turnaround or another post-report reversal.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
AppLovin (NASDAQ:APP | APP Price Prediction), this year’s worst S&P 500 stock through Wednesday’s close, reported third-quarter results after the bell on November 4, 2026, that beat estimates. At 7:59 p.m. ET, shares traded at $333.80, up 22.83% after hours. That followed a 10.69% regular-session rise to $271.75.
After-hours trading is thin, and that price is not a close. If it held, the year-to-date loss would narrow to about 50.5% from 59.67%. That would put AppLovin ahead of Fair Isaac (NYSE:FICO), which was down 58.53% for the year and fell another 6.57% after hours.

Filed Results Topped Every Estimate
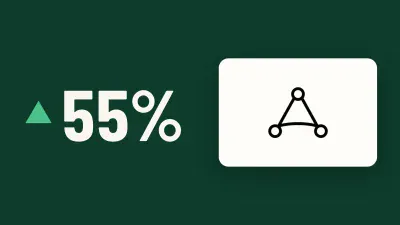
Revenue reached $2.185 billion, up 55% from $1.405 billion a year earlier and above the $2.07 billion consensus. Earnings per share of $4.30 beat the $4.03 estimate, although that GAAP figure includes $86.032 million of other income.
Net income rose 72% to $1.439 billion. Adjusted EBITDA, a profit measure that strips out interest, taxes, depreciation and stock pay, grew 59% to $1.842 billion at an 84% margin.
CFO Matt Stumpf said the largest digital ad platforms grew roughly 10% to the mid-20%s. He added that about 65% of revenue became free cash flow, which totaled $1.418 billion.
Guidance Carries More Weight Than the Beat
Fourth-quarter revenue guidance of $2.365 billion to $2.395 billion came in above the $2.25 billion consensus. Management also guided adjusted EBITDA to $1.995 billion to $2.025 billion, with margins of 84% to 85%. Stumpf said that means growth of about 43% to 44%.
CEO Adam Foroughi credited a partial launch of next-generation ad models and would not commit to a timetable for completing it. He said he believes the business can compound at roughly 30% a year over the long term, which is his belief and not company guidance.


Buybacks Show Conviction at a Cost
AppLovin bought back and withheld 4.1 million shares for $1.4 billion in the quarter. That works out to about $341 per share on average, which is more than the after-hours price. Stumpf said management stepped up purchases because it saw a gap between the stock price and the company’s intrinsic value.
The board added $3.2 billion, which brings the authorization to $3.6 billion. The $90 average Stumpf cited covers all 104 million shares bought for $9.4 billion since the program began, so it says nothing about how recent purchases have performed.
Post-Report Reversals Defined 2026
The stock’s worst days of 2026 came right after its own reports. It fell 19.68% to $366.91 on February 12, because a beat did not ease valuation concerns. It then fell 19.66% to $335.67 on August 6 after sales missed estimates.
Reported pressures included a 16.12% drop on February 4 after the startup CloudX made its AI agent tool for mobile game ads generally available. Short-seller reports and an SEC investigation into data collection, as it was described in February, were also cited. On October 30, the stock fell 10.4% to $228.50 with no company news. The after-hours price stands about 46% above that low but remains about 54.5% below the $733.60 peak close of December 22, 2025.
Two Markers That Will Test the Rebound
After the August miss, the question was whether growth could hold up. Guidance for about 43% to 44% growth with steady margins answers that question better than a single quarter’s beat would.
AI-native rivals and data-collection questions remain risks, and the stock has turned after reports before. Two markers will test whether the rebound holds: a regular-session close on November 5 below $271.75 would mean the after-hours gain did not hold. Fourth-quarter revenue below $2.365 billion would weaken the argument that growth is holding up.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.