The AI Boom Is Creating a New Set of Winners. These Stocks Stand Out
A sharp pullback has cooled valuations on three AI hardware names that just posted blowout quarters. Each one sits a round-number gain away from a new high, but supply bottlenecks and customer concentration could still derail the run.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Hyperscalers are spending heavily across every layer of the stack. That includes the server racks, the cables that link them and the custom chips inside (we featured seven suppliers riding that same expansion, from power to cooling to networking, in a free AI infrastructure report).
Three companies stand out as 2027 approaches. Each just reported huge growth, and a sharp drop in recent weeks has made their valuations look more reasonable. Here’s how each one could reach a round-number price target.
Dell Technologies Has a $95 Billion Backlog Behind a $500 Target
Dell Technologies (NYSE:DELL | DELL Price Prediction) is up 213.43% year-to-date, even after falling 30.51% over the past month. Jeff Clarke said on the earnings call, “Over the past 12 months, we have booked more than $130 billion in AI server orders.” Dell ended the quarter with a record $95B AI backlog. Non-GAAP EPS came in at $7.04, beating the $4.90 estimate. That makes four beats in a row.
Analysts now expect $28.2013 in fiscal 2028 EPS. Ninety days ago, they expected $19.4275. At $390.38, Dell trades at 14x that estimate. A move to $500 would be a 28% gain and lift the multiple to just 18x. That’s still below the S&P 500’s about 22x.

Credo Needs a 40% Gain to Reach $200
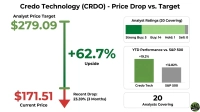
Credo (NASDAQ:CRDO) is down 0.6% year-to-date, but the business keeps speeding up. Revenue rose 114.7% to $479M, and EPS of $1.20 extended Credo’s beat streak to 8 consecutive quarters.
CEO Bill Brennan said, “What’s different today is that we’re adding optics as another major growth engine.” Credo expects more than $600 million in optical revenue in fiscal 2027.
Analysts project fiscal 2028 EPS of $9.7121, which is 54% above this year’s $6.3093. At $143.03, Credo trades at 15x that estimate. At $200, the multiple would be 21x.

Broadcom Expects to Double AI Revenue, Which Points to $400
Broadcom (NASDAQ:AVGO) is down 3.64% in 2026, even as AI chip revenue rose 221% to $16.70B. CEO Hock Tan said, “In 2027, we have secured the supply to again double AI revenue to approximately $115 billion. Our demand actually exceeds this outlook.” Broadcom has now beaten estimates for 9 consecutive quarters.
Analysts expect fiscal 2027 EPS of $19.4651, up 67% from this year’s estimate. At $331.68, Broadcom trades at 17x. At $400, a 21% gain, it would trade at 21x.

Catalysts That Could Unlock All Three Targets
- Rising estimates: Dell’s fiscal 2027 EPS estimate had 23 upward revisions and zero cuts over the past 30 days.
- Product cycles: Credo expects its first 1.6T DSP revenue later in fiscal 2027. Broadcom taped out Tomahawk 7, the first 200-terabit-per-second Ethernet switch.
- New AI labs as customers: Broadcom expects Anthropic to become its largest XPU customer in 2027. OpenAI’s Jalapeno chip is on track for a 1.3 gigawatt deployment.
Past Returns Show These Targets Are Within Reach
Dell has gained 688.29% over five years. Credo is up 1127.73% since early 2022, and Broadcom has returned 2375.7% over the past decade. Compared with those runs, the required gains are small.
Challenges remain. Dell called its supply bottleneck “DRAM, DRAM, DRAM.” Credo’s largest customer made up 33% of revenue. Broadcom’s fiscal 2027 estimate had 26 downward revisions over the past 30 days.
Bottom Line on $500, $200 and $400
All three companies have long beat streaks, earnings growing quickly and forward multiples near or below the market’s. These targets look achievable with steady AI spending and looser supply chains.
Expecting this level of returns every year is unrealistic, but this is how Dell, Credo and Broadcom could post outsized gains in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.