The AI Boom Is Giving Dell a New Growth Story
Dell's AI server backlog keeps shattering records, analysts keep raising targets, and the stock has already done things few expected. Here is the specific math behind whether shares can reach a level Wall Street still calls ambitious.

Dell Technologies (NYSE:DELL | DELL Price Prediction) has rebuilt itself around the AI factory. Some customer projects now require “upwards of 50 unique designs” to tune performance, power and cooling.
More than 6,500 customers now buy Dell AI Factory, and 3,300 of them arrived in the last three quarters. The stock has followed. Shares are up 360.32% year-to-date and 1,086.46% over five years. Let’s look at what Dell needs to do to hit $800 per share in 2027.

Wall Street Keeps Chasing Dell’s Earnings Higher
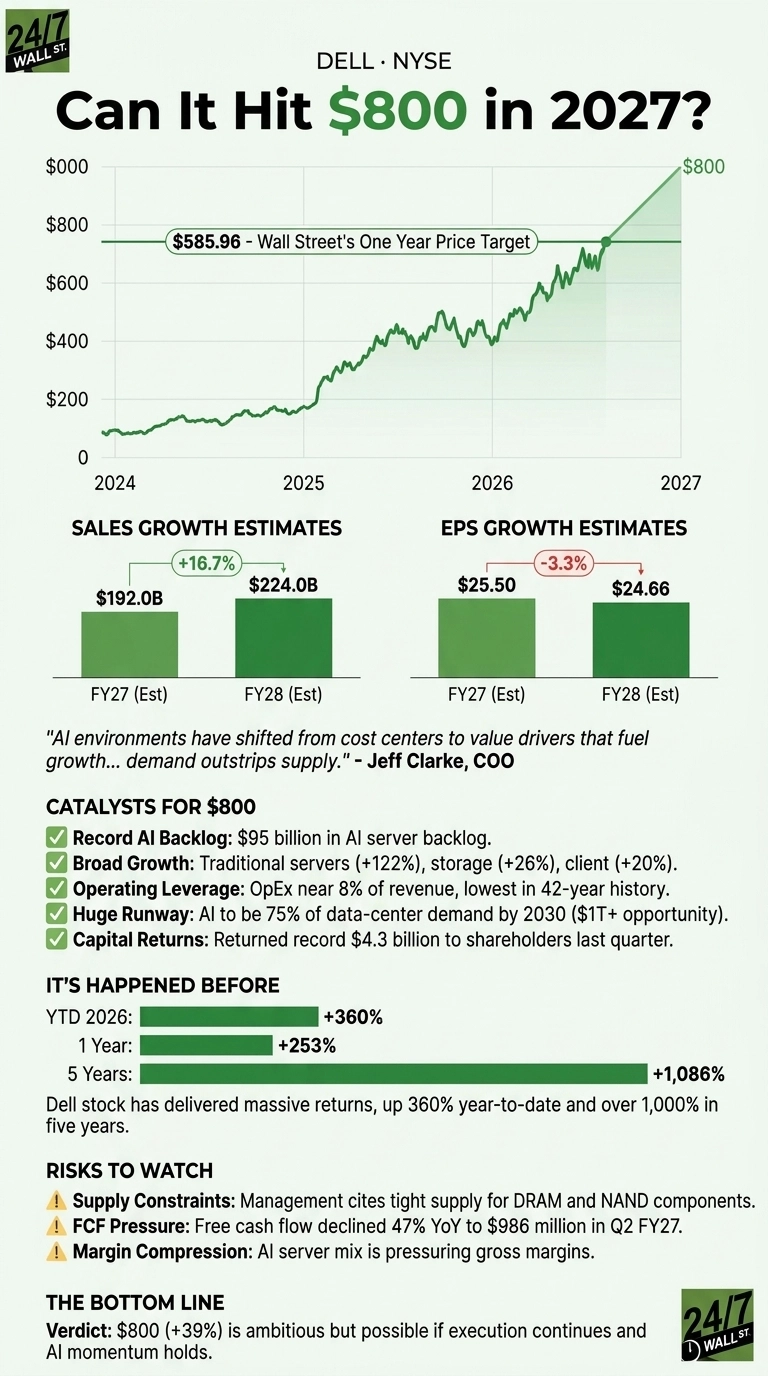
The average analyst target of $585.96 implies just 2% upside from $574.12. That conservative target trails the estimates behind it. Analysts expected $18.3732 in fiscal 2027 EPS 90 days ago. Today the figure is $25.8976, with zero down revisions over 30 days.
Dell has also beaten EPS estimates for 4 consecutive quarters, including a 43.69% beat last quarter. If that streak holds, actual results should keep coming in above forecasts.

Here’s What It Takes for Dell to Reach $800
At today’s price, Dell trades at about 23x the fiscal 2028 consensus of $24.6637. At $800, that multiple rises to roughly 32x. Measured against the high estimate of $30.19, it would be about 26x. Management already guides for fiscal 2027 non-GAAP EPS of $25.50, up 148%.
What Could Push Dell to $800?
- Record backlog: AI orders hit $60.9 billion last quarter, and backlog reached $95 billion.
- Growth beyond AI: Vice Chairman and COO Jeff Clarke noted “traditional servers and networking up 122%, storage up 26% and our client solutions up 20%.” New 18G servers can replace 12 to 14 servers.
- Operating leverage: Operating expenses near 8% of revenue would be the lowest in Dell’s 42-year history.
- Huge runway: Management expects AI to represent 75% of data-center demand by 2030 and sees an opportunity above $1 trillion.
- Capital returns: Dell returned a record $4.3 billion to shareholders last quarter.
Dell’s 2026 Run Shows $800 Is Within Reach
Reaching $800 requires a 39% gain. Dell has already cleared much bigger hurdles. Shares traded at $116.09 in February and reached $563.29 by mid-September. Over the past year, the stock has gained 253.42%.
Hurdles remain. Supply is tight, with management citing “DRAM, DRAM, DRAM, followed by NAND, NAND, NAND.” Free cash flow fell 47.22% to $986 million last quarter.

$800 Is a Stretch, but Dell Has the Ingredients
Hitting $800 would require roughly 39% upside in 2027. Estimates keep climbing, the beat streak is intact and the $95 billion backlog gives Dell unusual visibility. If supply improves and enterprise AI keeps expanding, a low-30s multiple is within reach.
Dell is one piece of the broader AI expansion (we covered seven other suppliers powering, cooling, and networking the data centers in a free report). Returns at this level shouldn’t be expected every year, but we’ve outlined the plan for how Dell could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.