Micron Cratered Losing 30% in 1 Month: 240% Gains Lie Ahead According to This Wall Street Pro

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
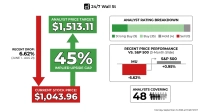
Micron Technology (NASDAQ:MU | MU Price Prediction) trades at $733.15. Wall Street’s average price target is $1,561.91, pointing to 113% upside.
Micron is the largest US supplier of DRAM, NAND and high-bandwidth memory (HBM), the chips that feed AI accelerators. Fiscal 2026 revenue reached $133.19 billion, up 256.3%. The most bullish analyst on the Street, KeyBanc Capital Markets’ John Vinh, has a $2,500.00 target. That translates to about 241% upside from here, even after the stock’s sharp drop.
Record Profits Collide With a Collapsing Share Price
The biggest blow came from fear that AI infrastructure spending has gone too far. Micron fell 28.74% over the past month, from $1,028.83, and 12.05% of that came in the last week alone. That is close to a 30% decline for a company of Micron’s size.
Investors also worried about rising inflation and about China’s ChangXin Memory Technologies, which said it could start shipping server memory by year-end. Political pushback against data-center projects and data showing Micron lost DRAM market share in the third quarter added pressure. The S&P 500 slid only 3.33% over the month, so this was a selloff in memory and storage stocks specifically.
The fundamentals gave investors little to complain about. Fiscal Q4 revenue of $54.23 billion beat the $50.97 billion consensus. Non-GAAP EPS of $33.42 exceeded the $31.35 estimate. Guidance calls for $61.5 billion ± $1.5 billion in fiscal Q1 revenue.
Analysts Are Raising Estimates While the Stock Falls
Coverage is mostly bullish. Nine analysts rate Micron a Strong Buy, 36 rate it a Buy, three rate it a Hold and one has a Strong Sell. Estimates are still going up. The fiscal 2027 EPS consensus is $176.5017, compared with $155.7946 90 days ago. Over the past month, 29 analysts raised their numbers and two cut them. At today’s price, that puts the stock at about 4x forward earnings.
KeyBanc’s thesis rests on sold-out HBM capacity, pricing power across DRAM and NAND, and a revenue mix shifting toward AI servers. Other top analysts are close behind: Cantor Fitzgerald at $2,300.00, Stifel at $2,100.00 and Goldman Sachs at $2,000.00.
More than 75% of fiscal 2027 shipments are committed, and Micron now has 26 supply agreements that run through 2030. Manish Bhatia, Micron’s president and COO, said “we really don’t have line of sight to when supply and demand balance.” The next milestones are HBM4E volume production in calendar 2027 and the first wafers from the Idaho fab in mid-calendar 2027.
Price targets are opinions, though. Many were set when the stock traded above $1,000, and memory cycles have caught analysts off guard before. The traits that showed up in the biggest tech winners long before their runs are the ones we cataloged in a free playbook, here.
Every Storage Stock Fell, and Sandisk Fell Hardest
Micron fell alongside its peers as the whole storage group sold off together.
Sandisk (NASDAQ:SNDK) dropped 43.96% in a month to $886.51. Its average target of $2,047.38 implies 131% upside, more than Micron’s. Analysts count four Strong Buys, 17 Buys, three Holds and one Strong Sell.
Seagate Technology (NASDAQ:STX) fell 35.36% to $506.14. Its $1,044.83 target implies 106% upside, a bit less than Micron’s, with four Strong Buys, 18 Buys and four Holds.
Western Digital (NASDAQ:WDC) lost 27.06% to $289.78. Its $613.38 target implies 112% upside, nearly the same as Micron’s, with four Strong Buys, 17 Buys and five Holds.
Sandisk offers the most analyst-implied upside among these stocks. Micron comes second.
Micron Is Still Up 157% This Year, Even After the Plunge
Micron is up 157.08% year to date, while the S&P 500 has gained 10.37%. Over the past month, Micron fell 28.74% and the index lost 3.33%.
At $733.15, the stock is well below its 52-week high of $1,254.61 and its 50-day average of $961.64. It trades at a trailing P/E of 9, and its beta of 2.398 means big swings in both directions should be expected.
Micron’s Earnings Power Outweighs the Cycle Risk
Optimism builds if HBM pricing holds, the supply agreements keep fiscal 2027 shipments locked in, and EPS lands near the $176.5017 consensus. In that case, even the average target looks conservative. Risks grow if AI capex budgets shrink, ChangXin wins server customers, or the new clean rooms coming online in late 2028 flood the market. At about 4x forward earnings, the market is pricing in a peak-cycle collapse. Rising estimates and committed demand support the analyst targets. Keep an eye on fiscal Q1 margins against the ~86.25% guide.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.