Tesla Stock Is Still a High-Stakes Bet on the Future. Here’s My Price Target

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
On the third-quarter earnings call, Elon Musk summed up where the business stands: “After many years of a sort of grind and things being fairly flat, I think we’re now headed for a lot of fun and significant growth.”[1] The stock tells a different story so far.
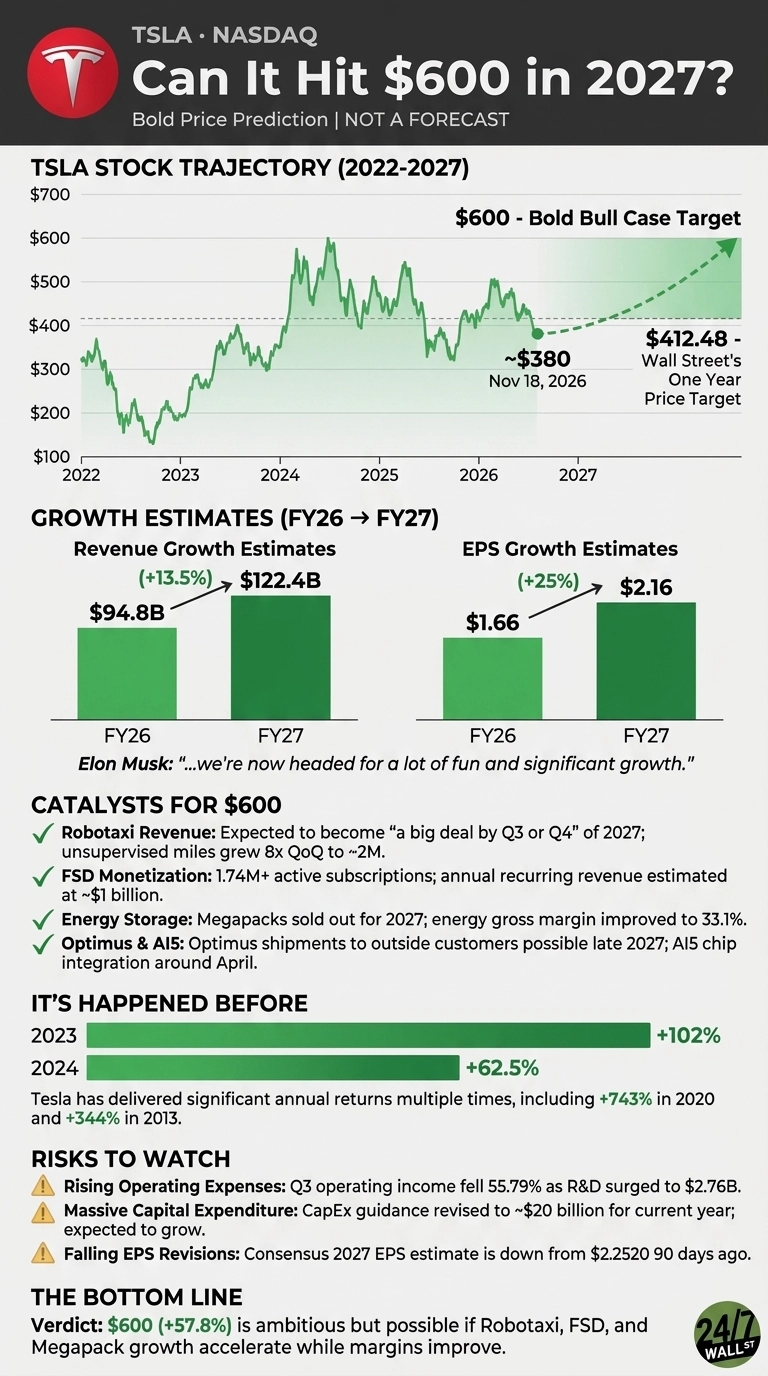
Tesla (NASDAQ:TSLA | TSLA Price Prediction) shares are down 15.48% year to date at $380.11 and up just 4.01% over five years. Under the hood, the business is moving quickly. Active FSD subscriptions reached 1.74 million[2], up from 1.04 million a year ago.
Cybercab joined the Austin Robotaxi fleet on September 3[2], and Optimus production has started in Fremont. Here’s what Tesla needs to do to hit $600 per share in 2027.

Wall Street Sees Only Modest Upside, and Its Forecasts Still Call for Growth
Analysts’ average 1-year target is $412.48, which means 8.5% upside. Opinion is split: 5 Strong Buy and 15 Buy ratings against 22 Holds and 2 Sells. Spending explains much of the caution. Q3 operating income fell 55.79%[2] to $718 million as R&D rose to $2.76 billion from $1.63 billion.

Even so, consensus calls for 2027 EPS of $2.1592, 25% above the 2026 estimate of $1.7242. Revenue is expected to reach $122.4 billion, which would represent 13.5% growth. Tesla has beaten EPS estimates in three of the last four quarters. In Q3 it reported $0.48[2] against a $0.4511 estimate.

Here’s What It Takes for Tesla to Reach $600
Tesla currently trades at 176x 2027 estimated earnings. At $600, the multiple would rise to 278x. The 2027 estimates are spread widely, though. Measured against the most bullish 2027 EPS forecast of $4.13, $600 works out to 145x, cheaper than today’s multiple on consensus.
So the path to $600 depends on estimates moving toward the high end. Revisions have recently gone the other way: the consensus figure is down from $2.2520 90 days ago.

What Could Push Tesla to $600?
- Robotaxi revenue: Musk said Robotaxi revenue should become noticeable around Q2 and “a big deal by Q3 or Q4 of next year.”[1] Unsupervised miles grew 8x[2] in the quarter to nearly 2 million.
- FSD monetization: More than 75%[1] of North American Q3 deliveries came with a paid FSD sign-up. On the call, Vaibhav Taneja confirmed an analyst’s estimate of about $1 billion[1] in FSD annual recurring revenue.
- Energy: Musk said Tesla is almost sold out of Megapacks for 2027[1]. Energy gross margin rose to 33.1%[1] from 20.4%, helped in part by tariff refunds.
- Optimus: Management expects to start shipping robots to outside customers toward the end of next year, with the AI5 chip integrated around April[1].
- SpaceX merger: Barclays upgraded Tesla to Overweight on October 26 and raised its target to $450 from $370. The firm pointed to upside from the expected merger with SpaceX and to data center demand.
Tesla’s History Says $600 Is Possible
A $600 share price would need a 57.8% gain. Tesla has hit that level four times since 2011, using split-adjusted year-end prices. Shares rose 743% in 2020, 344% in 2013, 102% in 2023 and 62.5% in 2024. Big moves cut both ways: the stock fell 65% in 2022.
With a market cap near $1.50 trillion, another 2020 is unlikely. The 2023 and 2024 gains, however, show how fast this stock can be appreciated once sentiment changes.
Why $600 Is a Stretch Worth Studying
Getting to $600 would take a 57.8% gain in 2027, well above Wall Street’s $412.48 target.
The bull case rests on three things: Robotaxi turning into real revenue, FSD subscriptions continuing to compound and Megapack demand holding up. The main hurdles are rising operating expenses, capex guidance of about $20 billion[1] for this year and falling EPS revisions.
If Tesla can turn its lead in autonomy into profit and keep beating estimates, $600 becomes achievable. Such rare returns led us to reverse-engineer what the earliest days of the biggest tech winners looked like in a free Next Nvidia playbook.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.