Tesla Stock Could Be Worth Much More in 2027. Here’s the Number I’m Watching

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
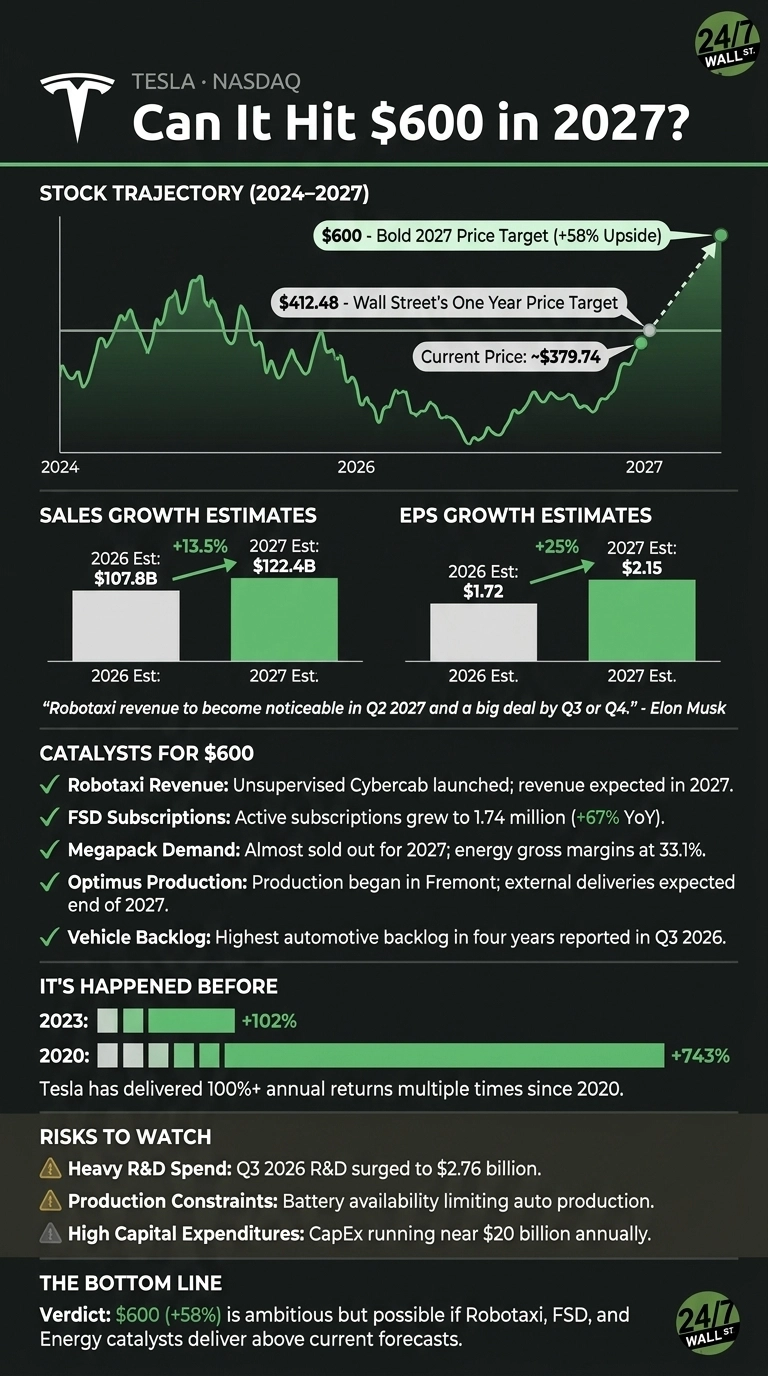
Tesla (NASDAQ:TSLA | TSLA Price Prediction) spent 2026 rebuilding its business around autonomy, but the stock has not caught up yet. Shares are down 15.56% year to date at $379.74, and the five-year gain stands at just 4.61%.
Several operating milestones were reached: Cybercab joined Austin’s unsupervised Robotaxi fleet on Sept. 3[1], active FSD subscriptions rose to 1.74 million[1] from 1.04 million a year earlier, and Optimus production began in Fremont. That sets up 2027 as a possible comeback year. Here’s what Tesla needs to do to hit $600.

Wall Street Sees Only Modest Upside for Tesla
The consensus price target is $412.48, which implies 8.6% upside. Analysts are split: 20 rate the stock a Buy or Strong Buy and 22 rate it a Hold. Analysts expect 2027 revenue of $122.4 billion, up 13.5%, and EPS of $2.1592, up 25% from $1.7242.
Revisions are mixed. Over the past 30 days there were 17 downward 2027 EPS revisions against 11 upward ones. Still, Tesla has beaten EPS estimates in 3 of the last 4 quarters, including Q3’s $0.48[1] against $0.4511 expected.

Here’s What It Takes for Tesla to Reach $600
Tesla currently trades at 176x its 2027 earnings estimate. At $600, that multiple would rise to 278x. The S&P 500 trades at roughly 21x to 23x. Investors value Tesla on what autonomy and robotics could earn, which makes upside to earnings estimates the key driver.
Analysts’ highest 2027 EPS estimate is $4.13. If Tesla gets there, $600 works out to 145x. Measured by sales, the multiple would go from 12x 2027 revenue today to 19x.

What Could Push Tesla to $600?
- Robotaxi revenue: Musk said Robotaxi revenue “starts to become noticeable probably in Q2 and then probably a big deal by Q3 or Q4 of next year.”[2] Cybercab capacity tops 125,000 units a year, and Tesla has begun selling Cybercabs for personal use.
- FSD recurring revenue: More than 75%[2] of North American Q3 deliveries included a paid FSD sign-up. The CFO confirmed an analyst’s estimate of roughly $1 billion[2] in annual recurring revenue.
- Energy storage: Musk said Tesla is “almost sold out of all Megapacks for 2027,”[2] and energy gross margin rose from 20.4% to 33.1%.
- Vehicle backlog: Tesla ended Q3 with its highest automotive backlog in four years[2].
- Optimus and SpaceX: Tesla expects to deliver Optimus to outside customers toward the end of next year[2], and Musk’s push to merge Tesla and SpaceX adds another possible catalyst.
Tesla’s History Says a 58% Gain Is Possible
Reaching $600 requires a 58% gain. Tesla has done better than that before, returning 743% in 2020 and 102% in 2023.
The swings go both ways, though: shares gained 50% in 2021 and then fell 65% in 2022. With a beta of 1.743 and a 52-week high of $498.83, Tesla can move quickly in either direction.

$600 Is a Stretch, but the Pieces Are in Place
Reaching $600 would take a 58% gain, well beyond Wall Street’s target.
Hurdles remain: R&D spending rose to $2.76 billion[1] from $1.63 billion, battery supply is limiting production, and capital spending is running near $20 billion[2].
Even so, Robotaxi revenue on track for 2027, growing FSD subscriptions and a Megapack business that is nearly sold out could push earnings above today’s forecasts. Returns at this level are rare, and this is the model for how Tesla could deliver outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.