Western Digital Cratered 40% in The Last 3 Months: This Wall Street Desk Now Predicts 200% Returns After Raising Its Target Price

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
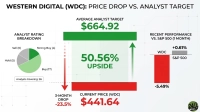
Western Digital (NASDAQ:WDC | WDC Price Prediction) currently trades at $296.78. Wall Street’s average price target is $613.38, which implies 106.68% upside.
Western Digital became a pure-play hard disk drive maker after it spun off its flash business into Sandisk (NASDAQ:SNDK) in February 2025. Hyperscalers buy its high-capacity drives to store the data that AI workloads generate. The company has also beaten EPS estimates for six consecutive quarters.
Some targets sit far higher. Baird raised its target to $900.00, which implies 203.25% upside from here.
A Violent Slide Despite a Record Quarter
The main driver was a sector-wide pullback in AI hardware, and Western Digital fell harder than most. Shares dropped 36.71% over the past three months and now sit 62.88% below the 52-week high of $799.61. That is a selloff well beyond 30%.
The decline came even as results kept improving. In the fiscal first quarter, non-GAAP EPS of $4.64[1] beat the $4.08 consensus, and revenue rose 55.5% to $4.38B. Even so, the stock was worth $553.20[2] when the prior quarter was reported and only $374[1] when this one came out.
Over the past month, Western Digital lost 18.54% while the S&P 500 fell 6.92%. One recent leg lower came when weakness in chipmakers dragged down the AI memory group. A beta of 2.344 means swings like that hit this stock harder than the broader market.
Analysts Keep Raising Estimates as the Price Falls
The ratings are firmly bullish. Four analysts rate the stock Strong Buy, 17 rate it Buy, five rate it Hold and none rate it Sell (4/17/5/0). Earnings estimates are rising too. The fiscal 2027 EPS consensus climbed to $24.7248 from $20.2553 a month ago, and fiscal 2028 rose to $40.4048. No analyst cut an estimate in the past 30 days.
Baird analyst Tristan Gerra raised his target from $630.00 and kept an Outperform rating. His case rests on exabyte demand from hyperscale customers, gross margins approaching 60%, and strong cash generation. Guidance supports that view. Management expects revenue of about $5.10B[1], gross margin of 60-61% and EPS of $5.80 next quarter.
The next catalysts are product launches. Western Digital expects to finish first-generation HAMR qualifications with two hyperscalers in Q1 calendar 2027[3], with volume shipments in the first half of that year. CEO Irving Tan said the company has “good visibility up to 2030, 2031”[3] with its top customers. Storage is one slice of the AI buildout most investors overlook in favor of the chipmakers (we rounded up seven non-chip suppliers riding the same wave in a free report).
Some analysts are more cautious. Rosenblatt trimmed its target to $650. For Baird’s $900 target to play out, pricing and margins have to hold up if competitors such as Toshiba add capacity. Price targets are estimates, and none of them is guaranteed.
Storage Peers Fell Together, but Their Upside Varies Widely
The whole group sold off together, which points to a sector-wide repricing.
Seagate Technology (NASDAQ:STX) fell 22.77% over the past month to $521.39. Its average target of $1044.83 implies 100.39% upside. Four analysts rate it Strong Buy, 18 Buy and four Hold (4/18/4), so its setup closely mirrors Western Digital’s.
NetApp (NASDAQ:NTAP) fell 18.95% over the past month to $170.18. Its target of $211.69 implies just 24.39% upside. Hold ratings lead with 13, against eight Buy or Strong Buy ratings (1/7/13).
Western Digital has the largest implied upside in the group, just ahead of Seagate. It also trades at a lower forward multiple: about 12x, compared with Seagate’s 13x.
A Big Yearly Gain Hides a Stock Trading at Half Its Target
Western Digital currently trades at $296.78, against an average target of $613.38 from 26 analysts (26). That works out to 106.68% implied upside. The trailing P/E is just 10.
Even after the selloff, the stock is up 72.46% year to date, while the S&P 500 is up 4.97%. Over one year, Western Digital gained 93.11% and the index gained 8.03%.
What Could Close Western Digital’s Gap to Its Price Target
The bull case for Western Digital strengthens if price per terabyte keeps rising, gross margins land in the guided 60% range and HAMR drives ship on schedule. Average price per terabyte rose 28%[3] last quarter, and management sees room for more increases. The bear case gains weight if Toshiba or Seagate adds capacity faster than demand grows, or if rising DRAM and NAND costs squeeze margins. Customers in the Cloud segment account for 88%[3] of revenue, so a pause in hyperscaler spending would hit hard.
I lean bullish. The stock trades at 12x forward earnings while estimates rise. The selloff reflects fear about where the cycle peaks. Expect volatility to stay high.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.