Is Western Digital’s Nightmare 3 Months Over? A Wall Street Pro Says Its Price Will Increase 130%
Western Digital stock has cratered more than 50% from its peak even as earnings beat estimates and revenue surged, leaving investors to wonder whether Wall Street's most aggressive analyst has spotted something the market is missing.

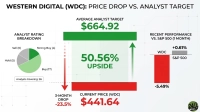
Western Digital (NASDAQ:WDC | WDC Price Prediction) is now priced at $380.88. Wall Street’s average price target of $610.04 suggests 60.17% upside.
Western Digital now makes only hard disk drives. It spun its flash business off into Sandisk (NASDAQ:SNDK), and today cloud customers storing AI data account for 88% of total revenue. The most bullish call on Wall Street comes from Robert W. Baird, which raised its target from $630 to $900.00 and kept an Outperform rating. Removing $900 would take a gain of about 136%.
Record Earnings Could Not Stop a 52% Slide From the Peak
Expectations broke this stock. Results held up fine. Shares are down 17.8% over the past three months and sit 52.37% below their 52-week high of $799.61. That is a large drop, well past 30%. The slide picked up speed in August, when the stock fell 12% despite beating earnings estimates as investors began to fear that storage pricing had topped out.
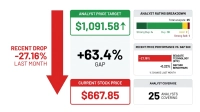
The whole sector sold off. Seagate Technology (NASDAQ:STX) lost 27.16% over the past month. Western Digital lost 16.62% over the same stretch. Even a strong fiscal first quarter barely helped.
Non-GAAP EPS came in at $4.64 against a consensus of $4.0771, revenue grew 55.46% to $4.381 billion, and gross margin hit 58.1%. Barron’s wrote that the report failed to get the stock back on track. Cantor Fitzgerald also cut its target to $625.00.
Analysts See Margin Expansion That the Market Doubts
The bull case rests on pricing power. Average price per terabyte rose 28% year-over-year, and CFO Kris Sennesael said incremental gross margins remain “well above 80%.” For the second quarter, management guided to revenue of about $5.1 billion, which would mean 66%–72% growth, plus gross margin of 60%–61% and EPS of $5.80 +/- $0.20.
Visibility supports the thesis. CEO Irving Tan said the company has good visibility through 2030, 2031 with its top seven customers. He called the current 22% exabyte growth rate the floor. Volume shipments of HAMR drives begin in the first half of calendar year 2027, which is the next catalyst to keep an eye on.
Estimates keep climbing. Consensus EPS for fiscal 2028 has risen to $39.5522, up from $27.1477 90 days ago. Baird’s $900 view leans on speeding up nearline drive volumes, gross margin approaching 60%, and a re-rating now that Western Digital is a pure-play HDD company. Recent analyst moves have been mixed. Baird raised its target while Cantor cut. Targets are opinions, and this consensus assumes pricing keeps rising.
Seagate Fell Harder While NetApp Climbed
The two hard drive makers sold off together. Enterprise storage moved the other way.
Seagate is priced at $667.85 compared with a target of $1091.58, suggesting 63.45% upside. Its analyst mix is 4 Strong Buy, 18 Buy, 2 Hold and 1 Strong Sell. That gives it slightly more upside than Western Digital, from a large monthly drop.
NetApp (NASDAQ:NTAP) rose 13.39% over the past month to $227.58. That price sits above its $211.69 target, suggesting 6.98% downside. Ratings lean conservative, at 2 Strong Buy, 6 Buy and 12 Hold.
Seagate holds the largest implied upside, with Western Digital close behind. That makes this a breakdown across hard drive stocks, and Western Digital trades as part of that group.
Up 121% This Year, Still Far Below Target
Western Digital is priced at $380.88, and the 26 analysts covering it set an average target of $610.04, suggesting 60.17% upside. The ratings break down this way:
- Strong Buy: 4
- Buy: 17
- Hold: 5
- Sell: 0
Even after the selloff, shares are up 121.34% year to date, compared with 12.87% for the S&P 500. The stock has also rebounded 4.55% over the past week. It trades at roughly 17x forward earnings with a beta of 2.169, so expect big swings in both directions.
Fundamentals Look Strong, but Pricing Decides
The bull case for Western Digital strengthens if pricing per terabyte keeps rising for the three, four quarters management called out and HAMR ships on schedule. In that case, a 60% gross margin and fiscal 2028 earnings near consensus make the average target look reasonable. The thesis weakens if hyperscalers slow their spending or rival capacity undermines pricing. Customer concentration and cyclical drive pricing are exactly the risks the market is pricing in.
I lean bullish. The business is growing faster than the stock is falling, and estimates keep rising. Baird’s $900 target needs everything to go right, so the $610.04 consensus is the more realistic marker.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.