If You’re Turning 66 This Year, Can You Claim Your Full Social Security Benefit in 2026?
When you collect Social Security, you're entitled to a standard benefit called your primary insurance amount (PIA), calculated from your 35 highest-earning years. You receive this full amount only at your full retirement age (FRA). If you're turning 66 in…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

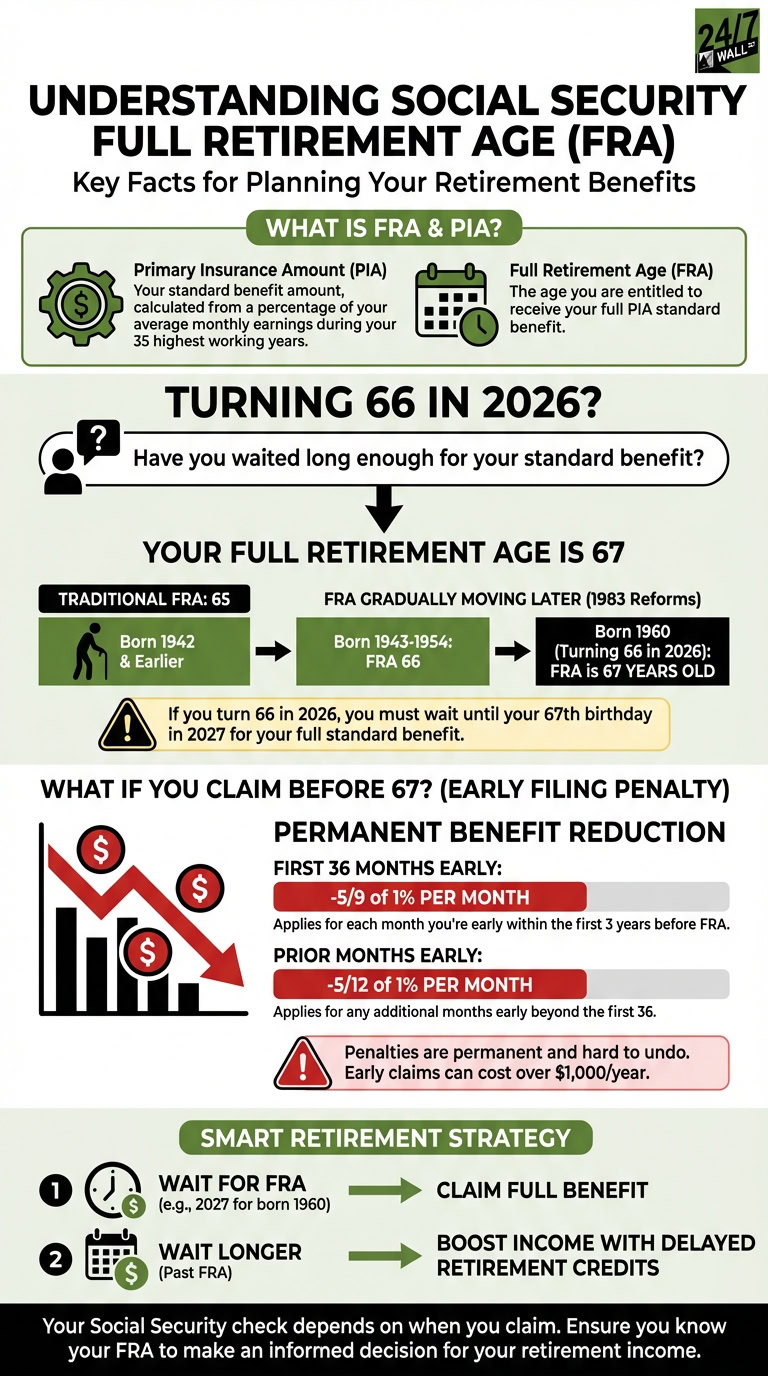
When you collect Social Security, you receive a standard benefit called your primary insurance amount (PIA). That figure is calculated as a percentage of your average indexed monthly earnings (AIME) across your 35 highest-earning working years.
You receive that full PIA when you file for benefits at your full retirement age (FRA). While you can start collecting as early as 62, FRA falls several years later. The traditional FRA of 65 has not applied for decades, so if you are turning 66 this year, the answer to whether you have waited long enough is probably no.
Your full retirement age if you turn 66 in 2026
Full retirement age has shifted later due to the 1983 Social Security reforms Congress passed to shore up the program’s finances. FRA began at 65, then moved to 66 for workers born between 1943 and 1954. For every birth year after 1954, FRA crept back by two additional months.
If you are turning 66 in 2026, you were born in 1960. For that birth year, FRA is 67. Those who turned 66 in 2025 were born in 1959, and their FRA was 66 years and 10 months. The 1960 birth year marks the final step in a decades-long transition: 67 is the highest FRA currently written into law, and no further increases are scheduled at this time.
Turning 66 in 2026 does not entitle you to full benefits. For this cohort, claiming at the standard benefit level means waiting until the 67th birthday in 2027. On the positive side, the 2026 cost-of-living adjustment of 2.8% has already lifted payments across the board. As of mid-2026, the average retired worker receives roughly $2,086 per month, according to Social Security Administration data.
One additional development worth noting for workers in this cohort: the Social Security Fairness Act, signed into law in January 2025, repealed two longstanding provisions called the Windfall Elimination Provision (WEP) and the Government Pension Offset (GPO). Those rules had reduced or eliminated benefits for more than 2.8 million public-sector retirees, including teachers, police officers, and firefighters who also drew pensions from jobs not covered by Social Security. By July 2025, the SSA had distributed over $17 billion in retroactive payments to eligible beneficiaries, completing the process five months ahead of schedule. Anyone in the 1960 birth cohort who previously held a non-covered public-sector job should confirm with SSA whether this change affects their projected benefit before filing.
What happens if you claim before 67?
Learning you may need to delay your benefits claim longer than expected is frustrating, but understanding the exact cost of filing early is essential before making a decision you cannot easily reverse.
When you file before your FRA, a permanent penalty applies for every month you are early. For each of the first 36 months before FRA, you lose 5/9 of 1% of your benefit. For every month beyond those first 36, the reduction drops to 5/12 of 1%. For someone born in 1960 who claims at 62, the total penalty reaches 30%, cutting a full benefit to just 70 cents on the dollar. In concrete terms, the SSA-published maximum monthly benefit at FRA in 2026 is $4,152, while the maximum for someone claiming at 62 is $2,969, a gap of more than $1,180 per month that persists for life. Waiting until 70 raises the maximum to $5,181.
Early filing penalties are permanent. The only practical exit is to withdraw your claim within 12 months of approval and repay every dollar of benefits you received to that point.
The upside of waiting past 67
For those who can afford to hold off past their FRA birthday in 2027, the payoff is substantial. Social Security credits delayed claiming at 8% per year for every year past FRA, up to age 70. Waiting three full years beyond FRA can increase your monthly benefit by up to 24% above your PIA. That higher base also compounds with future cost-of-living adjustments, meaning each annual COLA applies to a larger starting figure for the rest of retirement.
Looking ahead, the Senior Citizens League estimates the 2027 COLA at around 3.6%, with the official announcement expected October 14, 2026. That projected increase would lift the average monthly benefit further, reinforcing the value of locking in the highest possible base before COLAs begin stacking.
If you are still working while you wait, keep the 2026 earnings test thresholds in mind. Before FRA, Social Security withholds $1 for every $2 you earn above $24,480 per year, per SSA rules. In the year you reach FRA, a more generous threshold applies: $1 is withheld for every $3 earned above $65,160. Once you reach full retirement age, the earnings test disappears entirely and you can earn any amount without affecting your benefit.
The bottom line for anyone turning 66 in 2026: your FRA is your 67th birthday in 2027. Claiming before then permanently reduces your check, while waiting until 67 or beyond locks in a higher benefit for the life of your retirement.
Editor’s note: This article was updated to reflect the mid-2026 average retired-worker benefit of $2,086 per month, the SSA’s completion of $17 billion in Social Security Fairness Act retroactive payments by July 2025 covering over 2.8 million public-sector retirees, and the Senior Citizens League’s projection of a 3.6% COLA for 2027 with an official announcement expected October 14, 2026.
Contact [email protected] for any questions or corrections.
Christy Bieber has been a personal finance and legal writer since 2008. She has a JD from UCLA School of Law and a BA in English, Media and Communications with a certification in business from the University of Rochester.
Christy has been published by a wide variety of sites, including WSJ Buy Side, Forbes, Kiplinger, Fox Business, Credit Karma, Insurify, and Annuity.org. In addition to writing for the web, she has also ghostwritten textbooks on business and law and served as a subject matter expert for course design.