Baby Boomers Won the Retirement Lottery and Everyone Else Is Playing Catch-Up

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Baby Boomers have enjoyed better economic conditions than most generations that followed them.
Federal Reserve data from Q2 2026 shows the generation now controls 52.5% of all U.S. household wealth, holding $97.4 trillion of a combined $185.7 trillion across all American households. Millennials hold just 11.2% of that total despite representing a nearly identical share of the population. Many of those Millennials, including the Boomers’ own children, continue struggling to break into the housing market. The youngest Baby Boomers turn 62 this year, reaching the earliest Social Security eligibility age. As they look toward retirement over the coming years, real questions linger about whether Millennials or Gen Z will retire anywhere near the timeframe their Baby Boomer parents managed.
Millennials are not as well positioned financially as their parents were at similar ages, and the numbers show why. Housing prices have surged over the decades, recent inflation has eroded savings, and real wage growth has lagged behind cost increases. Median home prices have climbed more than 400% since 1990, while median household income rose less than 200% over the same period. That gap closed the door on early homeownership for millions of younger Americans and denied them the decades of equity appreciation Boomers accumulated. Legislative updates like the SECURE Act 2.0 offer new safety valves. The law, which took full effect in 2024 and 2025, includes penalty-free emergency withdrawals of up to $1,000 annually for unforeseeable expenses and expanded catch-up contribution limits reaching $11,250 for savers ages 60 to 63 in 2026. These provisions were simply unavailable to previous generations.
The contrast is sharp. The youngest Baby Boomers are entering retirement with sizable portfolios built over decades of favorable market conditions. They are also benefiting from a legislative windfall: the Social Security Fairness Act, signed into law on January 5, 2025, repealed the Windfall Elimination Provision (WEP) and Government Pension Offset (GPO) retroactive to January 2024. The law restored full Social Security benefits to approximately 2.8 million retired public service workers, including federal, state, and local government employees who had previously seen their benefits cut. By July 7, 2025, the Social Security Administration had completed more than 3.1 million retroactive payments totaling $17 billion, finishing five months ahead of schedule.
Looking further out, the wealth Boomers have accumulated will eventually flow to younger generations. Cerulli Associates projects that $124 trillion in total wealth will be transferred through 2048, with nearly $100 trillion coming from Baby Boomers and older generations. That figure dwarfs Cerulli’s earlier estimate of $84.4 trillion through 2045, reflecting the continued growth of Boomer portfolios as retirement unfolds.
A “lost decade” may not hit Baby Boomers as hard in retirement.
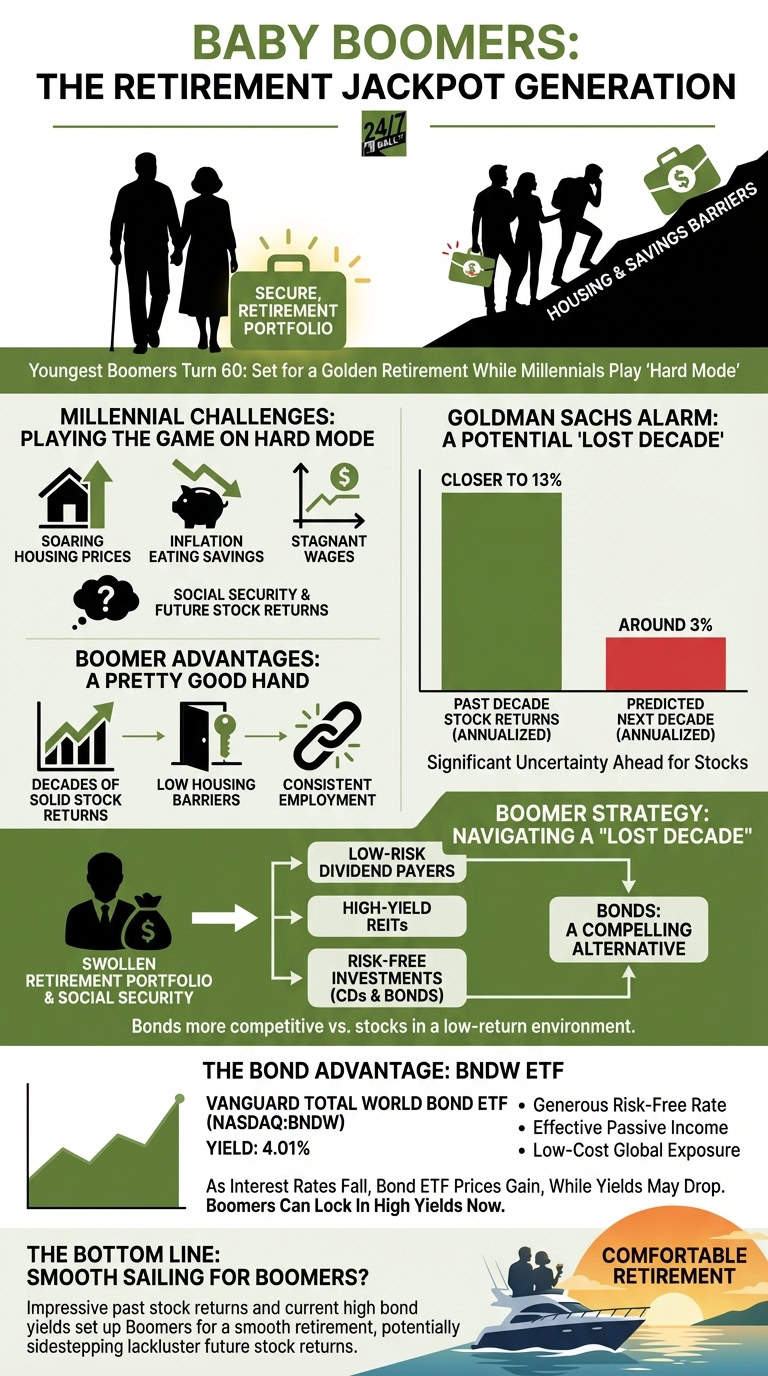
The Baby Boomer generation captured decades of strong stock returns, low barriers to homeownership, and consistent employment prospects. Goldman Sachs published a long-range paper in October 2024 projecting that the S&P 500 would deliver annualized nominal total returns of just 3% over the next ten years, citing extreme market concentration and elevated valuations. By November 2025, Goldman revised that base case upward to 6.5% annually, keeping the original 3% as the downside scenario and citing a range of 3% to 10% depending on market concentration and valuation outcomes. Meanwhile, by late May 2026, Goldman’s equity strategy team had raised its year-end 2026 S&P 500 target to 8,000 and lifted its 2026 earnings-per-share forecast to $340, implying 24% year-over-year profit growth. Both the cautious long-range view and the more constructive near-term outlook point to the same conclusion for Boomers: retired investors who have already shifted assets away from equities face less exposure to whatever the market delivers next.
Many Boomers are now reallocating into low-risk dividend stocks, high-yield real estate investment trusts (REITs), and safer fixed-income instruments like certificates of deposit (CDs), Treasuries, and bonds. Goldman’s base case assumes the S&P 500 valuation multiple will remain roughly flat at around 21 times forward earnings, as any modest declines in Treasury yields are likely offset by slowing growth and geopolitical uncertainty. Retirees who have already reduced equity exposure sidestep that risk by design. Modern income engineering strategies, including covered call approaches on major ETFs, allow many to generate yields between 7% and 11% even in flat or sideways markets. Funds like the JPMorgan Equity Premium Income ETF and Goldman Sachs Nasdaq-100 Premium Income ETF have attracted billions in assets by offering monthly income with reduced volatility, trading some upside participation for steady premium income.
Covered call strategies offer a practical path around the “lost decade” scenario: rather than depending on price appreciation, investors collect recurring premium income regardless of index direction. Baby Boomers overweighting bonds and pairing them with these yield-enhancement tools may continue faring well in the subdued-return environment that Goldman’s long-range model envisions.
Bonds offer yields not seen in years relative to stocks.
Baby Boomers can now capture attractive rates from bonds and bond funds that were largely unavailable for much of the past 15 years. The Vanguard Total World Bond ETF (NYSEARCA:BNDW) carried a 30-day SEC yield of 4.34% and a distribution yield of 3.84% as of the end of August 2026, making it an effective single-vehicle way to gain global bond market exposure without taking on equity risk. BNDW wraps the entire global investment-grade bond market into a low-cost structure with an expense ratio of just 0.05%.
The broader fixed-income environment has remained elevated well beyond the late-summer turning point. The 10-year Treasury yield climbed above 5% during the fall of 2026, reaching as high as 5.31% on October 5, 2026, its highest level since before the 2008 financial crisis. Yields have since pulled back modestly, trading near 4.9% in early November, but the broader trend has validated what bond market strategists anticipated: persistent rate pressure that leaves income-seeking retirees with opportunities not widely available for more than 15 years. Rising yields push bond prices lower in the short term, but elevated starting yields mean investors who hold to maturity lock in returns that simply were not on the table for most of the 2010s.
When interest rates eventually decline, bond ETFs like BNDW should appreciate in price while their yields compress. Baby Boomers putting the finishing touches on their passive income portfolios may find it worthwhile to lock in these relatively elevated yields now, giving them dependable income throughout retirement. For younger generations, the “catch-up” increasingly involves a different kind of geographic flexibility: leveraging remote work to relocate to lower-cost regions and effectively decouple income from the high-cost housing markets that Boomers were able to dominate a generation earlier.
The bottom line
Baby Boomers are well positioned for the retirement years ahead. Strong stock returns over the past decade accelerated nest egg growth for many, and the youngest Boomers who reach 62 this year can capture yields in the 4% to 5% range from bonds and bond funds. Those yields are further supported by the 2.8% cost-of-living adjustment (COLA) for Social Security benefits in 2026, which translates to an average monthly increase of about $56 for retired workers, lifting the average monthly retirement benefit from roughly $2,008 to about $2,064, according to SSA data.
If Goldman’s long-range outlook for below-average equity returns materializes, Boomers emphasizing bonds and active income engineering through covered call strategies may sidestep lackluster index returns. Bonds look competitive at current levels, with elevated yields and upside price potential if rates eventually move lower. The combination of the Social Security Fairness Act’s retroactive benefit restoration, flexible income strategies that prior generations never had access to, and the ability to harvest yields across multiple asset classes positions this generation uniquely well as it moves collectively into retirement.
Editor’s note: Boomer wealth figures were updated to Q2 2026 Federal Reserve data, now showing Baby Boomers hold $97.4 trillion (52.5%) of a combined $185.7 trillion in total U.S. household net worth, with the Millennial share revised to 11.2%. The Goldman Sachs long-range equity return section was revised to reflect the firm’s November 2025 update, which raised its 10-year base-case S&P 500 forecast to 6.5% annually while retaining 3% as the downside scenario. The Treasury yield section was refreshed to note the 10-year benchmark reached 5.31% on October 5, 2026, its highest level since before the 2008 financial crisis, before retreating to near 4.9% in early November.
Contact [email protected] for any questions or corrections.
Joey is a 24/7 Wall St. contributor and seasoned investment writer whose work can also be found in publications such as The Motley Fool and TipRanks. Holding a B.A.Sc in Computer Engineering from the University of British Columbia (UBC), Joey has leveraged his technical background to provide insightful stock analyses to readers.
Joey's investment philosophy is heavily influenced by Warren Buffett's value investing principles. As a dedicated Buffett disciple, Joey is committed to unearthing value in the tech sector and beyond.