Retirees Who Ended Up Alone in The Villages Say Nobody Warned Them What It Would Cost

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
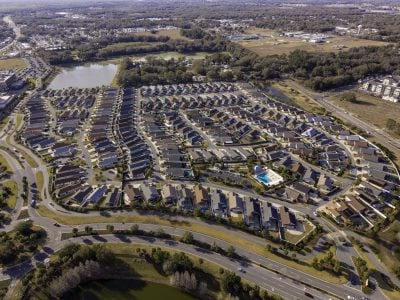
People often ask about retiring to a place like The Villages in central Florida, and the math usually works for a healthy couple. What almost nobody asks, until it is too late to plan for, is what happens when the couple becomes one person in the same house. Widowhood, divorce, a spouse moving into memory care. One of you will almost certainly face it. Here is what the numbers actually look like on the other side of that day.
Architecture Built for Two
An age-restricted community is engineered around couples. The clubs pair off, the dining is for two, and the neighborhood rhythm assumes a partner. The financial engineering assumes the same thing just as completely. Almost every fixed cost in the household, including property taxes, homeowners insurance, the amenity fee, the CDD assessment, utilities, cart maintenance, and the mortgage if there is one, was underwritten by two Social Security checks and often two pensions. None of those costs fall when one person is gone.
Social Security is the first line item to reset. When a spouse dies, the survivor keeps the larger of the two benefits, not both. If one check was $2,600 and the other was $1,800, the household income drops to $2,600. The Social Security Administration officially confirmed a 3.6% COLA for 2027 on October 14, 2026, the largest adjustment since 2023, adding about $75 a month to the average retirement benefit check. That increase does not close the income gap widowhood creates; it only applies to what is left. A pension may continue at a reduced percentage or stop entirely, depending on the survivor election made at retirement. That choice between a 100% joint and survivor benefit, a 50% survivor benefit, or a life-only annuity that pays nothing after death was made years ago and is generally irrevocable.
Tax Code Compounds the Loss
The tax code worsens the shortfall in ways that catch many survivors off guard. In the year of death, the survivor can still file jointly. For two more years after that, a qualifying surviving spouse filing status applies if a dependent child is in the home, which is uncommon in this community. After that, the filing status flips to single. For 2025, the joint standard deduction is $31,500 and the 22% bracket does not begin until taxable income reaches $96,951. For a single filer, the standard deduction is $15,750 and the 22% bracket starts at $48,476. The same retirement income keeps arriving, but more of it gets taxed at a higher rate.
One provision worth understanding: the One Big Beautiful Bill, signed into law on July 4, 2025, added a temporary $6,000 senior deduction for qualifying adults 65 and older, available through 2028. The deduction is on top of the standard deduction and can be claimed whether a filer itemizes or not. It phases out at a rate of 6 cents per dollar of modified adjusted gross income above $75,000 for single filers and above $150,000 for joint filers. For a surviving spouse filing single whose income falls below that threshold, it softens the tax bite in a meaningful way, though it does not eliminate the bracket gap created by losing joint status.
Medicare follows the same logic. In 2026, Part B IRMAA surcharges kick in above $109,000 of modified adjusted gross income for a single filer, versus $218,000 for a couple. The standard Part B premium is $202.90 per month before any surcharge. A survivor doing a Roth conversion or taking a large IRA distribution can cross that $109,000 threshold on income the couple, filing jointly at twice the limit, never had to think about.
Costs That Only Show Up When You Are Alone
Then there are the costs that never appeared on the joint budget because one spouse was quietly providing them. Driving to appointments. Fixing the disposal. Paying bills on time. Cooking. Watching for the small signs that something is wrong. In a community built around independent living, none of this is provided by the community itself. Home care in central Florida costs real money once it becomes a regular need, and 24-hour care is a serious expense. Transportation once you stop driving becomes another budget line, because the golf cart only goes so far.
The house itself is often the central problem. It was priced for two incomes and sized for two people. Selling is not painless either, and while the S&P Cotality Case-Shiller national home price index stood at 336.7 in June 2026 (nominally near a recent high), home prices have been falling in real terms for more than a year as inflation outpaces price appreciation. That dynamic tells you nothing useful about your specific villa on your specific street. For broader context, average annual household expenditures came to $78,535 in 2024, according to the Bureau of Labor Statistics Consumer Expenditure Survey. A widow in a paid-off home in The Villages can still exceed that figure once solo healthcare costs and paid help are added up.
Distance to Your Children Is Now Distance to Help
Many people chose The Villages precisely because it was far from where their adult children live. For a healthy couple, that was a reasonable tradeoff. For a person living alone who has stopped driving and needs a ride to the cardiologist at seven in the morning, it is a different calculation entirely. Neighbors help, but in an age-restricted community, neighbors are aging alongside you. The ones who were closest often move away to be near their own children. In practice, the support network shrinks to paid help and whichever child is willing to fly down. Both have a price, and neither one is in the brochure.
The Calculation to Run Before Either of You Needs It
Do the arithmetic while both of you are still here. Add up the fixed costs that will not fall: property taxes, homeowners insurance, the amenity fee, CDD assessments, utilities, and a maintenance reserve. Then subtract the survivor’s own Social Security benefit and whatever the pension survivor election actually pays.
The gap that remains is what the survivor must draw from the portfolio every year, plus enough on top for food, single-filer taxes, Medicare with a possible IRMAA surcharge, and the paid services a spouse was once providing at no charge. Divide by a withdrawal rate closer to 3.5% than 4%, because a survivor’s planning horizon can still stretch 25 or 30 years.
If the answer exceeds the portfolio, the practical options are a term or permanent life insurance policy sized to close the gap, downsizing to a smaller home within the same community, or a move closer to a child before either of you has to make that decision under pressure. Running this one calculation now is the single most protective step a couple in The Villages can take for the person who will eventually be there alone.
Plug your own numbers in here to see how long a survivor’s portfolio actually lasts at a 3.5% draw versus the classic 4%:
Editor’s note: This article has been updated to reflect the Social Security Administration’s official 2027 COLA of 3.6%, announced October 14, 2026, replacing earlier estimates. It also adds the specific income phase-out thresholds for the One Big Beautiful Bill’s $6,000 senior deduction ($75,000 for single filers, $150,000 for joint filers) and clarifies that the deduction runs through 2028.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.