The Retirees Who Left Florida for Good Say the Bill That Broke Them Was Not the One They Feared
Florida retirees planned carefully for the cost everyone warned them about, and it was not the bill that broke them. A different charge, one that arrives without warning and locks the exit behind it, has pushed hundreds out of the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Retirees in their late fifties and early sixties often ask whether moving to Florida was a mistake and what it will cost to relocate. Most arrived braced for the expected villain: homeowners insurance. What forced many out was something else entirely: a trap that is specific, unusual, and largely invisible until it lands.
Bill Retirees Feared Versus the One That Actually Landed
Insurance premiums in Florida have climbed sharply, and every retiree who bought a coastal or near-coastal property in the last decade planned for that line to keep rising. A recurring cost is at least visible. You see it renewal after renewal, you can shop carriers, raise a deductible, and fold the increase into next year’s withdrawal plan. A retiree on a fixed income can absorb a steadily rising line item far more easily than a single large demand that arrives with no warning.
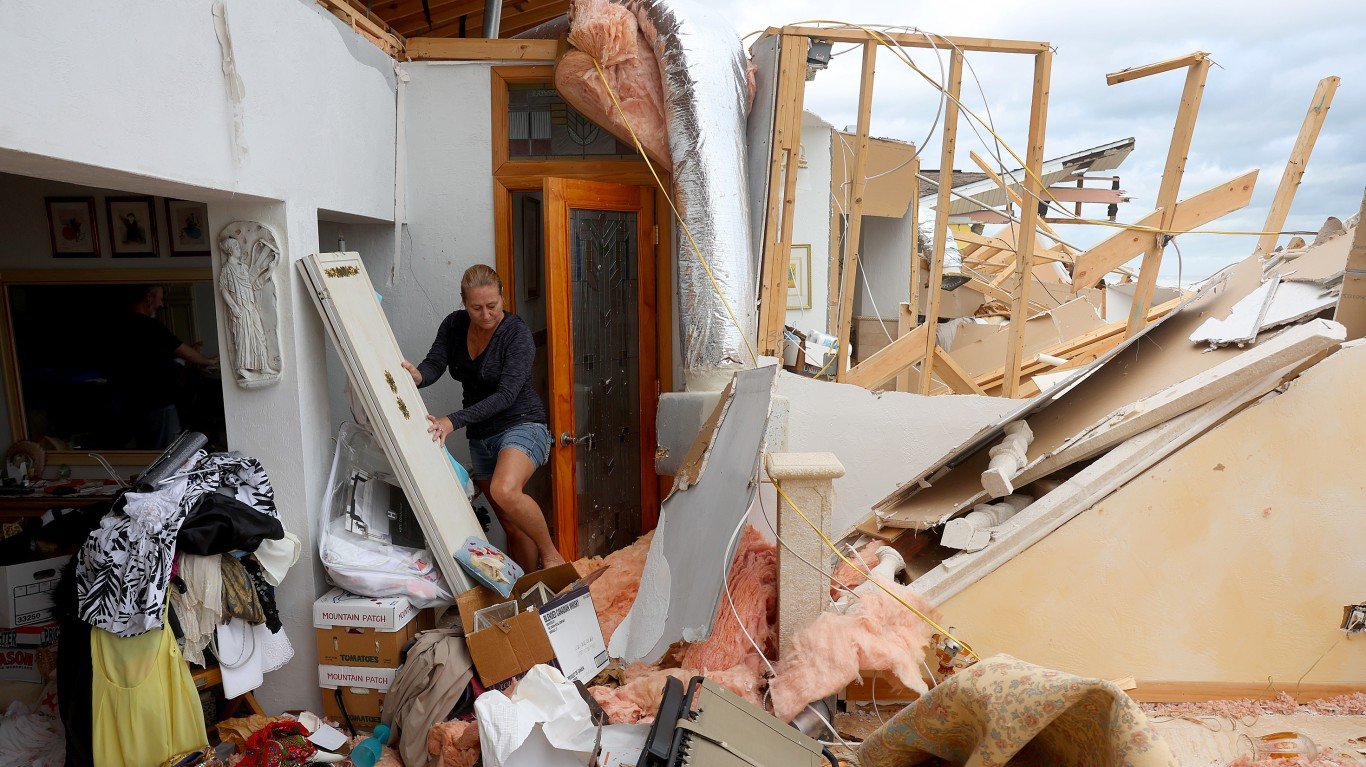
The bill driving people to the exits is the condominium special assessment triggered by Florida’s post-Surfside structural integrity regime. It arrives as a lump sum, is non-negotiable, cannot be shopped to another provider, and frequently arrives at the same moment it erases the resale value that would have funded the exit. One cost you can budget for. The other cashes a check you may not have.
Why the Assessment Math Breaks a Fixed-Income Budget
Florida’s structural safety law, Senate Bill 4-D, passed in the wake of the 2021 Champlain Towers South collapse in Surfside that killed 98 people. The law requires milestone structural inspections for condominium and cooperative buildings three stories or higher: generally at 30 years of age, or 25 years for buildings within three miles of the coast. Associations must also complete a Structural Integrity Reserve Study covering major structural components, with reserves that can no longer be waived or reduced by a membership vote for those items. A 2025 amendment extended the SIRS completion deadline to December 31, 2025, with a hard outer limit of December 31, 2026. Where prior boards had underfunded reserves for decades, the catch-up is being levied on current owners.
The real-world numbers are jarring. In 2024, residents at the Cricket Club in North Miami received special assessments as high as $134,000 per unit. At Mediterranean Village in Aventura, some owners faced bills reaching $400,000. These are not outliers: reported per-unit assessments across older Florida buildings have ranged from the mid-five figures to well into the six figures, depending on age, height, coastal exposure, and how badly reserves were underfunded. The structure is consistent: a lump sum paid on a schedule the board sets, with no option to opt out. One important caveat added by HB 913 in 2025: associations may now fund required reserve items through a bank loan or line of credit instead of a direct assessment, but only if a majority of all unit owners approves the alternative. That vote does not always happen, and not every board pursues it.
Average annual household expenditures ran about $78,535 in 2024, and retiree households typically run below that figure. The 2027 Social Security COLA is tracking toward 3.5%, with the official SSA announcement expected October 14, 2026. A raise in that range covers a rising insurance premium and not much beyond that. A $60,000 assessment landing on that same household is a full year of gross withdrawals in a single bite, and if it comes from a taxable IRA, it drags the next year’s IRMAA tier and ACA subsidy with it.
Trap That Closes the Exit Door
A unit with a known or pending assessment is harder to sell, and the resale math in the Florida condo market is already difficult. The statewide condo median stood at $295,000 in July 2026, flat year-over-year, while the single-family market posted a 4.9% gain. Condo inventory sat at 7.8 months of supply, nearly double the 4.5-month supply for single-family homes. Florida disclosure rules require sellers to provide association financials, recent board minutes, and information about pending assessments to prospective buyers. Buyers discount sharply for the number, demand closing credits, or simply walk. The owner who most needs to leave, the retiree whose fixed income cannot absorb the lump sum, is the same owner least able to sell without first paying the assessment that created the problem. The Case-Shiller national home price index registered 337.3 in July 2026, but older Florida condo stock has tracked well below that national line.
Documents to Demand Before You Sign
If you are looking at a Florida condo purchase, ask for the full Structural Integrity Reserve Study, the association’s current reserve balance measured against the study’s required funding level, the milestone inspection report and its findings, board meeting minutes from the last twelve months where assessments are discussed, any assessment already approved or under discussion, and the last five years of dues history. Florida law requires sellers to provide many of these documents, but the quality and completeness of what you receive matters as much as the paperwork itself. If any of those items are slow to arrive, treat that delay as an answer.
Who Is Actually Exposed, and What the Escape Math Looks Like
This risk is concentrated on owners of older mid-rise and high-rise condominiums, especially near the coast, and on association-governed cooperatives subject to the same rules. A single-family homeowner outside an HOA faces insurance, property tax reset risk, and roof age, but not this specific lump-sum mechanism.
For the retirees who have already left, the exit math has been consistent. Relocating to a lower-cost state with comparable purchasing power tends to lift the standard of living even before the assessment risk disappears entirely. Florida’s cost-of-living index reads 103.4 against a national benchmark of 100, with real income of $70,919. Tennessee posts a 91.9 cost-of-living index and $72,154 in real income. Texas comes in at 97.1 with $71,877. The spread is meaningful on a fixed income: the household that trims annual spending by roughly 10% through relocation frees several percentage points of withdrawal capacity, which at a 4% rate implies needing several hundred thousand dollars less in the portfolio to sustain the same lifestyle.
With CPI at 334.98 in August 2026 and inflation running at a 3.4% annual rate, the real purchasing power of a fixed monthly benefit continues to erode. Every dollar saved through relocation is a dollar the portfolio does not need to produce.
Plan on a portfolio that supports your target spending at a 3.5% to 4% withdrawal rate in the destination state’s cost basis. Hold twelve to eighteen months of that spending in cash so a surprise assessment cannot force a bad sale at a bad moment (the same early-withdrawal fragility we mapped out in a free guide on defending the first five years of retirement, here). Price your Florida exit against the reserve study rather than the Zillow estimate. The reserve study decides whether you stay or go. Read it before you buy, and read yours again before you list.
Editor’s note: This update refreshes the 2027 Social Security COLA estimate to 3.5% (from 3.3%) reflecting pre-announcement forecasts from TSCL, AARP, and Nowflation as of mid-October 2026, corrects the August 2026 CPI index level to 334.98, updates the Case-Shiller national index to the July 2026 reading of 337.3, adds real-world per-unit assessment figures from the Cricket Club and Mediterranean Village, incorporates the HB 913 loan-financing alternative for reserve funding, and notes the July 2026 Florida condo median of $295,000 at 7.8 months of supply.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.