The No Income Tax State Retirees Leave Fastest May Be the One They Move to First
Florida pulls in more retirees than any other no-income-tax state, yet nearly as many pack up and leave, and the costs that drive them out rarely appear on the spreadsheet they used to justify the move.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Anyone who’s done retirement planning has seen this. A couple sells in Illinois or New Jersey, figures out how much they save by avoiding state income tax, and moves to Florida. A few years later, some move again, often to the Carolinas, Georgia, or Tennessee, so does the state that pulls in the most retirees also lose them fastest? If so, what should that mean for anyone pricing a move today?
What Retiree Migration Data Really Shows About Florida
As it stands today, there are nine states that don’t tax wages: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. For retirees, two points matter. Washington charges a 7% tax on profits from selling stocks, bonds, and other capital assets held outside retirement accounts, but only above a threshold. And New Hampshire repealed its interest and dividends tax starting in 2025.
Among those states, Florida is the biggest draw. A 2026 HireAHelper study counted 45,696 inbound moves among adults over 65 and 44,881 outbound moves, for a net gain of only 815 retirees in 2025. That means about 98% of people leaving were also coming, while South Carolina led the nation in net gains in that age group.
So the headline holds up, at least in part. Florida gets the most older movers, but it loses almost as many, and the data can’t tell you how long the leavers stayed or why they left. Those 44,881 could be recent arrivals or people who’d been there 30 years, so calling it the “fastest” exit is an open conclusion, and you should read it as such.
Where Florida Collects the Money Instead
A state with no income tax still has to raise money somewhere, and where it does that decides who comes out ahead. Florida charges a 6% state sales tax, and some counties add a local surtax. The homestead exemption reduces the taxable value of a primary residence by up to $50,000. The Save Our Homes cap limits annual assessment increases to 3%, and that protection resets at your new address. So your tax bill is based on what you paid, which can be far higher than the seller’s assessed value. Overall, Florida’s income-adjusted state and local tax burden is still low: $5,110 per capita, compared with $10,828 in New York.
Insurance Costs That Wipe Out the Tax Savings
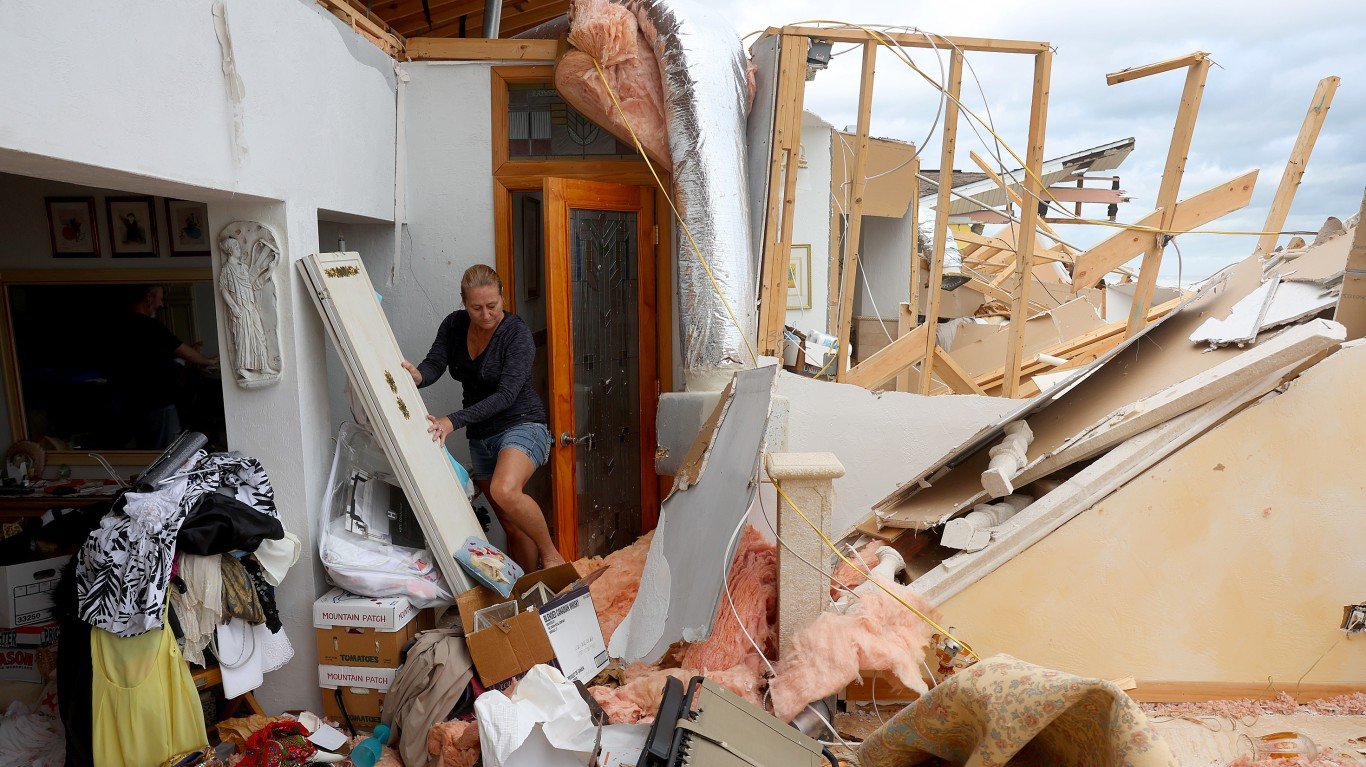
Some costs outside the tax code hit your budget just as hard. Florida homeowners’ premiums rose 75% between 2021 and 2025, compared with 38% nationally. One estimate puts the state’s average premium at about $8,471 a year, compared with a national average of $2,765, a gap of $5,706. Living costs are higher too. On the Bureau of Economic Analysis price index, where 100 is the national average, Florida sits at 103.414. Tennessee is at 91.87 and South Dakota at 88.586.
Here’s how that plays out for a couple. Start with average household spending of $78,535, which covers all households, not just retirees, and adjust it to Florida prices. That comes to about $81,200. Next, subtract two average Social Security checks of about $2,031 a month each, or $48,744 a year. That leaves a gap of roughly $32,500 a year. Withdrawing 4% a year to cover that takes a portfolio of about $812,000.
Now say they left a state with a hypothetical 5% income tax. On those withdrawals, they’d save about $1,600 a year. The extra insurance cost alone is about 3.5 times that dollar amount. At 4%, that adds another $142,650, bringing the target to roughly $955,000. Medicare Part B, which covers doctor visits, costs $202.90 per person per month, and it costs the same no matter which state you live in, so it doesn’t help either side of the comparison.
Why Retirees Often Leave a Few Years Later
You see the tax saving on day one. The insurance renewal, the tax bill based on your purchase price, the first full summer of air conditioning, and the first serious dealings with local doctors all show up later. Our conclusion is that retirees who moved for the number they could calculate run into the numbers they couldn’t, and the decision to leave takes shape once all of those have come. The Wall Street Journal featured one couple who moved from Illinois to Arizona. That state has an income tax, but their property tax dropped from more than $13,000 a year to about $3,600. The biggest savings came from the home tax.
How to Run the Full Cost Comparison Before You Move
Before you commit, line up five figures for each place you’re considering:
- State income tax on your actual mix of withdrawals.
- Property tax based on your purchase price after exemptions.
- Sales tax on what you really spend.
- An insurance quote for the specific address.
- How many doctors are available in that county.
For a typical couple heading to Florida, a 4% withdrawal plan needs closer to $955,000 than $812,000, unless they cut about $5,700 a year somewhere else in the budget. The 4% rule itself is also under more scrutiny than it used to be (we made the case for an income-first replacement in a free report here). Waiting to claim Social Security raises the guaranteed income floor and reduces the gap a portfolio has to cover. Zero income tax gets most of the attention, but the insurance bill and the tax reset on your home are more likely to decide whether the move pays off.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.