Is Cincinnati the Most Underrated Place to Retire in the Midwest? Here’s What It Takes
Cincinnati looks like a bargain for retirees, and Ohio barely taxes retirement income. Yet one bill keeps climbing for decades, and where you buy decides how hard it hits. Here is the portfolio a couple needs before they move.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
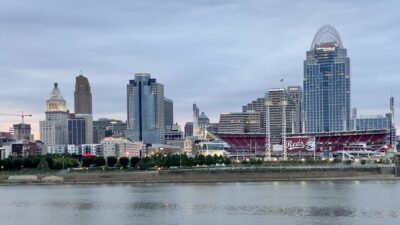
Plenty of retirees never put Cincinnati on their list of retirement destinations, but they might want to get doing so. Home prices make a strong case for this switch.
Zillow Group (NASDAQ:Z | Z Price Prediction) puts the average home value in Anderson Township’s 45255 ZIP code at about $351,457, and North Avondale comes in around $294,589.
Coastal buyers haven’t seen numbers like that in years. So is the Queen City the Midwest’s best-kept retirement secret? Below we look at what it actually costs to retire there, the portfolio it takes, and the one local tax that changes the math.
What a Comfortable Cincinnati Retirement Costs
We’ll start with a benchmark, as the average U.S. household spent $81,905 last year, according to the BLS Consumer Expenditure Survey. On the BEA’s price index, where 100 is the national average, Ohio comes in at 92.774.
Adjusted to Ohio prices, a couple’s budget comes to about $76,000 a year, or around $6,330 a month. That figure works as a generous ceiling, since retired couples usually spend less than the average working household.
Housing is where Cincinnati pulls ahead. The median rent for a house is about $1,505 a month. Owners pay property tax instead, and Ohio’s effective rate averages 1.22%.
On a $351,000 home, that works out to about $4,300 a year, or around $360 a month. Medicare Part B costs $202.90 a month per person, so about $406 for a couple, plus a $283 deductible. Joint filers pay the base premium on income up to $218,000.
Ohio keeps state taxes light for retirees and leaves Social Security untaxed benefits. Ohio’s 2026 tax formula starts at $332, plus 2.75% of taxable income above $26,050. A couple withdrawing $37,500 from an IRA would owe about $647 before personal exemptions and tax credits.
The state’s retirement income credit then takes off up to $200, as long as modified income stays under $100,000. Northern Kentucky suburbs across the river fall under a different state tax system, which we’ve covered separately.
Turning That Budget Into a Portfolio Target
In 2026, a retired couple where both spouses collect benefits receives an estimated $3,208 a month, or $38,496 a year, on average. Subtract that from the budget, and you’re left with a gap of about $37,500. Using a 4% withdrawal rate, covering that gap takes about $937,000. If you’d rather use a more conservative 3.5% to plan for a 30-year retirement, the target rises to around $1.07 million.
A solo retiree should assume a budget about two-thirds of the couple’s, or around $50,700. A typical retired worker’s benefit of $2,071 a month totals $24,852 a year. The gap comes to about $25,800, with a portfolio target near $645,000 at 4%.
When you claim, it also moves the target. The maximum benefit at full retirement age is $4,152 a month, and every dollar of extra benefit is a dollar your portfolio no longer has to produce. Benefits also rise 3.6% next year with the inflation adjustment.
Property Tax Is Cincinnati’s Real Retirement Tax
Ohio barely touches retirement income, but it leans hard on homes. Metro home prices are up 49.9% over five years and 3.77% over the past year. Property reassessments can increase tax bills, but Ohio’s tax reduction rules prevent many property value increases from producing proportional tax hikes. Actual bills depend on local levies and effective tax rates. Rates also swing by school district, so two similar houses a few miles apart can carry very different bills.
Ohio’s standard homestead exemption reduces a qualifying home’s assessed value for tax purposes, with a $41,000 income limit for 2026. Most applicants must be at least 65 or permanently disabled, although certain exceptions apply.
Ohio leaves Social Security out of that income figure, and Roth withdrawals don’t count toward it either. Keeping taxable IRA withdrawals modest lets a couple stay under the cap, and both the exemption and the retirement credit stay available. The county auditor determines final eligibility.
Is Cincinnati Underrated? A Fair Verdict
For most retirees, Cincinnati is underrated, offering major hospital systems, pro sports, a deep arts scene, river views and neighborhoods with real character. You also get hills, gray winters, and an airport across the state line in Kentucky. Even the city’s pricier parts are reasonable, with Oakley’s median list price at about $430,817.
A couple with typical Social Security income and a paid-off home needs around $940,000 to $1.07 million. That represents a 3.5% to 4% withdrawal rate, though the case against relying on 4% is worth reading before you lock in a number (we laid out why that rule wobbles now, and the income-first alternative, in a free guide here). For someone retiring alone, the target is about $645,000.
Mixing Roth and taxable-account withdrawals in with IRA money can keep Ohio income low enough to preserve the homestead break.
The biggest variable is city versus suburb. That choice picks the school district, your school district sets your property tax, and property tax is the bill that will grow the most over a 30-year Cincinnati retirement.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.