How to Build $9,950 a Month in Dividend Income Without Owning a Single Bond or Selling a Single Share

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
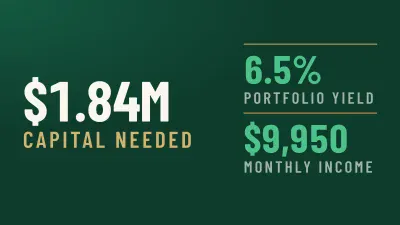
If bonds burned you when rates jumped, you probably still want what they promised: a steady check that arrives whether the market cooperates or not. The goal here is $9,950 a month, or $119,400 a year. It comes from six stocks and funds with zero bonds or bond funds in the portfolio, and the goal is to cover bills without selling shares.
Three Yield Levels, Three Price Tags
The math fits on one line. Income divided by yield equals the capital you need.
- Conservative (3% to 4%): dividend growers and wide-ranging index funds. $119,400 divided by 0.035 equals about $3.41 million. It takes the most money, but payouts tend to grow, and the principal tends to appreciate.
- Moderate (5% to 7%): high-dividend equity funds, REITs, utility funds, and covered call funds. $119,400 divided by 0.065 equals about $1.84 million. Dividend growth slows, and covered calls cap your upside.
- Aggressive (8% to 14%): business development companies, mortgage REITs and leveraged option funds. $119,400 divided by 0.10 equals $1.19 million. Cuts and principal erosion come with the territory.
The editor’s portfolio has an estimated 7.37% weighted distribution rate using the yields below, although the $1.84 million target assumes a more conservative 6.5%.
Six Holdings Writing Your Paycheck
Nuveen S&P 500 BuyWrite Income Fund (NYSE:BXMX), 20%: it owns S&P 500 stocks and sells call options to generate income. Its distribution rate is about 9.6%, with quarterly payments. The catch: covered calls limit some upside, and distributions can include return of capital.
This State Street ETF, the SPDR Portfolio S&P 500 High Dividend ETF (NYSEARCA:SPYD), 15%: it spreads your money across the S&P 500’s highest yielders, including utilities, REITs, banks and energy companies, and yields about 4.2%. The catch: its quarterly checks swing. One paid about 13 cents a share in late 2021, and the next paid about 65 cents.
With 15%, STAG Industrial (NYSE:STAG) owns single-tenant warehouses, keeps 96%[1] occupancy, and yields about 4.2%. Cash rents on new and renewed leases rose 24%[1], but shares gained only about 5% over five years, so the dividend does almost all the work.
Fidus Investment (NASDAQ:FDUS), 15%: this business development company lends to smaller private companies with revenue between $10 million and $150 million. That’s where this bond-free portfolio still has credit risk. It yields about 11.6%, counting its extra payout, or 9.2% on the base dividend alone. It did, however, book $10.9 million[2] in net realized losses last quarter.
The lineup’s best dividend grower, Altria (NYSE:MO | MO Price Prediction), takes 15%. It yields about 5.8%, and its August raise was its 61st increase in 57 years[3]. Industry cigarette volume, however, fell an estimated 5% last quarter.
Reaves Utility Income Fund (NYSEAMERICAN:UTG), 20%: It holds utility and infrastructure stocks and pays monthly, yielding about 7.9%. In July, it raised its monthly payout to 21 cents. The catch: shares are down about 9% this year, and utilities feel pressure when rates rise.
Why a Smaller Yield Can Pay You More Later
The 10-year Treasury yields 5.1%[4]. Your 6.5% portfolio pays only slightly more than that, and most of its payouts barely grow.
Compare it with the conservative path. Put that same $1.84 million in 3.5% dividend growers, and you’d start with just $64,400 a year. If those dividends grow 8% a year, the income roughly doubles in nine years and passes the flat $119,400. Fund the full target at 3.5%, and your $119,400 grows to about $238,700 by year nine. High-yield checks rarely compound like that.
Who Should Own This Mix, and What Could Shrink the Check
This portfolio fits someone who needs the full check now, has roughly $1.84 million, and can accept income that mostly holds steady instead of growing.
- Add up what you actually spend in a year. If it’s $8,000 a month, you need $1.48 million at 6.5% instead of $1.84 million.
- Revisit Fidus at its base yield of about 9%. If your budget only works with the extra dividend included, you’re counting on money the board can drop at any time.
- Review SPXX’s current distribution rate and payout history before allocating 20% of your portfolio here.
A $9,950 monthly check without bonds is realistic at $1.84 million. Just expect that check to stay about the same size for years. The whole point of a portfolio like this is that the shares stay put while the checks arrive, and we walked through how to build that kind of dividend ladder step by step in a free guide.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.